Verra Approves First Carbon Credits Under Food Loss and Waste Methodology

Verra Approves First Carbon Credits Under Food Loss and Waste Methodology
Verra has approved the first carbon credits generated under its methodology for reducing food loss and waste, opening a new pathway for food rescue projects to access carbon market finance.

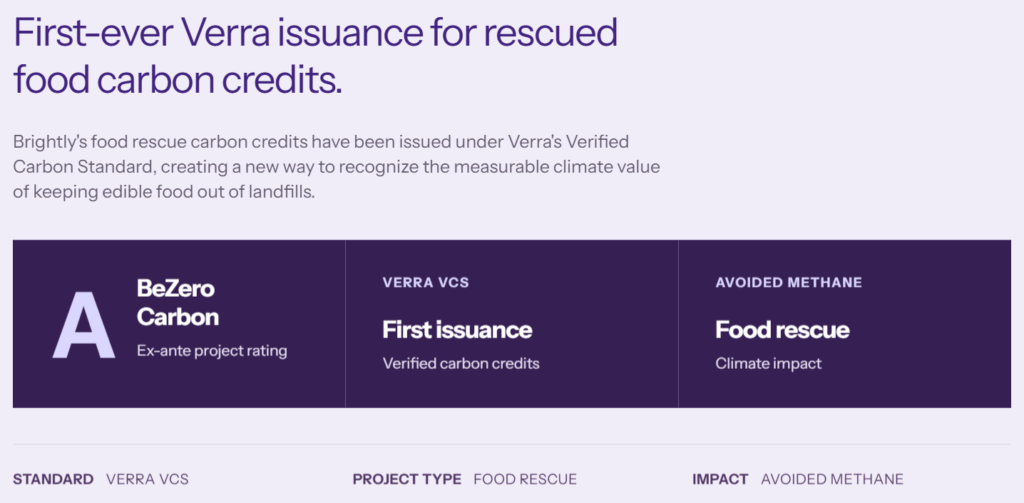
The credits come from the Brightly – Reducing Food Loss and Waste project in the United States. The project generated 721,649 Verified Carbon Units (VCUs) by redirecting surplus food to people instead of allowing it to enter waste streams.

The milestone gives food rescue organizations a new way to monetize avoided methane emissions while addressing food insecurity. It also broadens the types of activities that can earn verified carbon credits. This goes beyond traditional areas like forestry, renewable energy, and methane capture.

Verra approved the credits under its VM0046 Methodology for Reducing Food Loss and Waste, v1.0. Mandy Rambharos, CEO, Verra, remarked: 

“Food waste is one of the most overlooked sources of methane, and preventing it is one of the most solvable issues. This first issuance under VM0046 proves that keeping food out of landfills can be measured with integrity, and that carbon markets can move finance to the organizations making it happen. It also shows why Verra keeps broadening its methodology portfolio: there are many ways to cut emissions, and each one needs a credible pathway to carbon finance.”

721,649 Credits Put Food Rescue on the Carbon Map

Brightly’s project covers food rescue activities carried out between March 2020 and December 2023. During that period, participating organizations rescued 15.3 billion pounds of surplus food. After applying historical baselines and accounting for project-related emissions, 3.1 billion pounds of the rescued food qualified for carbon crediting.

That activity produced 721,649 VCUs, with each credit representing one tonne of avoided greenhouse gas emissions. The credits received an A ex-ante rating from BeZero Carbon, indicating a high likelihood that each credit represents one tonne of avoided emissions.

SCS Global Services, a Verra-approved body, independently validated and verified the project. Then, Verra reviewed and approved the issuance.

The first issuance follows Verra’s registration of Brightly’s project in May 2026. At that stage, Verra expected the project to save about 167 million pounds of food over seven years, from 2020 to 2027. It would also cut emissions by about 115,118 tonnes of CO2e.

The latest issuance reflects verified historical activity rather than the entire future potential of the project.  
Brightly – Reducing Food Loss and Waste
Source: Brightly

How Verra’s Food-Waste Methodology Works

Verra’s VM0046 methodology has been active since July 12, 2023. It falls under the Verified Carbon Standard’s waste-handling and disposal sector.

The methodology allows projects to quantify emissions avoided when food that would otherwise become waste remains in the human food supply chain. Projects can operate at several points along the food chain, including:

  • Farms,
  • Food processing facilities,
  • Retailers,
  • Food-service and hospitality businesses, and
  • Households.

The methodology measures the emissions that would happen if the food went to a waste site, like a landfill. That makes it different from carbon removal projects. The credits represent avoided emissions, primarily by preventing food from decomposing in waste streams and generating methane.

The methodology also addresses additionality. Brightly establishes a conservative historical baseline for participating organizations, with only food rescued above that baseline eligible for crediting. This ensures that credits show real climate impact. They don’t just reward current food-rescue efforts.

A Billion-Tonne Waste Stream With a Climate Cost

The potential market for this type of project is large because food loss and waste occur across the global food system.

The UN Environment Programme estimates that 1.05 billion tonnes of food waste were generated in 2022 at the retail, food service and household levels. That amounted to 132 kilograms per person and nearly one-fifth of food available to consumers. Households alone wasted more than 1 billion meals per day.
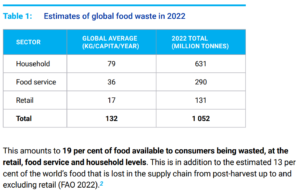
global food waste in 2022
Source: UN Environment Programme

Food loss also occurs before food reaches consumers.

The Food and Agriculture Organization estimates that 13.2% of food is lost worldwide from harvest to retail. Additionally, 19% is wasted at retail, food service, and households, according to 2024 UNEP statistics. Together, food loss and waste account for an estimated 8% to 10% of global greenhouse gas emissions, according to FAO.

This gives carbon markets a large potential emissions reduction opportunity. However, not every tonne of wasted food automatically translates into a carbon credit.

Projects must establish baselines, quantify eligible activity, and account for emissions associated with the intervention. VM0046 provides the framework for doing that.

Carbon Revenue Could Help Scale Food Rescue

The Brightly project connects climate finance with food rescue. The company works with food rescue organizations that collect edible surplus food and redistribute it instead of allowing it to enter waste streams. The organizations can then receive revenue from carbon credit sales.

Feeding America said the majority of net proceeds from credit sales will return to participating food rescue organizations. The funding can cover costs like trucks, drivers, refrigeration, staff, and other infrastructure needed to recover and distribute food.

The scale of the network has also expanded significantly.

Brightly partners with 198 Feeding America food banks and 28 independent food rescue groups. This helps us reach communities in every U.S. state and about 97% of U.S. counties. Together, these organizations rescue more than 5 billion pounds of surplus food each year, according to Feeding America.
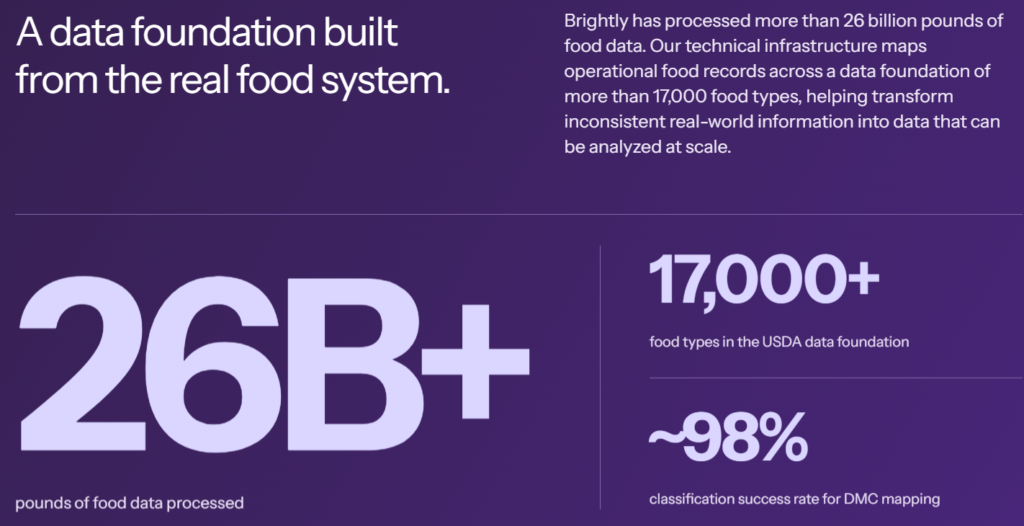
Brightly food rescue
Source: Brightly

This can lead to a feedback loop. More carbon revenue helps organizations recover more food. This, in turn, can create further measurable emissions reductions.

Carbon Markets Broaden Beyond Forests and Renewables

The first food-loss-and-waste issuance comes as the broader carbon credit market continues to develop.

The World Bank reported that global carbon credit issuances increased 8% between 2024 and 2025, although issuance remained about 20% below its 2022 peak. Independent crediting mechanisms still accounted for about 70% of total issuance.

At the same time, carbon credit retirements fell by more than 10% in 2025. Voluntary uses made up over 80% of retired credits. Meanwhile, companies and other buyers signed around $12 billion in offtake agreements for future carbon credits. This amount is three times what was recorded in 2024.

Prices also varied sharply by project type. The World Bank said carbon credit prices declined slightly across 2025, but higher-quality and compliance-eligible credits continued to command premiums. CORSIA-eligible credits, for example, traded at around $15 to $22 per tonne, compared with roughly $1 to $14 for most other credit types.

For food-loss-and-waste projects, the key question will be whether buyers place a premium on the combination of methane avoidance, food security, and measurable local impact. 
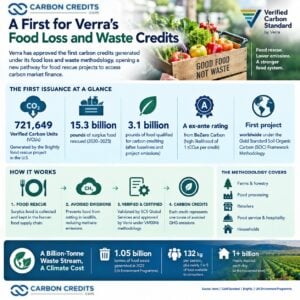
Verra food waste carbon credits

Food Rescue Enters the Carbon Credit Economy

Verra’s first VM0046 issuance does more than create another category of carbon credits. It demonstrates that food rescue can be measured through a standardized carbon methodology and converted into a tradable environmental asset.

The Brightly project also shows how carbon finance can potentially reach organizations that traditionally depend heavily on grants and donations.

With 721,649 credits now approved from the first issuance, the project provides an initial test of demand for this new credit type. Future projects could expand the market to other parts of the food supply chain, including retailers, food processors, farms, and food-service businesses.

The climate opportunity is significant. Over 1 billion tonnes of food waste are created each year at the consumer level. This waste contributes to nearly 10% of global greenhouse gas emissions.

VM0046 does not solve that problem by itself. But it gives project developers a standardized way to measure a portion of the emissions avoided when food stays in the human food system. For carbon markets, that creates a new pathway to finance climate action while also reducing food waste and supporting food security.

The post Verra Approves First Carbon Credits Under Food Loss and Waste Methodology appeared first on Carbon Credits.
Europe’s Soil Carbon Market Gets a First: Gold Standard Credits Issued in France and Belgium

Europe’s Soil Carbon Market Gets a First: Gold Standard Credits Issued in France and Belgium

Europe’s soil carbon market has reached a new milestone. The European Soil Revitalization Programme, covering farms in France and Belgium, has issued the first carbon credits worldwide under the Gold Standard Soil Organic Carbon (SOC) Framework Methodology.

South Pole, agricultural technology company Gaïago, and Gold Standard announced the first issuance on October 6, 2026. The initial issuance covers 6,000 verified hectares. The wider program includes 727 farms and could expand to more than 39,282 hectares.

At full enrollment, the project is forecast to remove 264,174 tonnes of CO₂ equivalent (tCO₂e) during its first crediting period.

The milestone comes as Europe builds a stronger policy framework for soil health and carbon farming. The European Commission says 60% to 70% of EU soils are unhealthy, while new EU rules are creating a formal system for certifying carbon farming activities.

That could create a growing role for high-quality soil carbon projects in Europe’s climate market.

A First for Gold Standard Soil Credits

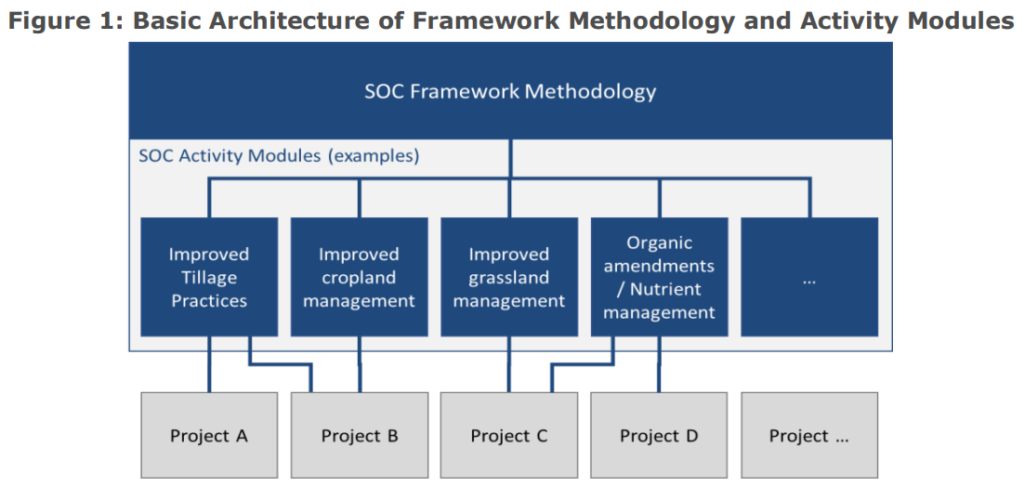
The European Soil Revitalization Programme is the first project worldwide to issue credits under Gold Standard’s Soil Organic Carbon Framework Methodology. Gold Standard launched the framework to measure changes in soil carbon and greenhouse gas emissions when farmers adopt improved agricultural practices.

The framework can cover both emissions reductions and carbon sequestration in soils. It also allows different approaches to measure soil carbon, including direct field measurements, scientific models, and approved default factors.

Sarah Leugers, Chief Growth Officer at Gold Standard, said:

“As the first project worldwide to issue credits under our Soil Organic Carbon Framework Methodology, the European Soil Revitalization Programme shows how rigorous standards can unlock vital finance for sustainable land management. We congratulate Gaïago and South Pole on this important milestone.”

Basic Architecture of Framework Methodology
Source: Gold Standard

For the French and Belgian project, the specific activity module covers biostimulants for soil revitalization. The project combines this approach with other regenerative farming practices, including reduced or zero tillage and year-round cover crops.

The program began in 2022 and has a planned 20-year operational horizon. South Pole has worked with Gaïago since launch as the carbon asset development partner. They help develop the project and complete the certification and verification process.

The project uses the UN Food and Agriculture Organization’s GSOC monitoring, reporting, and verification protocol (MRV). It also aligns with the FAO’s RECSOIL initiative.

6,000 Hectares Mark the First Step

The first issuance is based on the program’s initial 6,000 verified hectares. The full program is much larger.

  • Across its 727 participating farms, the project could eventually cover more than 39,282 hectares and remove an estimated 264,174 tCO₂e during its first crediting period.

That works out to roughly 2.5 tCO₂e per hectare per year based on the project’s full enrollment forecast.

The first group of participating farms has already produced measurable results. The project developers’ latest calculations from August 2026 show that the first cohort removed about 3.1 tCO₂e per hectare each year over the last three years.

The developers have not publicly disclosed the exact number of carbon credits contained in the inaugural issuance in the announcement.

That distinction matters. The 6,000-hectare figure is the verified area covered by the first issuance, not a statement that 6,000 credits were issued. As more farms join the program, the project could become a meaningful source of European soil-based carbon removals.

Why Soil Carbon Matters to European Farmers

The project arrives against a major soil-health problem. The European Commission says 60% to 70% of EU soils are in an unhealthy state. Soil degradation costs the EU more than €50 billion each year, according to the Commission.

Loss of soil organic carbon is one of the main forms of degradation. Healthy soil does more than store carbon. It helps retain water, supports crops, protects biodiversity and improves the resilience of farmland. That gives soil carbon projects a different value proposition from credits focused only on carbon removal.

Regenerative practices can potentially improve farm conditions while also creating carbon market revenue.

For farmers, however, changing agricultural practices can involve upfront costs and uncertainty around yields. Carbon finance can help offset some of those costs by creating another source of income.

That is a key part of the European Soil Revitalization Programme. The project aims to enhance soil structure, fertility, and water retention. It also boosts farm resilience and increases soil carbon stocks.

Gold Standard Tightens the Rules for Soil Carbon

Measuring soil carbon is not as simple as measuring emissions from a factory. Carbon levels can vary across fields and change with weather, farming practices and soil conditions. Carbon stored in soil can also be released later if management practices change.

  • Gold Standard has therefore placed strong requirements around additionality, permanence, uncertainty and measurement.

Its SOC framework lets projects use various measurement and modeling methods. However, it requires that uncertainty be addressed in the calculations.

In September 2025, Gold Standard also released specific guidelines for using soil organic carbon models. The guidelines set out a seven-step process covering model selection, data collection, calibration, validation, prediction, and verification.

The goal is to make soil carbon estimates more consistent while still allowing models to reflect local soil and climate conditions. That could become increasingly important as more agricultural projects seek carbon market certification.

Europe Builds a New Framework for Carbon Farming

The Gold Standard issuance is happening alongside a separate European policy push. In July 2026, the European Commission adopted new certification methodologies under the Carbon Removals and Carbon Farming Regulation (CRCF).

The rules cover three types of carbon farming:

  • Agriculture and agroforestry on mineral soils,
  • Rewetting and restoration of peatlands and other organic soils, and
  • Afforestation.

The EU states that these activities offer benefits beyond just carbon removal. They also enhance climate resilience, protect biodiversity, and improve food and biomass security. This creates an emerging European framework for certifying carbon farming.

The Gold Standard program is separate from the EU’s CRCF certification system. However, both developments point toward a larger focus on measuring and rewarding carbon stored in agricultural land.

For project developers, that could mean more opportunities to finance regenerative farming. For buyers, it could create a wider pool of European carbon removal projects.

Soil Carbon Credits Command Premium Prices

Soil carbon is emerging as a premium segment of the voluntary carbon market. In January 2026, Microsoft agreed to buy 2.85 million soil carbon removal credits from Indigo Carbon over 12 years. Reuters reported that Indigo’s historical credits sold for 60–80 per tonne, implying a potential deal value of 171 million–228 million.

Microsoft’s disclosed purchases from Indigo now total 2.95 million tonnes, including earlier purchases of 40,000 tonnes in 2024 and 60,000 tonnes in 2025.

Europe is also seeing significant transactions. In June 2026, South Pole facilitated the sale of 29,000 Verra-certified soil carbon credits from eAgronom for €1.46 million, equal to about €50 per tonne.

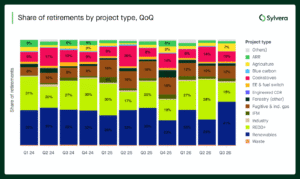
These transaction prices are much higher than in the broader VCM. In Q3 2026, the average retired credit price was $6.92/t. This shows how much more buyers will pay for high-quality agricultural removals. The volume of retired credits also increased for the quarter, per Sylvera’s report.

credit retirements by project type q3 2026
Source: Sylvera

A New Test for Europe’s Soil Carbon Market

The first Gold Standard soil issuance does not mean soil carbon has become a mature market. It does, however, remove one important barrier:

  • A large European agricultural project has now demonstrated that soil carbon can be certified and issued under Gold Standard’s dedicated framework.

The next challenge is scale. The program must expand beyond its initial 6,000 hectares while maintaining reliable measurement and verification. More projects will also need to show that soil carbon gains are real, additional and durable.

Europe’s policy environment is moving in the same direction. The EU aims to achieve healthy soils by 2050, while its carbon-farming rules are creating new certification pathways for agricultural carbon projects.

If more farmers can combine regenerative practices with credible carbon revenue, soil could become an increasingly important part of Europe’s carbon-removal market.

The first Gold Standard issuance is therefore more than a project milestone. It is an early test of whether carbon finance can help turn healthier European farmland into a measurable climate asset.

The post Europe’s Soil Carbon Market Gets a First: Gold Standard Credits Issued in France and Belgium appeared first on Carbon Credits.
Pentagon Bets on Space Solar Power as Solar Market Hits Record Growth

Pentagon Bets on Space Solar Power as Solar Market Hits Record Growth

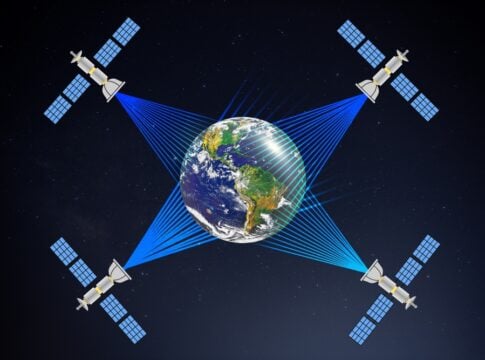
The U.S. Department of War is putting new money behind a technology that could change how solar power reaches the ground: beaming electricity from space. Virginia-based startup Overview Energy received a contract through the Department of War’s Operational Energy Capability Improvement Fund (OECIF). The company will design, build, and test a ground-based homing beacon for its planned space solar system.

The contract value was not disclosed.

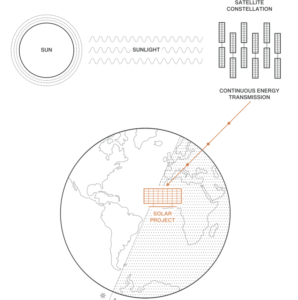
The beacon is a key part of Overview’s plan. It would allow satellites to identify and authenticate receiving sites on Earth before sending power to them. The company says its satellites will collect sunlight in orbit and convert it into a safe, invisible beam of near-infrared light. It plans to test the system in space in 2028, with its first geosynchronous-orbit satellites targeted for deployment from 2030. 

The Pentagon Wants Solar Power Without Fuel Convoys

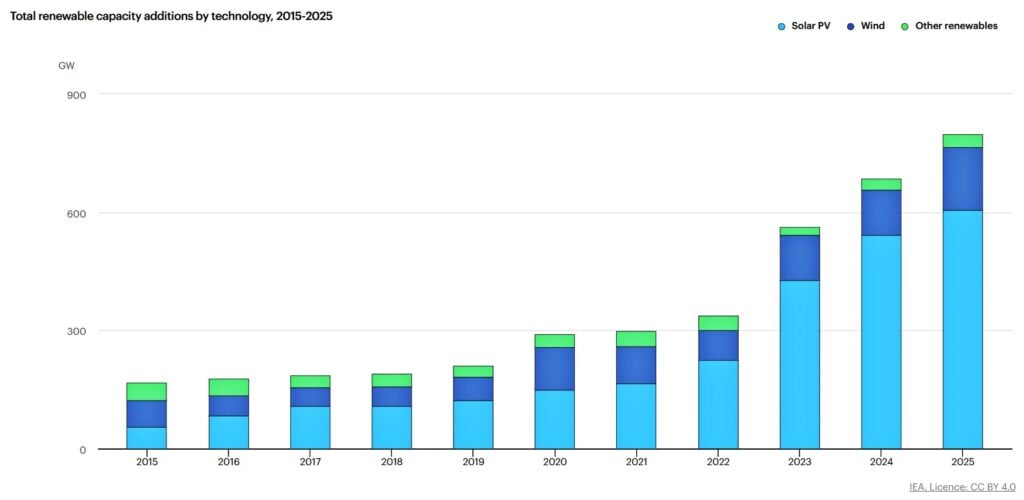
The project comes as solar power is already expanding at record speed on Earth. The International Energy Agency (IEA) says solar PV additions topped 600 GW in 2025, while total renewable capacity additions reached 800 GW.

Now, U.S. energy and defense agencies are exploring whether some of that growth can move beyond the planet. 

Remote military bases can depend on fuel deliveries to keep generators running. Those supply lines can be expensive, difficult to protect, and vulnerable in conflict zones. Space-based solar power could offer another option.

Overview says its system could send power to remote or contested locations without regular fuel shipments. Satellites could also shift power between receiving sites as demand changes. That makes the technology especially interesting for military operations where reliable energy is difficult to provide.

The OECIF program is designed to support advanced technologies before they reach commercial use. The program works with military users to test new energy systems under real operational requirements.

Overview Energy is not starting from scratch. In May, the Air Force awarded the company a separate contract to study how space-based solar power could support military operations in constrained and contested logistics environments.

The latest contract focuses on a smaller but critical piece of the system: making sure the power beam reaches the right place.

A Beacon Will Tell Satellites Where to Send Power

The homing beacon would be installed at a receiving site on the ground. A satellite would use the beacon to locate the site and establish a secure connection before sending power. The system requires an active and authenticated beacon before transmission begins, according to Overview.

Overview Energy space-based solar
Source: Overview Energy

That security feature is important because a power beam cannot simply be pointed toward a general area. The satellite needs to know exactly where the receiver is and confirm that it is an authorized destination.

Overview plans to use near-infrared light to transmit the energy. The company says this approach would allow its satellites to deliver power to existing and future utility-scale solar infrastructure.

The system is designed around satellites in geosynchronous orbit (GEO). At that altitude, a satellite can remain aligned with the same area of Earth as the planet rotates.

Overview says this could allow its satellites to collect sunlight continuously rather than only when solar panels on the ground are exposed to sunlight. The company has already demonstrated power beaming from a moving airborne platform, testing the tracking and pointing technology that will be needed for its orbital system.

Overview Targets a 2028 Space Demonstration

The next major milestone is the company’s planned 2028 space demonstration. Overview plans to integrate the Pentagon-funded beacon into its first satellite. The company then expects to use the ground hardware as part of a larger GEO constellation targeted for deployment beginning in 2030.

These are company targets, not confirmed commercial launch dates. The 2028 test will matter because the full space-to-ground system has not yet been proven in orbit.

Several questions remain, however. The system must show that it can maintain a precise connection over the long distance between orbit and Earth. It must also demonstrate acceptable conversion and transmission efficiency while meeting safety requirements.

Launch costs are another major issue. Space-based solar systems require large structures and power-generation equipment to be placed in orbit. The economics will depend heavily on how cheaply those systems can be manufactured, launched, and maintained.

Overview has also attracted commercial interest. In April 2026, the company reached an agreement with Meta that gives the company early access to up to 1 GW of planned capacity. Overview expects commercial power delivery around 2030, although that timeline remains a company goal.

The US Is Funding Multiple Space Solar Approaches

Overview is part of a wider U.S. push into space-based energy. Another company, Katalyst Space, received an OECIF award in September to develop and launch robotic spacecraft that could assemble a large power-beaming system in orbit and transmit electricity back to Earth.

Its approach is different. Katalyst plans to use microwaves, while Overview is developing near-infrared transmission.

The Air Force Research Laboratory has also spent years studying space solar power. Its Space Solar Power Incremental Demonstrations and Research Project, or SSPIDR, is examining how satellites could collect sunlight, convert it to radio-frequency energy, and transmit it to ground-based receiving antennas.

The Arachne flight experiment is a major part of that work. It is designed to test solar power generation, beamforming, and wireless power transmission.

DARPA is separately developing technologies for airborne optical power transmission that could create more flexible wireless energy networks.

Together, these programs show that space-based power is moving beyond a purely theoretical idea. Yet, the technology remains at the demonstration stage.

Space Solar Is Arriving as Earth Solar Hits Records

The interest comes at a time when solar power is already dominating new renewable energy growth. The IEA says global renewable capacity additions reached 800 GW in 2025, up 16% from the previous year. It was the 23rd consecutive year of record renewable expansion.

Total renewable capacity additions by technology, 2015-2025
Source: IEA

Solar PV made up more than three-quarters of those additions. More than 600 GW of solar capacity was added globally, taking total installed solar PV capacity to about 2,800 GW.

China remains the biggest driver. It added nearly 500 GW of renewable capacity in 2025, including about 370 GW of solar and 117 GW of wind.                                                                                

The IEA expects renewable power capacity to grow by another 4,600 GW between 2025 and 2030, with solar PV accounting for nearly 80% of that increase. But conventional solar still faces limits.

Solar panels on Earth do not generate power at night, and their output can drop because of clouds, weather, and seasonal changes. Grid bottlenecks are also becoming a bigger problem as more renewable projects seek connections.

The IEA has identified more than 2,500 GW of renewable, storage, and large-load projects waiting in grid queues worldwide. Space solar is being developed partly as a way to overcome some of those limits.

Pentagon Bets on Space Solar Power

From Climate Technology to Energy Security

Space solar power is not yet a proven low-cost alternative to conventional solar. For now, its strongest case may be energy security.

The Pentagon is interested in whether space-based power can provide electricity to locations where fuel deliveries are difficult or dangerous. At the same time, commercial companies see potential for supplying electricity to grids without building an entirely new ground-based power network.

That dual-use potential is helping attract government funding.

The climate benefits could become important if space solar eventually replaces fossil-fuel generation or reduces the need for diesel generators at remote facilities. But that outcome remains unproven.

For now, the key milestone is much simpler: can a satellite safely and efficiently send usable power to Earth? Overview’s 2028 demonstration should provide the first major answer.

If it works, space solar could move from a long-running science project toward a real energy technology. If it fails, the industry will gain valuable data on what still needs to change. Either way, the Pentagon’s latest investment shows that the race to expand solar power is no longer limited to the ground.

The post Pentagon Bets on Space Solar Power as Solar Market Hits Record Growth appeared first on Carbon Credits.
Amazon’s $3.9B UK Clean Energy Bet Pushes Renewable Portfolio Past 1 GW

Amazon’s $3.9B UK Clean Energy Bet Pushes Renewable Portfolio Past 1 GW

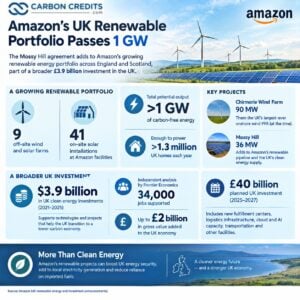
Amazon is expanding its renewable energy footprint in the UK as demand for low-carbon electricity grows across the economy. The company has now signed a new Power Purchase Agreement (PPA) with Statkraft for the 36-megawatt (MW) Mossy Hill wind farm near Lerwick in Scotland’s Shetland Islands. The project is expected to become operational in November 2030.

The deal adds to more than £3 billion (about US$3.9 billion) that Amazon says it invested in low-carbon technologies across the UK between 2021 and 2025. Its UK portfolio now spans more than 50 carbon-free energy projects with combined capacity of over 1 gigawatt (GW) once fully operational.

The investment comes as clean energy spending accelerates globally. The International Energy Agency (IEA) predicts global energy investment will hit $3.4 trillion by 2026. Of this, around $2.2 trillion will focus on clean energy technologies, grids, storage, nuclear, efficiency, and electrification.

Amazon’s UK Renewable Portfolio Passes 1 GW

The Mossy Hill agreement is Amazon’s latest addition to a rapidly growing UK portfolio.

The company has signed PPAs and developed renewable energy projects across England and Scotland. Its portfolio includes nine off-site wind and solar farms and 41 on-site solar installations at Amazon facilities. Once they start, the projects will produce over 1 GW of carbon-free energy. This is enough to power more than 1.3 million UK homes each year.

The earlier Chirmorie Wind Farm agreement in South Ayrshire was particularly significant. Its 90 MW project represented what Amazon described as the UK’s largest-ever onshore wind PPA at the time.

Mossy Hill adds another 36 MW to the pipeline. Together, these projects give Amazon a large, long-term position in Britain’s renewable power market while supporting new generation capacity for the wider grid.  

John Boumphrey, Amazon UK and Ireland Country Manager, said:

“Our latest project in the Shetland Islands builds on years of investment in renewable energy across the UK… Last year we announced our plan to invest £40bn (US$53bn) in the UK by 2027 and the transition to a lower-carbon economy is a part of how we’re putting that commitment to work.”

The $3.9 Billion Figure Covers More Than Wind Power

Amazon’s roughly $3.9 billion UK clean energy investment is broader than its renewable electricity portfolio. The company reports over £3 billion in low-carbon investments from 2021 to 2025. This funding supports technologies and projects that help the UK shift to a lower-carbon economy.

Frontier Economics conducted an independent analysis for Amazon. They estimate that the investment supported 34,000 jobs and added up to £2 billion in gross value to the UK economy.

Amazon has also committed to invest £40 billion in the UK between 2025 and 2027. That broader investment includes new fulfillment centers, logistics infrastructure, cloud and AI capacity, transportation and other facilities.

Amazon UK Renewable Portfolio Passes 1 GW

Clean energy is therefore one part of a much larger expansion. The company claims its renewable projects can boost UK energy security. They add to local electricity generation and cut reliance on imported fuels.

Why Amazon Is Locking In Long-Term Renewable Power

Amazon’s renewable strategy relies heavily on PPAs. Under these agreements, the e-commerce giant commits to buying electricity from a renewable project for a specified period.

Amazon clean energy capacity

Such contracts can provide developers with predictable revenue and help them secure financing for new projects. This model has allowed large corporations to become major sources of demand for new renewable capacity.

Amazon says it has helped projects reach deployment by acting as an anchor offtaker. Its UK portfolio therefore does more than match electricity consumption. It can also support the construction of new generation capacity.

The strategy is becoming more relevant as electricity demand rises. The IEA expects global electricity investment to hit nearly $1.6 trillion by 2026. With end-use electrification added, it could rise to around $2 trillion. Grid investment alone could approach $550 billion, up nearly 20% year over year.

Renewable projects backed by long-term corporate demand can therefore play a growing role in meeting future electricity needs.

Amazon Has Already Matched 100% of Its Electricity

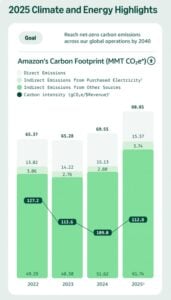
The renewable projects also support Amazon’s global climate strategy. Amazon reached its goal of using 100% renewable energy for its global operations in 2025. This is five years sooner than the original target of 2030. It achieved the same level for the third consecutive year.

Its carbon-free energy portfolio includes over 700 projects worldwide. This totals more than 42 GW of capacity in 30 countries, based on its 2025 sustainability report. 

The company co-founded The Climate Pledge in 2019 and remains committed to achieving net-zero carbon emissions across its global operations by 2040. However, matching electricity consumption with renewable energy does not mean Amazon’s overall emissions have already fallen.

Amazon’s 2025 sustainability report reveals that its absolute carbon emissions rose 16% from 2024. However, carbon intensity dropped 38% from the 2019 baseline. Revenue increased 156% over the same period. That distinction is important as Amazon continues to expand.

Amazon carbon emissions
Source: Amazon

AWS and AI Are Driving Amazon’s Power Needs

Amazon’s renewable energy strategy is also tied to the rapid expansion of AWS. It claims that AWS infrastructure added more data center capacity in 2025 than any other company worldwide. Data centers need a lot of reliable electricity to operate effectively.

At the same time, Amazon is working to improve energy efficiency. Its data centers recorded an average Power Usage Effectiveness (PUE) of 1.14 in 2025, compared with an industry average of 1.25 cited by the company. Amazon also says its data centers are seven times more water-efficient than the industry average.

Globally, data center electricity demand is becoming a major driver of power investment. This makes securing additional low-carbon electricity increasingly important for technology companies.

Amazon is also investing beyond wind and solar. Its broader energy strategy includes advanced nuclear, geothermal, and long-duration energy storage. The goal is to provide cleaner electricity while also improving the reliability of power supplies.

Renewable Power Has Not Yet Stopped Emissions Growth

Amazon’s renewable investments are significant, but the company’s overall decarbonization challenge remains large. Its business continues to expand across e-commerce, transportation, and cloud computing. 

The company’s 2025 sustainability report says it delivered 2.4 billion packages using electric vehicles during the year and operated more than 52,700 electric delivery vans globally. It is targeting 100,000 electric delivery vehicles by 2030.

  • Amazon also reduced carbon emissions per shipped unit by 7% in 2025.

However, its absolute emissions increased as its operations grew. The company needs ongoing investment in electricity, transportation, buildings, packaging, and its supply chain to hit its 2040 target. This is where renewable energy can have a larger role.

Amazon net zero emissions 2040
Source: Amazon

Amazon Is Turning Renewable Power Into Infrastructure Strategy

Amazon’s latest UK wind agreement shows how corporate renewable energy buying is moving beyond a simple sustainability initiative. The 36 MW Mossy Hill project adds to more than 50 UK carbon-free energy projects and takes Amazon’s planned UK portfolio beyond 1 GW of capacity.

At the same time, the global energy market is moving in the same direction. The IEA expects $2.2 trillion to flow into clean energy areas in 2026, nearly twice the investment expected for fossil fuels.

For Amazon, the UK strategy provides long-term access to carbon-free electricity while supporting new renewable capacity. The challenge now is to keep that growth aligned with emissions reductions. Amazon has already matched 100% of its global electricity consumption with renewable energy, but its absolute carbon footprint increased in 2025.

The company’s ongoing investment in wind, solar, electric transport, efficient data centers, and new clean energy technologies will be key. This will determine if it can achieve net-zero emissions by 2040.

The post Amazon’s $3.9B UK Clean Energy Bet Pushes Renewable Portfolio Past 1 GW appeared first on Carbon Credits.
Rio Tinto Pushes Steel Decarbonization with Carbon Capture Trial in China

Rio Tinto and Chinese steelmaker Shougang Group have commissioned an industrial-scale carbon capture trial facility designed to capture carbon dioxide directly from blast furnace gas at Shougang’s Jingtang steelmaking base in China.

The facility can process up to 3,000 cubic metres of blast furnace gas per hour and is designed to capture as much as 10,000 tonnes of CO₂ annually.

The project targets one of the hardest parts of steelmaking to decarbonize: existing blast furnace operations. Rather than replacing the blast furnace with a different production route, the technology captures CO₂ from gas generated during ironmaking and could potentially allow existing assets to continue operating with lower emissions.

The facility is part of a broader technology partnership between Rio Tinto and Shougang that began with a 2022 memorandum of understanding. The companies are working on low-carbon sintering, blast furnace and basic oxygen furnace optimization, and carbon capture and utilization technologies.

Steelmaking Remains a Major Source of Global Emissions

The project comes as the steel industry faces growing pressure to reduce its carbon footprint.

  • Steelmaking accounts for about 7% to 9% of global CO₂-equivalent emissions, according to a 2025 review published in Nature Reviews Clean Technology.

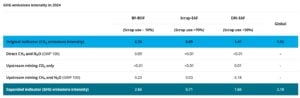
Around 70% of global steel production still uses the blast furnace-basic oxygen furnace (BF-BOF) route, which has an emissions intensity of about 2.32 tonnes of CO₂e per tonne of steel.

steel emissions
Source: World Steel

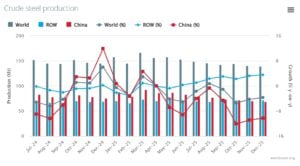
Global crude steel production reached about 1.85 billion tonnes in 2025. China remained by far the world’s largest producer, producing 960.8 million tonnes, or more than half of global output.

china steel making steel production
Source: World Steel Association

China’s steel industry is particularly important to global decarbonization efforts. Research published in 2026 estimates that China’s iron and steel sector accounts for roughly 15% of the country’s CO₂ emissions and more than 30% of its industrial emissions.

China’s total energy-related CO₂ emissions declined by around 0.5% in 2025, according to the International Energy Agency (IEA), with lower steel and cement production contributing to the decline. However, the scale of China’s steel industry means even incremental changes in emissions intensity can have a significant impact globally.

Shougang’s Steel Footprint

Shougang Group produced 30.23 million tonnes of crude steel in 2025, ranking it 12th among the world’s largest steelmakers, according to World Steel Association data. The company’s production declined from 31.57 million tonnes in 2024.

The company does not appear to publicly disclose a single consolidated current CO₂ footprint for the entire group that can be directly attributed to its 2025 steel production. However, the company has expanded its carbon accounting and product-level carbon footprint systems.

Shougang says Beijing Shougang and Shougang Jingtang have completed organization-level carbon emissions accounting and carbon footprint assessments for customer products. Both operations have also received carbon certification from SGS.

At Jingtang, the company has already been pursuing several measures to lower emissions from conventional steelmaking. Its blast furnace process has increased the share of pellet ore to more than 55%, which Shougang says has reduced CO₂ emissions by more than 167 kilograms per tonne of iron compared with the previous process.

Jingtang has also demonstrated steelmaking using more than 50% scrap in automotive steel production. Higher scrap use can reduce the need for carbon-intensive primary ironmaking.

Rio Tinto and Shougang Scale Up Carbon Capture

The new carbon capture facility follows a smaller-scale blast furnace carbon capture unit commissioned in 2024.

The companies are now testing the technology at a larger industrial scale and plan to operate the facility over the longer term for research and technology development.

Using waste heat from existing steelmaking operations could help reduce the energy requirements and costs associated with carbon capture. If costs can be lowered sufficiently, the approach could eventually be applied to other existing blast furnace facilities.

Rio Tinto Iron Ore Sales and Marketing Vice President Ramona Sim said:

“This milestone is an important step in our 30-year relationship with Shougang and our work together to find practical ways to reduce emissions from steelmaking.

“Steelmakers are exploring a range of technologies to lower emissions from existing blast furnace operations, and carbon capture and utilisation could play a key role as these technologies continue to develop.

“We’re committed to working with our customers to find better ways to use Pilbara ores in a lower-carbon future.”

A Partnership that Dates Back to 1996

The partnership between the two companies dates back to 1996, when Shougang received its first shipment of Rio Tinto iron ore from Australia’s Pilbara region. Three decades later, the relationship is increasingly focused on how that iron ore can be used in a lower-carbon steel industry.

Shougang Group Vice President Zhu Guosen said:

“Through this collaboration with Rio Tinto on carbon capture technology, Shougang has successfully developed and commissioned a 10,000-tonne-scale industrial trial facility.

“This achievement represents an important milestone for blast furnace decarbonisation and provides valuable demonstration value for reducing emissions in the conventional steelmaking route.

“The project has effectively addressed key challenges associated with carbon reduction in the blast furnace process and serves as an important example of our commitment to China’s dual-carbon goals and the advancement of low-carbon, green development.

“Looking ahead, we will continue to optimise the technology, advance the utilisation of captured carbon resources, and contribute to the green and low-carbon transformation of the steel industry.”

Captured CO₂ Could Be Reused in Steelmaking

The project is focused not only on capturing CO₂ but also on finding ways to use the captured carbon.

Rio Tinto and Shougang are exploring the conversion of captured CO₂ into syngas that could be recycled into the steelmaking process. Such an approach could reduce the amount of new carbon-based inputs required by steelmakers while creating a circular carbon pathway inside the plant.

That could become increasingly important as steelmakers look for ways to decarbonize existing BF-BOF assets without waiting for complete replacement with hydrogen-based direct reduced iron or electric arc furnace technologies.

The Broader Carbon Capture Market

Carbon capture is also becoming a larger commercial market.

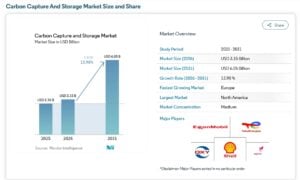
  • According to Mordor Intelligence, the CCS market size is expected to grow from USD 2.76 billion in 2025 to USD 3.15 billion in 2026 and is forecast to reach USD 6.05 billion by 2031 at 13.98% CAGR over 2026-2031.

carbon capture

Other market estimates vary significantly depending on whether they include transportation, utilization, and storage infrastructure.

The growth reflects rising demand for industrial carbon management, particularly in sectors such as steel, cement, chemicals and refining where process emissions can be difficult to eliminate through electrification alone.

Carbon Capture Targets Existing Steel Assets

The Rio Tinto-Shougang project highlights a broader debate over how quickly the global steel industry can move away from conventional blast furnace technology.

Hydrogen-based direct reduced iron and electric arc furnaces offer a potential pathway to much lower-emission steel, but replacing the world’s existing blast furnace fleet would require significant investment, new infrastructure and large amounts of low-carbon electricity or hydrogen.

Carbon capture offers another route by targeting emissions from facilities that are already operating.

The challenge will be cost. Capturing 10,000 tonnes of CO₂ annually at Jingtang is small compared with the emissions generated by a large integrated steel mill. But the trial could provide data on capture efficiency, energy use, operating costs, and the potential value of using captured CO₂.

For Rio Tinto, the project also extends its role beyond supplying iron ore into technologies that could lower emissions further down the steel value chain.

The post Rio Tinto Pushes Steel Decarbonization with Carbon Capture Trial in China appeared first on Carbon Credits.
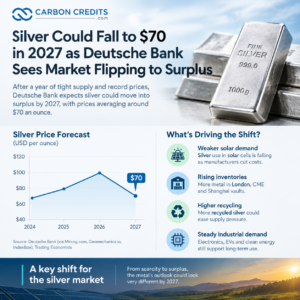
Deutsche Bank Sees Silver Prices at $70 an Ounce in 2027 as Market Shifts from Shortage to Surplus

Silver’s supply outlook is changing quickly.

After a physical shortage and a dramatic price rally in 2026, the silver market could enter surplus as early as 2027, Deutsche Bank says. Rising inventories, weaker industrial consumption and falling silver use in solar manufacturing are reducing pressure on the market.

The bank’s outlook, reported by Mining.com, points to a very different silver market from the one investors saw at the start of this year. Deutsche Bank metals analyst Daniel Ghali expects silver prices to average around $70 an ounce in the second quarter of 2027.

The forecast comes as silver prices retreat from their 2026 highs.

Silver Price Pulls Back From Record High

Silver has experienced an unusually volatile year.

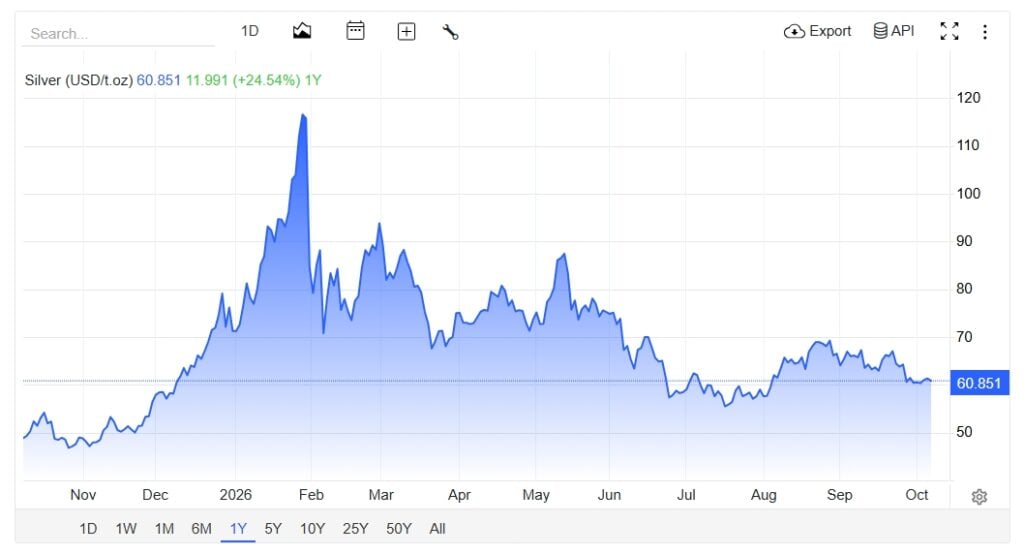
Trading Economics data show silver trading around $60.72 an ounce on October 7, down about 7.7% over the past month. However, the metal remains about 24% higher than a year ago. Silver reached an all-time high of $121.64 an ounce in January 2026.

silver

The decline reflects more than normal market volatility. Higher Treasury yields, a stronger U.S. dollar, and changing expectations for Federal Reserve policy have pressured precious metals.

But Deutsche Bank sees a more fundamental reason for potential weakness ahead: the silver market is becoming less physically constrained.

London commercial vaults held more than 914 million ounces of silver at the end of August, including more than 300 million ounces considered readily available. Deutsche Bank said readily available London stocks have increased about 70% since October 2025.

Inventories have also increased in CME warehouses and Shanghai. The bank attributes the buildup to higher recycling, the release of privately held metal, and weaker fabrication demand.

That growing inventory cushion could make another severe physical shortage less likely.

Solar Industry Becomes the Biggest Demand Risk

The biggest change could come from the solar industry.

Silver plays an important role in solar cells because of its high electrical conductivity. But manufacturers are under growing pressure to reduce the amount of silver used in each cell as prices rise.

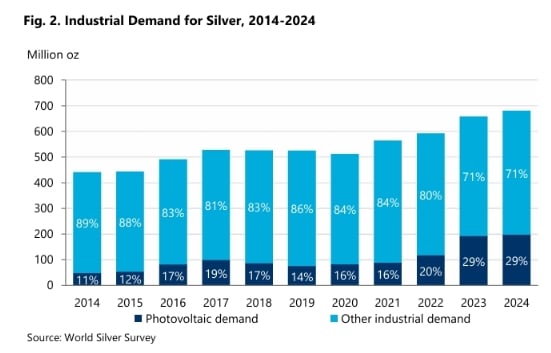
Deutsche Bank expects global silver consumption in solar applications to fall by more than 20% this year. Chinese solar demand could decline by about 33%.

Manufacturers are using thinner electrical contacts, copper-plated silver pastes and new cell designs that require less silver. The bank estimates silver use per solar cell will fall 17% in 2026.

High prices have strengthened that incentive.

silver demand

At one point in 2026, silver accounted for more than 30% of solar-module production costs, compared with less than 10% at the beginning of 2025. That share has since fallen to roughly 14%, but the cost remains high enough to encourage further material savings and substitution.

This creates an important paradox for the energy transition. Solar deployment can keep growing rapidly while the amount of silver required per panel falls.

Silver Demand Is Not Disappearing

A weaker solar market for silver does not mean industrial demand will collapse.

Silver remains widely used in electronics, electrical equipment, medical technologies and other industrial applications. Electrification, data infrastructure and renewable energy continue to support demand for the metal.

Recycling could also become a more important source of supply.

A recent Reuters analysis highlighted improvements in solar-panel recycling, including technologies capable of recovering silver at very high rates. Rystad Energy estimates that recycled panels could supply as much as 21% of the silver needed for solar-panel production by 2035.

That could further reduce the solar sector’s dependence on newly mined silver over time.

Investment Demand Could Decide Silver’s Next Move

With physical scarcity easing, investment demand may become even more important for prices.

Deutsche Bank estimates silver-backed investment funds could potentially release around 40 million ounces by the end of 2027 if investors respond to interest-rate conditions in a way similar to previous Federal Reserve tightening cycles.

India also presents a weaker demand signal. The bank estimates the country’s silver imports are about 25% below last year’s levels following higher import duties and purchasing restrictions. Chinese demand remains a wild card, however, because silver continues to trade at a premium in China despite rising inventories.

  • Trading Economics currently expects silver to average around $63.60 by the end of the quarter and reach about $74.56 over the next 12 months, showing that the broader market does not necessarily expect prices to collapse even as physical tightness eases.

The key difference is that silver may no longer need extreme scarcity to support its price.

What a Silver Surplus Means for the Energy Transition

A move from shortage to surplus would give manufacturers more breathing room, but it could also change the economics for silver miners.

If solar companies continue reducing silver intensity while recycling expands, future demand growth may not translate directly into higher primary silver consumption.

For investors, the story is therefore shifting from simply finding more silver to understanding where demand will come from.

Deutsche Bank’s forecast does not guarantee a surplus. Stronger Chinese demand, renewed investment buying, supply disruptions or another wave of precious-metals demand could quickly tighten the market again.

For now, however, the silver story is changing. A metal that started 2026 at the center of a supply squeeze could enter 2027 with rising inventories, more recycling and a solar industry determined to use less of it.

The next phase of the silver market may be less about scarcity and more about how quickly manufacturers can adapt.

The post Deutsche Bank Sees Silver Prices at $70 an Ounce in 2027 as Market Shifts from Shortage to Surplus appeared first on Carbon Credits.
Xpansiv Secures Major Growth Investment From Verdane to Expand Global Environmental Markets

Xpansiv Secures Major Growth Investment From Verdane to Expand Global Environmental Markets

Xpansiv has gained a significant investment from Verdane, a European firm. This funding will help the environmental markets infrastructure company expand by making acquisitions, developing new products, and growing internationally. The companies announced the strategic partnership on September 22, 2026. They did not disclose the size of the capital raise.

Xpansiv plans to use the new investment to strengthen its position across carbon credits, renewable energy certificates (RECs), clean fuels, and other environmental commodities. The company also wants to expand into new asset classes and geographic markets.

The deal comes as environmental markets become more complex. Companies are facing wider climate reporting rules, rising carbon prices, and stronger demand for clean energy certificates. For Xpansiv, that creates an opportunity to build the digital infrastructure behind these markets.

Xpansiv Is Building the Rails for Environmental Markets

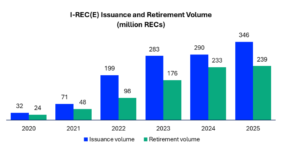
Xpansiv operates a mix of registries, marketplaces, trading services, data products, and portfolio-management systems. Its platform connects companies, utilities, and traders to carbon credits, RECs, clean fuels, and other environmental products. Verdane says Xpansiv processes about 1 billion transactions each year.

Its registry network now supports more than 320 gigawatts (GW) of renewable generation capacity across more than 60 countries. That represents about 4% of global electricity generation and 7% of renewable energy generation.

Xpansiv also says about 28% of RECs issued globally in 2025 were managed through its registry network. The scale is important because environmental markets depend on more than buyers and sellers.

They also need systems to register assets, issue certificates, verify ownership, track transfers, and record retirement. Xpansiv is trying to bring many of those functions onto one platform.

Xpansiv REC issuances and retirements volume
Source: Xpansiv 

Acquisitions Drive Xpansiv’s Expansion Strategy

Verdane’s investment will support Xpansiv’s merger and acquisition strategy, which has already become a major part of its growth model. Over the last four years, Xpansiv acquired:

  • APX, a provider of energy and environmental registry infrastructure;
  • Evolution Markets, a market execution and brokerage business; and
  • Evident, which operates the I-REC(E) renewable energy registry.

The strategy is continuing. In September 2026, Xpansiv agreed to acquire Formbay. This Australian platform makes and validates renewable energy certificates for rooftop solar and battery projects.

Formbay supports about 25% of Australia’s Small-scale Technology Certificate market. It creates nearly 100,000 certificates daily and helped with over A$1 billion in transactions in 2025. It also supports about 30,000 retailers and installers and is involved in one in three Australian home solar installations.

The Formbay deal is expected to be Xpansiv’s 13th acquisition since 2017. It remains subject to regulatory approval.

The new Verdane capital could give Xpansiv more room to continue making similar investments.

Carbon Is Just One Piece of the Environmental Markets Puzzle

Xpansiv’s growth strategy extends beyond carbon credits. The CBL exchange trades carbon credits, RECs, and other environmental commodities. Xpansiv Connect links various registries and marketplaces for easy portfolio management.

That broader approach could become increasingly important as companies manage several types of environmental assets at once. For example, a company may need carbon credits for climate targets, renewable energy certificates for electricity claims, and clean fuel credits for transport emissions.

Xpansiv is building infrastructure that can manage these products together. The company also provides market data and execution services through Evolution Markets, giving it a role beyond simply recording transactions.

That could help Xpansiv benefit from the wider growth of environmental markets rather than relying on one asset class.

Carbon Markets Are Attracting More Capital

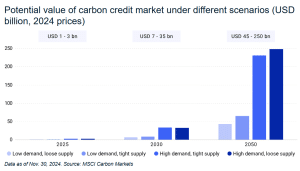
The timing of the investment is notable because capital flowing into carbon projects and future carbon supply has risen sharply. MSCI estimates that capital in the global carbon credit market hit $22 billion in 2025. This is a 72% increase from 2024 and over five times the amount from 2021.

Offtake agreements, where buyers commit to future carbon credit supply, reached $12.3 billion in 2025, nearly three times the previous year’s level.

Yet, the market remains small compared with long-term climate needs. MSCI estimates the primary global carbon credit market could grow from about $1.4 billion in 2025 to $5–20 billion by 2030 and $60–270 billion by 2050.

carbon credit market value 2050 MSCI

That potential growth creates demand for better market infrastructure. As transaction volumes grow, buyers require reliable data. Regulators and companies also need clear records of credit origins and usage.

RECs Add Another Fast-Growing Market

The opportunity extends into renewable energy markets. Xpansiv’s registry network supports over 320 GW of renewable energy. In July 2026, its I-REC registry hit a big milestone by recording its one billionth I-REC redemption.

The I-REC market has expanded tenfold since 2020. Now, over 80,000 organizations in more than 140 countries use I-RECs for buying renewable energy and supporting sustainability programs.

Xpansiv’s North American REC business is also expanding. The company said more than 3 million RECs were traded on its CBL exchange in 2024, up 18% year over year. In January 2025 alone, REC transaction value exceeded $27 million, a monthly record for the exchange.

Corporate clean energy targets, renewable portfolio standards, and rising demand for data centers are driving these markets. Electrification is also a key factor.

AI Could Help Scale Environmental Markets

Technology is another major part of the investment story. Xpansiv says its AI-enabled systems are being used to improve verification, auditability, and workflow management.

Formbay adds another example. Its platform uses AI to validate solar and battery installations and automate certificate creation. These tools can become more valuable as environmental markets grow.

Manual checks become harder when millions of certificates and transactions are involved. Automated data checks can reduce administrative work and help identify errors faster.

That does not remove the need for independent verification or market rules. Instead, digital systems can make those processes easier to manage at scale. For carbon markets, this could be especially useful as companies face growing demands for evidence behind climate claims.

Verdane Brings Climate and Technology Experience

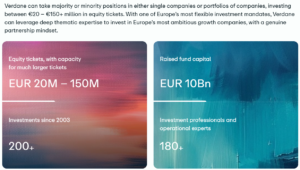
Verdane is a European growth investment firm focused on technology-enabled and sustainable companies. The firm says it has raised €10 billion in capital and made more than 200 investments since 2003. Its team includes more than 180 investment and operating professionals across Europe.

Verdane portfolio
Source: Verdane

Its investment in Xpansiv fits a broader strategy around companies involved in digitalization and decarbonization.

Verdane said Xpansiv’s market infrastructure could become more important as environmental reporting and compliance requirements widen. The investment also gives Verdane exposure to several markets at the same time, including carbon, renewable energy, and clean fuels.

For Xpansiv, this partnership means more capital and a growth investor. This investor knows how to scale tech platforms in Europe.

A Bigger Bet on Environmental Market Infrastructure

The new investment is important not because of its undisclosed size, but because of what Xpansiv plans to do with it. The company wants to keep buying businesses, enter new markets, and expand its technology platform. That strategy comes as environmental markets become more connected.

Carbon markets are expanding. Renewable energy certificates are becoming more widely used. Clean fuel and methane markets are developing. At the same time, governments are increasing reporting and compliance requirements.

All of these markets need trusted systems for registration, verification, trading, settlement, and data. Xpansiv is betting that one integrated platform can serve more of those needs. The latest Verdane investment provides more capital to continue that expansion.

As the market grows from a relatively small voluntary sector into a broader system linked to corporate reporting, renewable power, and climate regulation, the companies providing the digital rails could become as important as the developers creating the underlying carbon and clean energy assets.

The post Xpansiv Secures Major Growth Investment From Verdane to Expand Global Environmental Markets appeared first on Carbon Credits.
Carbon Credits Get More Expensive as Q3 Retirements Decline, Sylvera Finds

The voluntary carbon market (VCM) continued to move away from a volume-driven model in the third quarter of 2026, with carbon credit retirements falling even as buyers spent more on the credits they purchased.

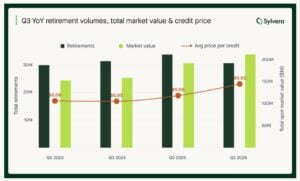
  • Carbon credit retirements reached 30.6 million in Q3 2026, down 9% from 33.7 million a year earlier, according to carbon market data provider Sylvera. However, the value of those retirements rose to $211.8 million from $190.6 million in Q3 2025.

The difference points to a market where buyers are becoming more selective. The report reveals that the average price paid for a retired credit climbed to $6.92 in Q3, compared with $5.66 a year earlier. For the first nine months of 2026, the average reached $6.12, up from $5.40 during the same period in 2025.

The trend also builds on what Sylvera identified earlier this year. In the first half of 2026, retirement volumes were down 9% year over year, while market value increased. By the end of Q3, however, cumulative retirements had edged above 2025 levels at 130.3 million credits, compared with 129.1 million through the first three quarters of last year.

Meanwhile, year-to-date retirement value reached $798 million, 14% above the $697.3 million recorded a year earlier.

carbon credit retirements

Quality Is Taking a Bigger Role in Carbon Credit Pricing

The strongest signal from the latest data comes from the widening gap between higher- and lower-quality credits.

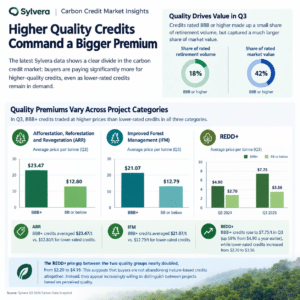
Credits rated BBB or higher represented only 18% of rated retirement volume in Q3. Yet they generated 42% of rated market value. This suggests buyers are willing to pay significantly more for credits that meet stronger quality expectations rather than simply purchasing the cheapest available supply.

The premium becomes even clearer across individual project categories.

  • For afforestation, reforestation and revegetation (ARR), BBB+ credits averaged $23.47 per tonne in Q3, compared with $12.80 for credits rated BB or below. Improved forest management (IFM) showed a similar divide. BBB+ IFM credits reached $21.07, while lower-rated credits averaged $12.79.
  • REDD+ also saw a sharp quality-driven price difference. BBB+ REDD+ credits averaged $7.75 in Q3, up 58% from $4.90 a year earlier. Lower-rated REDD+ credits increased from $2.70 to $3.56 over the same period.

As a result, the REDD+ price gap between the two quality groups nearly doubled from $2.20 to $4.19. The trend suggests that buyers are not abandoning nature-based credits altogether. Instead, they appear increasingly willing to distinguish between projects based on perceived quality.

carbon credits sylvera

Renewables Still Dominate, But Their Market Position Is Changing

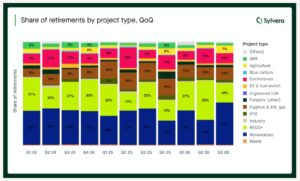
Renewable energy projects accounted for 41% of Q3 retirements, giving them the largest share among project categories. However, Sylvera cautions that the increase in market share does not represent renewed growth in renewable credit demand.

Renewable retirements totaled 40.7 million credits during the first nine months of 2026, roughly unchanged from the same period in 2025. That remains far below the 77.1 million credits retired during the first three quarters of 2022. Full-year renewable retirements peaked at 99.7 million in 2022 before falling to 49.3 million in 2025.

The quality issue is particularly important here. Sylvera does not rate renewable projects above C because many grid-connected renewable projects face additionality concerns. As a result, renewables accounted for 76% of B/C/D-rated retirement volume in Q3.

That helped push the share of B/C/D-rated credits across the entire retirement market to 66.1%, the highest level since Q3 2023. In other words, renewable credits continue to provide substantial market volume, but their presence also weighs on the overall quality profile of retirements.

REDD+ Demand Normalizes While Agriculture Gains Ground

REDD+ accounted for 18% of Q3 retirements, down sharply from 38% in Q2. However, the comparison needs context because Q2’s unusually high share was largely driven by one major retirement.

Beyond that temporary spike, REDD+ demand appears relatively stable, with retirement activity spread across Colombia, Brazil, Cambodia, Peru, and the Democratic Republic of Congo.

Agriculture was a more notable growth area. Its share of retirements increased from 2.55% to 7.82%, while retirement volume more than doubled. Energy and utility companies played an important role in that shift, with agriculture representing 28% of their Q3 retirement mix, compared with 6.8% a year earlier.

This diversification matters because the market is gradually moving beyond a small group of traditional project categories. Buyers are showing greater interest in credits tied to agriculture, forest management, and other project types where measurable climate and environmental benefits can support stronger pricing.

carbon credits renewables

Corporate Buyers Are Still Active

Despite the overall decline in quarterly retirement volumes, major corporate buyers continued to transact at scale.

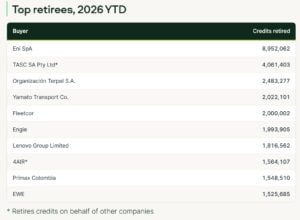
Yamato Transport and Corpay each retired about 2 million credits in Q3, making them the largest retirees during the quarter. Primax Colombia followed with just over 1 million.

For the first nine months of 2026, Eni remained the largest retiree with nearly 9 million credits. TASC, Organización Terpel, Engie and Lenovo also ranked among the largest buyers.

At the same time, Shell’s retreat remains significant. The company retired only about 496,000 credits through the first three quarters of 2026, compared with roughly 7 million during the same period in 2025. Sylvera first highlighted the decline in its Q2 report, and the latest numbers suggest the pullback has continued.

carbon credit retirement
Source: Sylvera

Q3 Reports Point to a More Selective Market

Sylvera’s findings broadly align with the quality-focused direction highlighted by other Q3 market research, although the datasets show different parts of the market.

CEEZER described Q3 as a cooler market, with weaker retirement activity and a sharper focus on credits carrying recognized quality labels.

  • Its analysis found that CCP-labeled retirement value increased 6.9% year over year even as the associated volume fell 17.7%. It also found that CCP-labeled issuances carried a roughly 48% premium over the broader market, up from about 5% a year earlier.

The difference between the reports is useful. Sylvera’s data shows that quality premiums are already visible across individual project types, while CEEZER’s analysis suggests that recognized integrity standards are becoming an increasingly important market filter.

Together, the findings point to a carbon market that is becoming less focused on buying the largest possible volume of credits. Instead, buyers appear more willing to pay for credits that can offer stronger ratings, clearer additionality, and greater confidence in environmental outcomes.

What Comes Next for the Carbon Market?

Sylvera’s Q3 data suggests that the voluntary carbon market is entering a more selective phase.

Retirement volumes remain uneven, and large corporate buying decisions can significantly influence quarterly results. Yet the rise in average prices and total market value shows that weaker volume does not necessarily mean weaker demand.

Instead, the market appears to be splitting between lower-cost credits that continue to provide significant volume and higher-quality credits that attract a growing share of spending.

That shift could have major implications for developers. Projects with stronger additionality, monitoring, and permanence claims may increasingly compete for a premium, while lower-quality supply could face greater difficulty attracting buyers.

For investors and corporate buyers, the message is similar: headline retirement volumes alone no longer tell the full story. The more important question may be how much capital is flowing toward credits that the market considers genuinely high quality.

Is the carbon market finally shifting from buying more credits to buying better ones?

The post Carbon Credits Get More Expensive as Q3 Retirements Decline, Sylvera Finds appeared first on Carbon Credits.

EU Carbon Price Jumps as CBAM Certificate Hits €82.32 per Tonne

EU Carbon Price Jumps as CBAM Certificate Hits €82.32 per Tonne

The European Union set the Q3 2026 price for Carbon Border Adjustment Mechanism (CBAM) certificates at €82.32 per tonne of CO₂. This provides importers with a new benchmark for the carbon cost of emissions-heavy goods entering the bloc.

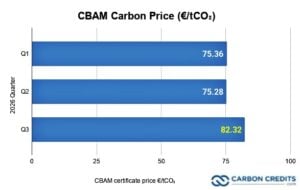
The European Commission published the price on October 5, after calculating it from EU Emissions Trading System (EU ETS) auction prices during the third quarter. It is the highest quarterly CBAM certificate price published so far in 2026. The price rose 9.4% from €75.28/tCO₂ in Q2 and about 9.2% from €75.36/tCO₂ in Q1.

The move comes as CBAM enters its first year of full operation. Importers now bear costs tied to the carbon emissions of their products. This makes the EU’s carbon price more important for global manufacturers and exporters.

CBAM Turns Carbon Reporting Into a Financial Cost

The CBAM definitive regime took effect on January 1, 2026, replacing the transitional system that operated from 2023 through 2025. The mechanism currently covers cement, iron and steel, aluminum, fertilizers, electricity and hydrogen.

Importers must report the emissions embedded in covered goods and eventually surrender the corresponding number of CBAM certificates. The system is designed to address carbon leakage.

Without CBAM, EU manufacturers covered by the EU ETS could face a carbon cost that foreign producers do not pay. This could encourage production to move outside the EU or allow more carbon-intensive imports to compete with European goods.

CBAM is intended to apply a comparable carbon cost to covered imports. The European Commission states that the mechanism aims to make sure imported products pay a carbon price similar to what EU producers pay. This also encourages cleaner production outside the EU.

An EU official recently said that starting in January 2026, CBAM will shift from reporting emissions to adding a financial cost to those emissions.

Q3 CBAM Price Climbs Nearly 10%

The new €82.32/tCO₂ price marks a clear increase during 2026. The Q3 price is important because it applies to CBAM-covered emissions from goods imported into the EU during that quarter.

CBAM Carbon Price q3 2026

However, importers do not begin buying certificates during 2026. The Commission says that approved CBAM declarants will start buying certificates in February 2027 for their imports from 2026.

The first CBAM declarations and corresponding certificate surrender are due by September 30, 2027. This gives companies time to calculate their embedded emissions, verify data, and prepare for the financial obligation.

How Much Could €82.32 Cost Importers?

The certificate price provides a straightforward way to estimate the potential carbon cost. For example, an importer with 10,000 tonnes of embedded emissions would face a gross certificate cost of approximately €823,200 at the Q3 2026 price.

At 100,000 tonnes, the figure rises to about €8.23 million.

The actual liability can be lower because CBAM allows importers to deduct a carbon price already paid in the country where the goods were produced. The final number of certificates also depends on the rules for calculating embedded emissions and the applicable free-allocation adjustment. That makes emissions data increasingly valuable.

The Commission has released guidance for specific sectors, including cement, hydrogen, fertilizers, iron and steel, aluminum, and electricity. It aims to help companies calculate embedded emissions during the set period.

For exporters, cleaner production can therefore become a competitive advantage. Lower embedded emissions mean fewer CBAM certificates are ultimately required.

Weekly CBAM Pricing Starts in 2027

The €82.32 price is also important because it represents the last phase of the EU’s temporary quarterly pricing system. For 2026, the Commission calculates four prices, one for each calendar quarter.

From 2027 onward, certificate prices will be calculated and published weekly. The methodology is designed to track the EU ETS more closely by using the relevant auction prices for EU ETS allowances. This means importers will face a more dynamic carbon price environment.                                         

The EU’s approach aims to keep the carbon cost for imports aligned with the carbon cost faced by European producers under the ETS. It also means companies will need to pay closer attention to carbon price movements when planning procurement, production and investment.

For businesses importing large quantities of emissions-intensive materials, carbon pricing could increasingly become part of ordinary supply chain cost management.

Top 10 Country of Production for CBAM

EU Could Expand CBAM’s Reach

CBAM is not necessarily staying limited to its current product categories. In June, the European Commission welcomed a Council agreement to extend CBAM to specific downstream goods and strengthen anti-circumvention measures.

The proposal aims to stop companies from sidestepping the rules. They can’t process covered materials into specific products outside the EU and then import them. This could expand the number of businesses exposed to the mechanism.

At the same time, the EU recently assessed its 50-tonne de minimis threshold. From April 2025 to March 2026, the Commission found that the threshold would exempt only 0.87% of embedded emissions. This is below the 1% limit set by the regulation.

The threshold was introduced to reduce the administrative burden on smaller importers. The Commission previously estimated that it would exempt about 182,000 importers while still covering more than 99% of emissions within CBAM’s scope.

The result is a system designed to reduce paperwork for small shipments without removing most emissions from the mechanism.

Carbon Pricing Is Expanding Beyond Europe

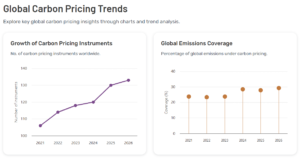
The CBAM price arrives as carbon pricing continues to expand globally. The World Bank’s State and Trends of Carbon Pricing 2026 report found that 87 carbon pricing policies were operating worldwide as of 2026.

Direct carbon pricing now covers over 29% of global greenhouse gas emissions. In 2025, carbon pricing systems generated over $107 billion in government revenue. The average direct carbon price reached nearly $21/tCO₂e.

carbon pricing trend world bank 2026
Source: World Bank
  • The EU’s €82.32 CBAM certificate price is therefore substantially above the global average direct carbon price.

However, the comparison is not like-for-like. The World Bank figure includes various carbon taxes and emissions trading systems. In contrast, CBAM is tied to the EU’s carbon market and targets embedded emissions in certain imports.

Still, the trend is clear: Carbon is increasingly becoming a direct economic cost in international trade.

EU Climate Policy Is Tightening the Long-Term Signal

CBAM is part of the EU’s broader climate strategy.

The bloc set a target in 2026 to cut net greenhouse gas emissions by 90% from 1990 levels by 2040. At least 85% of this reduction must happen within the EU, and up to 5% can come from international carbon credits. The bloc remains committed to achieving climate neutrality by 2050.
CBAM supports that trajectory by extending the carbon price signal beyond EU borders for covered products. The policy also interacts directly with the EU ETS, where European industrial producers already face carbon costs.

As the EU ETS gradually cuts free allocation for sectors under CBAM, the border mechanism will become more important. This gives manufacturers a stronger incentive to reduce emissions rather than simply absorb higher carbon costs.

The shift also creates stronger incentives for exporters to provide accurate, verified emissions data. Companies with lower actual emissions can potentially reduce their CBAM liability compared with producers relying on higher default values.

From 2027, the move to weekly certificate pricing will make the system even more closely tied to carbon market movements.

CBAM Is Becoming a Global Trade Signal

The European Commission’s €82.32/tCO₂ Q3 price marks another step in the transition from carbon reporting to carbon pricing at the border. The price is almost 10% above the Q2 benchmark.

The EU is also getting ready for weekly pricing starting in 2027, with the first certificate surrender deadline set for September 2027. At the same time, carbon pricing is spreading globally. The World Bank reports that direct carbon pricing now covers nearly 30% of global emissions.

For companies exporting emissions-intensive products to Europe, the implications are clear. Carbon emissions are no longer only an environmental metric. Under CBAM, they can directly affect the cost of accessing the EU market.

As the mechanism expands and the EU continues tightening its climate targets, the ability to measure, verify, and reduce embedded emissions is likely to become an increasingly important part of international industrial competitiveness.

The post EU Carbon Price Jumps as CBAM Certificate Hits €82.32 per Tonne appeared first on Carbon Credits.