Masdar Raises $600 Million in First Blue Bond to Fund Offshore Wind Projects

Masdar has raised US$600 million through its first blue bond to support eligible marine renewable energy projects, including offshore wind. The five-year bond is the fourth issuance under its US$6 billion Global Medium Term Note Programme. It also expands the company’s use of sustainable finance to support its global clean energy plans.

As per the press release, S&P Global Ratings and Fitch Ratings have both assigned the bond an AA- rating. According to the company, this makes it the highest-rated public blue bond issued by a corporate globally to date.

Issued on the London Stock Exchange’s International Securities Market, the bond carries a 5.875% US dollar coupon. The company then swapped the proceeds into euros at a yield of 4.374%, matching the funding with its European investment needs.

Investor demand remained strong despite difficult market conditions. The orderbook reached US$1.5 billion, making the final US$600 million issue 2.5 times oversubscribed. This means investors placed orders worth 2.5 times the amount offered.

Mazin Khan, Chief Financial Officer, Masdar, said:

“For two decades, Masdar has been a driving force in the development, deployment and commercialization of renewable energy solutions across the world. Our first blue bond issuance under our updated Green Finance Framework provides yet more opportunities for investors to join us in building the clean energy system of the future. This benchmark offering will ensure capital can be delivered where it will have the most impact, supporting the development of a more resilient blue and green economy.”

What Are Blue Bonds?

Blue bonds are debt instruments that raise money for projects linked to the protection and sustainable use of oceans and water resources. They work much like green bonds but focus on marine and water-related environmental goals.

Companies and governments can use them to fund ocean conservation, wastewater treatment, sustainable marine infrastructure, and eligible offshore wind projects.

Investors buy these bonds and receive interest payments under agreed terms. The issuer must direct the money toward eligible projects and report how it uses the funds.

However, a blue bond label alone does not guarantee environmental benefits. Clear project rules, regular reporting, and checks on possible harm to marine life help maintain investor trust.

For the renewable energy developer, this financing route creates another way to fund offshore wind and other eligible projects while supporting the sustainable use of marine resources.

Masdar Updated Green Finance Framework Adds Blue Projects

In September 2026, the company updated its Green Finance Framework to include eligible blue projects. The framework sets the rules for selecting projects, allocating funds, and reporting their environmental impact.

Under the updated rules, green financing instruments can fund eligible green and blue projects. Blue financing instruments form a separate category, with all proceeds reserved exclusively for eligible blue projects.

The framework follows the Green Bond Principles of the International Capital Market Association (ICMA). It also considers the International Finance Corporation’s (IFC) blue finance guidelines and the 2023 guide to financing the sustainable blue economy, published by several international organizations.

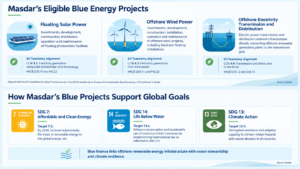
                                 Eligible Blue Projects

masdar blue energy
Source: Masdar

Moody’s Gives Its Highest Sustainability Score

Moody’s assigned the framework an SQS1, or Excellent, Sustainability Quality Score. This is the highest score available under its sustainability assessment system.

The framework also requires environmental checks to identify and reduce potential harm to biodiversity. Where feasible, eligible projects must align with relevant European Union Taxonomy criteria for climate change mitigation.

These safeguards matter for offshore wind developments. While offshore wind generates electricity without burning fossil fuels, construction and operation can affect marine habitats and wildlife. Careful planning and environmental checks can help reduce these risks.

Bond Funding Supports Renewable Energy Growth

The latest issuance brings the total raised through the company’s bond programme to US$3.35 billion since 2023. Before this deal, it had raised US$2.75 billion through the programme.

By the end of 2025, US$2.3 billion had been allocated to 30 renewable energy projects across 10 countries. These projects had a combined gross capacity of more than 16 gigawatts (GW).

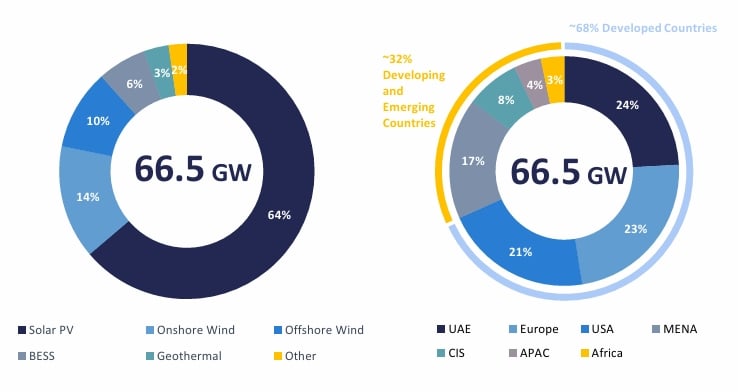
The company now reports more than 65 GW of renewable energy capacity across global markets. Its portfolio includes solar power, onshore and offshore wind, battery storage, and hybrid energy systems.

It aims to increase this capacity to 100 GW by 2030. Reaching that target will require further investment in project development, construction, and supporting infrastructure.

masdar renewable energy
Source: Masdar

The blue bond adds another source of capital for this expansion. It also links fundraising with specific environmental goals and may attract investors seeking opportunities in sustainable finance.

What Does the Blue Bond Mean for Investors?

The deal shows how sustainable finance is expanding beyond traditional green bonds. Blue bonds give investors another way to support environmental projects, with a focus on oceans and water resources.

Strong demand for the issuance points to investor interest in this type of financing. The AA- ratings from S&P and Fitch also reflect the agencies’ assessment of the issuer’s credit quality. However, credit ratings do not guarantee returns or eliminate investment risks.

The bond’s environmental value will depend on how the company uses the proceeds and how it measures results. Investors will need to review project selection, biodiversity safeguards, and impact reports to assess whether the funded activities meet their stated goals.

As the company works toward its 2030 capacity target, blue financing could help fund eligible offshore wind and other marine-related renewable energy projects. The deal also shows how specialised bonds can link corporate funding plans to measurable environmental objectives.

The post Masdar Raises $600 Million in First Blue Bond to Fund Offshore Wind Projects appeared first on Carbon Credits.

COP31 Sponsor Koç Holding Cuts Climate Targets as Oil Profits Rise

COP31 Sponsor Koç Holding Cuts Climate Targets as Oil Profits Rise

A major Turkish business group sponsoring the upcoming UN climate summit has weakened its emissions targets while its oil-refining business benefits from a global supply crunch and rising profits.

Koç Holding, one of Türkiye’s largest industrial groups, is the Global Business Partner of COP31, which will take place in Antalya from November 9 to 20, 2026. Its energy subsidiary, Tüpraş, operates the country’s largest oil-refining business.

An investigation by Climate Home News found that Koç Holding and Tüpraş lowered their 2030 emissions reduction targets in 2025. The change came as Tüpraş planned to keep its refineries running at high capacity and prepare for higher production in 2026.

The findings raise questions about the role of major fossil fuel-linked companies at climate summits. They also highlight the challenge of judging corporate climate plans when companies continue to depend on oil while investing in lower-carbon energy.

Koç Holding and Tüpraş did not respond to multiple requests for comment from Climate Home News. The UN climate secretariat and the COP31 presidency also declined to answer questions about the sponsorship agreement.

COP31 Sponsorship Raises Questions About Climate Integrity

Koç Holding was named COP31’s Global Business Partner in August 2026. The COP31 presidency said the group would share its experience in turning climate commitments into practical business action.

The partnership gives Koç a prominent role at a summit designed to advance global climate action. But the company’s oil business has brought its climate record under fresh scrutiny.

The hosting agreement between Türkiye and the UN Framework Convention on Climate Change (UNFCCC) says the government should seek advice from the UN climate secretariat when assessing potential partners. The agreement also says that a partner’s “climate integrity” should be considered.

However, the process for applying this test remains unclear. The Turkish presidency has not published its sponsor-selection criteria or the financial terms of its partnership agreements.

Campaigners say companies with major fossil fuel businesses should face stronger checks before receiving prominent roles at climate conferences. They argue that sponsorship can give companies visibility and access to policymakers, even when their business plans remain tied to oil and gas.

The issue is not limited to COP31. Previous climate summits have also accepted sponsorship from companies linked to fossil fuels, prompting calls for clearer rules on corporate participation.

Koç Holding and Tüpraş Lowered Their Emissions Targets

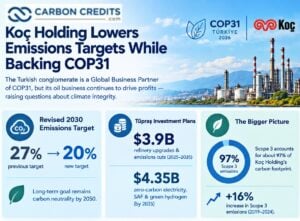
Koç Holding and Tüpraş both announced lower interim emissions reduction targets in 2025. The companies had previously aimed to cut emissions from their own operations by 27% by 2030, compared with 2017 levels. They reduced that target to 20%.

Tüpraş also lowered its 2035 target from a 35% reduction to 25%. Both companies have retained their long-term ambition to reach carbon neutrality by 2050.

Koç Holding’s carbon neutrality by 2050 target
Source: Koç Holding Sustainability Report 2025

The companies said changing market conditions, economic pressures and technology developments had affected their plans. Koç Holding also pointed to the slower-than-expected development of green hydrogen, which had been an important part of its earlier transition strategy.

The revised 2030 targets are closer to the progress the companies had already made. By 2025, Koç Holding had cut emissions from its own operations by about 16% from 2017 levels, while Tüpraş had reduced them by around 17%.

This means the companies have less ground to cover to meet their updated interim goals. However, lower targets do not automatically mean emissions will rise. Actual results will depend on future operations, investments, and emissions reporting.

Oil Refining Remains Central to the Business

Tüpraş is the main source of income for Koç Holding’s energy division. It operates four refineries that turn crude oil into petrol, diesel, jet fuel, and other products.

In 2025, Tüpraş processed 28.1 million tonnes of crude oil and other materials and produced 26.8 million tonnes of products. Its refineries operated at 93% of capacity.

The company planned to raise production to 29 million tonnes in 2026. It has said it intends to maintain existing refinery capacity and run its facilities at maximum potential.

Tüpraş has also benefited from strong refining margins. These margins—the difference between the cost of crude oil and the value of refined products—rose as the global oil-processing market faced supply pressures linked to the Middle East crisis.

The strong oil business sits alongside the group’s stated climate ambitions. Koç Holding and Tüpraş have pledged to reach carbon neutrality by 2050, but oil refining is expected to remain an important source of earnings for years to come.

The issue is not simply that Tüpraş continues to operate refineries. The key question is whether its investments and emissions plans will lead to a meaningful shift away from fossil fuels over time.

Most of the Group’s Emissions Come From Sold Fuels

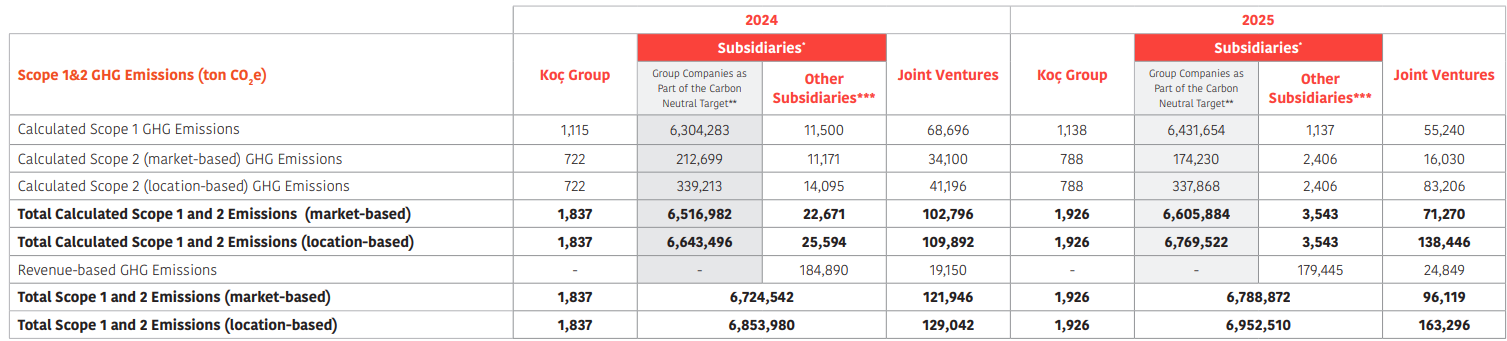
A major gap in the revised targets is their limited coverage of the group’s overall climate impact. The targets focus on emissions from the companies’ own operations and purchased energy. These are known as Scope 1 and Scope 2 emissions.

But much of the climate impact comes from products sold to customers. When petrol, diesel and jet fuel are burned in cars, trucks and aircraft, they release greenhouse gases. These emissions are known as Scope 3.

Climate Home News reported that Scope 3 emissions accounted for about 97% of Koç Holding’s carbon footprint. These emissions rose by roughly one-sixth between 2019 and 2024, and neither Koç Holding nor Tüpraş has set a target to reduce them.

Koç Holding’s carbon footprint ghg emissions 2025

This distinction matters when assessing a company’s climate progress. A refinery can cut the energy it uses and improve its own efficiency while continuing to sell large volumes of fossil fuels. Without a clear plan to address emissions from sold products, cuts at factories and refineries may cover only a small part of the company’s total climate impact.

Green Investment Plans Face Delays and Cost Pressures

Koç Holding and Tüpraş are also investing in lower-carbon energy. Their plans include renewable electricity, sustainable aviation fuel (SAF) and green hydrogen.

Tüpraş plans to invest $3.9 billion between 2025 and 2035 in refinery improvements and measures to reduce emissions from its operations. Its wider plan calls for $4.35 billion in investment in zero-carbon electricity, sustainable aviation fuel and green hydrogen by 2035.

The company also aims to expand its installed zero-carbon electricity capacity to 1.6 gigawatts by 2030 and 2.5 GW by 2035. Its renewable energy portfolio includes solar and wind projects, while additional developments remain in the pipeline.

However, some projects have been delayed or scaled back.

Tüpraş originally planned to begin producing green hydrogen in 2025. It now expects to launch a pilot project by 2030, with large-scale commercial production not expected before 2035. The company has cited higher costs for electrolyzers, which use electricity to split water into hydrogen and oxygen.

Its SAF plans have also changed. Instead of converting an existing refinery unit by 2026, Tüpraş now plans to build a separate plant expected to begin operating toward the end of 2028. That change means the new fuel production would be added to existing refining capacity rather than replacing it.

The projects could support the transition to lower-carbon energy. But delays and high costs show how difficult it can be to turn long-term climate plans into operating businesses.

Koç Holding Climate Accountability Infographic

COP31 Puts Corporate Climate Claims Under the Spotlight

The Koç Holding case highlights a wider challenge for COP31: how to bring businesses into climate action while ensuring their claims match their investment decisions and emissions results.

Corporate partnerships can help fund new technology and expand clean energy projects. But a sponsor’s role at a climate summit also carries reputational value, making the selection process important.

For Koç Holding and Tüpraş, the main test will be whether their planned investments lead to substantial and lasting changes in their businesses. Progress will depend on more than emissions cuts at refineries. It will also depend on how the group addresses emissions from the fuels it sells and whether its low-carbon projects move forward.

COP31’s approach to sponsor screening may also shape future debates over the role of companies with large fossil fuel interests at UN climate conferences.

As world leaders prepare to meet in Antalya, the question is not only what companies promise to do. It is whether their targets, spending, and business plans show a credible path toward lower emissions.

The post COP31 Sponsor Koç Holding Cuts Climate Targets as Oil Profits Rise appeared first on Carbon Credits.

EIB Unveils €30 Billion Climate Plan to Protect Europe From Extreme Weather

EIB Unveils €30 Billion Climate Plan to Protect Europe From Extreme Weather

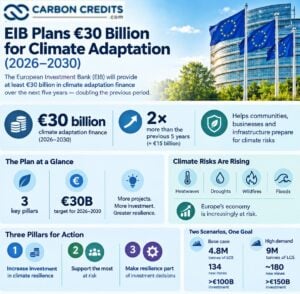
The European Investment Bank (EIB) Group plans to provide at least €30 billion in climate adaptation finance from 2026 to 2030. This doubles the amount it provided over the previous five years. The funding will help communities, businesses and infrastructure prepare for climate risks such as heatwaves, droughts, wildfires and floods.

The bank announced the new target, along with its Climate Adaptation Plan Phase 2. The plan explains how the EIB Group will turn climate risks into investment projects across Europe and in vulnerable countries outside the European Union (EU).

The commitment builds on about €15 billion in adaptation finance provided during the previous five-year period. However, the new €30 billion figure is a funding target for 2026–2030. It is not money that has already been spent. The plan also does not say that the full amount has already been set aside for specific projects.

The strategy marks a change in the bank’s approach. The EIB Group is shifting its focus. Instead of just raising awareness of climate risks, it now wants to prepare more projects. The goal is to attract both public and private investment, and it aims to make climate adaptation easier to fund.

Climate Risks Put Pressure on Europe’s Economy

Climate adaptation means taking steps to prepare for climate change and reduce the harm it causes. These steps can include stronger flood defenses, better water management, buildings designed to handle heat, and farming methods that use less water.

The EIB Group says climate resilience is becoming vital to Europe’s economic security. Extreme weather can damage roads, power networks and public buildings. It can also disrupt businesses, reduce farm output and put pressure on food and water supplies.

The bank’s plan notes that Europe is warming faster than any other continent. Economic losses from extreme weather have also risen sharply in recent decades. Heat contributes to tens of thousands of premature deaths each year.

Investing in adaptation can also reduce the cost of future climate damage. According to the EIB’s announcement, research suggests that every euro invested in climate prevention and adaptation can bring up to €10 in benefits to people and the economy. The actual results will depend on the type of project and the risks it addresses. 

EIB Group President Nadia Calviño remarked:

“Climate adaptation is a no-brainer. Every euro invested in prevention and adaptation to climate change saves 10 euros in damages and repairs.”

However, adaptation investment remains below what is needed. Many projects face funding gaps, a lack of technical skills, and limited financial incentives. Smaller businesses and local authorities may understand their climate risks but lack the resources to develop projects that lenders are willing to finance.

The EIB Group wants to address these problems by combining loans and other funding with expert advice, guarantees, and tools that help share investment risks.

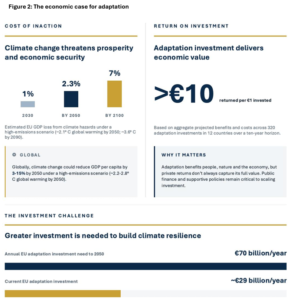
Eu climate adaptation investment case
Source: EIB

Three Pillars Guide the €30 Billion Plan

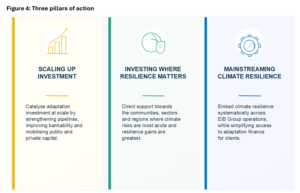
The plan has three main pillars. They aim to increase investment, direct support to those most at risk from climate change, and make climate resilience a normal part of investment decisions.

1. Increase investment in climate resilience

The first pillar focuses on developing more projects that can attract funding.

The EIB Group plans to support measures such as early-warning systems, flood protection and the protection and restoration of natural areas. It will also support stronger water, energy, transport and communication networks. These investments can help keep essential services running during extreme weather.

The bank will provide advice to help clients assess climate risks, prepare projects and plan their funding. Programmes such as the Climate Adaptation Investment Advisory Platform (ADAPT), Green Gateway and JASPERS will help turn climate needs into projects that are ready for investment.

The EIB Group will also use blended finance. This means combining different types of funding, such as public grants and loans, to help projects attract more investment. Guarantees and other tools that share risks can also make projects more appealing to investors.

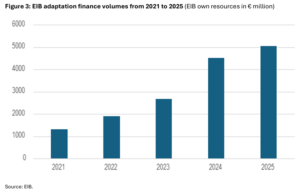
The bank plans to support green bonds that help fund climate adaptation. It will also back financing tools that improve disaster preparation and recovery. Between 2020 and 2025, the bank deployed around €15 billion for adaptation projects, as annual lending nearly quadrupled.

EIB adaptation finance volumes from 2021 to 2025
Source: EIB

2. Direct funding to the areas most at risk

The second pillar focuses on vulnerable communities, small and medium-sized businesses, farmers, cities and regions. It also covers countries outside the EU that face serious climate risks.

In Europe, the bank plans to support projects that address heat, drought, wildfires, floods and other climate threats. These could include cooler public buildings, greener city spaces, better systems for managing rainwater and stronger flood protection.

Small businesses and farmers are another priority. Many do not have enough money, skills or insurance to prepare for climate impacts. The EIB Group plans to work with financial institutions to improve their access to loans, expert advice and tools that help manage risk.

Projects could include water-saving irrigation, monitoring technology, backup power systems, cooling equipment and production methods that can better withstand extreme weather.

The plan also highlights nature-based solutions. Restoring wetlands, forests and floodplains can help manage water, reduce flood risks and protect ecosystems. These measures can work alongside traditional infrastructure, although the best option will depend on local conditions.

Outside the EU, the EIB Group plans to increase support for vulnerable partner countries, especially Small Island Developing States and Least Developed Countries. EIB Global, in partnership with the European Commission, helps countries develop projects. These projects focus on water management, coastal protection, early-warning systems, stronger transport networks, and disaster planning.

EIB Climate Adaptation Investment Plan

3. Make climate resilience part of investment decisions

The third pillar aims to include climate resilience more often in the EIB Group’s investment decisions. It also seeks to make adaptation funding easier for clients to access.

The bank will improve its climate risk checks and the tools available to clients and financial partners. It also plans to reduce reporting work while keeping clear and reliable standards for identifying and measuring adaptation projects.

One key initiative is ClimateSET, a free digital tool being developed with the Copernicus Climate Change Service. It will help users find climate information for specific locations, identify risks and weaknesses, and explore ways to prepare for climate impacts.

The EIB plans to add ClimateSET to its Green Checker tool, which helps financial partners check whether investments meet relevant climate standards. Together, the tools should help businesses and other borrowers understand their risks and prepare suitable projects.

The bank also wants to improve how it measures the results of adaptation projects. This includes checking whether investments reduce risks and prevent losses. Better measurement should help the EIB Group understand which measures work and guide future investment decisions.

EIB THREE PILLARS OF ACTION
Source: EIB

New Financing Could Support Climate Adaptation Technology

The EIB Group’s plan aims to help European companies develop climate adaptation technologies, including cooling systems, water-saving solutions and stronger energy infrastructure. Through its TechEU platform, the bank will connect innovators with funding, guarantees and expert advice to bring these solutions to market.

The plan supports the bank’s Climate Bank Roadmap Phase 2 for 2026–2030, which aligns with the Paris Agreement and the EU’s climate goals. Separately, the EIB and European Investment Fund approved €11.8 billion in new financing, including €5.5 billion to strengthen Europe’s energy independence and reduce power costs. This is a separate decision and should not be counted toward the €30 billion adaptation target without confirmation.

The plan also supports global efforts to increase adaptation finance. At COP30 in 2025, countries adopted the Belém Political Package, which included a commitment to triple adaptation finance by 2035.

However, more funding alone will not guarantee results. Projects must be prepared to attract investment and deliver clear benefits. The EIB Group plans to combine finance with expert advice, better climate data and partnerships to help overcome these barriers. It also stresses that adaptation must go hand in hand with cutting greenhouse gas emissions.

Over the next five years, the success of the €30 billion target will depend on how quickly projects are developed, how much additional funding is mobilized, and whether support reaches the communities and infrastructure most exposed to climate risks.

The post EIB Unveils €30 Billion Climate Plan to Protect Europe From Extreme Weather appeared first on Carbon Credits.

Mexico Produces One-Fifth of the World’s Silver: Why the Country Still Matters to the Next Supply Cycle

Disseminated on behalf of Sierra Madre Gold & Silver Ltd.

Mexico remains the world’s largest silver-producing country, but its output declined in 2025. As global silver supply struggles to expand, the country’s mature mining districts, existing infrastructure, and pipeline of established assets could become increasingly important to the next supply cycle. Sierra Madre Gold & Silver is developing two such assets through La Guitarra and Del Toro.

Mexico occupies a unique position in the global silver market. The country produced 172.9 million ounces of silver in 2025, according to the World Silver Survey 2026, accounting for roughly one-fifth of global mine production.

However, Mexico’s dominance does not mean its silver output is continually increasing. Production fell 5% from 181.1 million ounces in 2024, even as global silver mine production increased 3% to 846.6 million ounces.

That contrast matters.

Mexico is the largest source of mined silver in the world. Yet, it’s getting harder to keep or boost production as mature mines decline and the global market faces deficits.

For the silver market, the question is therefore not simply how much silver Mexico produces today. It is whether the country can continue supplying significant volumes as existing operations mature.

Sierra Madre Gold & Silver offers a case study in one potential response. The company operates the La Guitarra complex in Temascaltepec, State of Mexico, and is advancing the restart of the Del Toro complex in Zacatecas.

Both are established mining assets with existing infrastructure and production histories.

Mexico Remains the World’s Silver Leader

Mexico has held the top position in global silver production for years. Its 2025 output of 172.9 million ounces represented approximately 20% of global mine production.

Peru ranked second, followed by China, Poland, and Bolivia, according to the Silver Institute and Metals Focus.
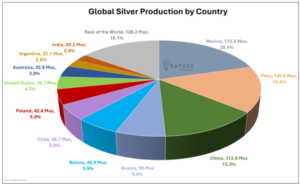
global silver production

The scale is significant. In 2025, Mexico made more silver than many countries did in their whole mining sectors. This makes its output a key factor in the global supply.

Yet, the 5% year-over-year decline also illustrates the challenge facing mature silver jurisdictions.

Being the largest producer does not guarantee production growth.

Mining assets age. Ore grades can change. Underground development becomes more complex. Processing plants require investment. Permits and infrastructure must be maintained.

At the same time, new deposits take years to move from discovery to production. This creates a potential role for established mining districts and brownfield assets.

The Next Supply Cycle May Depend on Existing Districts

A large part of Mexico’s silver production comes from mining districts with decades or even centuries of operating history.

That creates an unusual advantage. Established districts can have roads, power systems, water infrastructure, processing facilities, underground workings, and experienced mining workforces already in place.

Those assets do not eliminate development costs or operating risks. But they can change the starting point for companies seeking to restart or expand production.

This is particularly relevant in a market where global mine supply is not responding quickly enough to close persistent deficits.

The World Silver Survey 2026 recorded a 40.3-million-ounce deficit in 2025, the fifth consecutive annual deficit. Metals Focus expects another 46.3-million-ounce deficit in 2026.
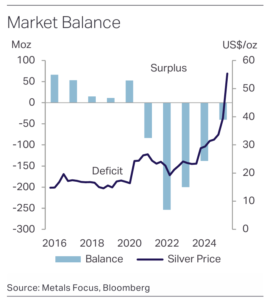
silver market deficit

If global supply needs additional ounces, bringing established assets back online could form part of the response.

Mexico has a large inventory of those assets.

La Guitarra Sits Inside Mexico’s Historic Silver Belt

Sierra Madre’s La Guitarra complex provides one example. Located near Temascaltepec in the State of Mexico, La Guitarra is part of a historic silver-producing district.

Sierra Madre acquired the operation from First Majestic Silver and restarted commercial production on January 1, 2025. The operation already had a processing plant and established underground workings, allowing Sierra Madre to restart production without developing an entirely new mine and mill.

The company has since been expanding the operation.

The original processing configuration was approximately 500 tonnes per day. Sierra Madre is now targeting 750–800 tpd in its first expansion phase and 1,200–1,500 tpd by Q3 2027 in the second phase.

In September 2026, the company reported steady throughput of up to 720 tpd as development advanced at the Guitarra and Nazareno mines. This progression shows how an established Mexican asset can become a source of incremental supply.

Instead of starting with a discovery and building an entirely new mine, Sierra Madre started with a past-producing operation and is investing to increase its capacity.

Del Toro Adds a Second Mexican District

Sierra Madre’s Mexican strategy extends beyond La Guitarra. In June 2026, the company completed the acquisition of the Del Toro Silver Mine in Zacatecas from First Majestic. 
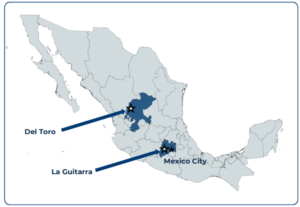
Del Toro

Zacatecas is one of Mexico’s most important historic silver-producing regions and has been a major contributor to the country’s position in global silver mining.

Del Toro itself operated from 2013 through 2019 under First Majestic. The property includes three underground mines, San Juan, Perseverancia and Dolores, together with more than 62.5 kilometers of existing underground development.

The complex also contains a 3,000-tonnes-per-day flotation facility, as well as other processing and infrastructure assets. This infrastructure provides Sierra Madre with a solid base to assess future production.

The company plans to restart Del Toro at approximately 800 tpd, with potential to increase throughput to 1,600 tpd.

Sierra Madre currently targets the restart process for mid-2027 and first production for mid-2028. These are company targets and depend on the completion of technical, development and operational work.

Zacatecas Shows Why Existing Infrastructure Matters

Del Toro’s history also demonstrates the depth of Mexico’s established mining infrastructure.

First Majestic invested approximately US$175 million to develop the operation, according to Sierra Madre’s acquisition materials. The mine subsequently produced an average of approximately 2.54 million silver-equivalent ounces per year between 2015 and 2018.

Sierra Madre is not simply attempting to restart historical production at the same scale.

The company is doing more exploration and resource work. They are also looking at the best way to restart operations.

The property has a large exploration database and Sierra Madre found several mineralized zones for further study. That gives the asset two potential roles.

  • First, it can provide a platform for restarting production.
  • Second, exploration could potentially extend the mine’s future resource base.

Any future resource estimate, however, will need to be established through updated technical work. Historical estimates and past production figures should not be treated as current mineral resources or guarantees of future production.

Mexico’s Importance Goes Beyond Two Mines

Sierra Madre’s assets are only two examples within a much larger Mexican mining industry.

The country has extensive experience in underground mining, processing and silver production. It also has established mining districts, transportation networks, power infrastructure, and skilled labor.

That ecosystem matters when the global silver market needs additional production.

New greenfield mines will remain necessary over the long term, but the timeline from discovery to commercial production can be lengthy.

Brownfield expansions and restarts can potentially provide another route. The distinction is becoming more important because silver supply remains structurally constrained.

About three-quarters of silver produced worldwide comes from other metals. This means that higher silver prices can’t quickly boost primary silver production.

Mexico’s established silver assets therefore represent more than historical production. They form part of the existing physical infrastructure that can potentially be expanded, modernized or restarted.

A Mature Producer Still Has Room to Grow

Mexico’s 5% production decline in 2025 is a reminder that being the world’s largest silver producer does not make supply growth automatic. The country needs continued investment to maintain production from existing mines while developing the next generation of deposits. 
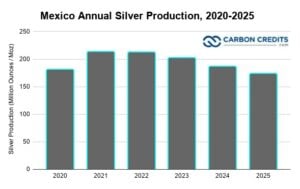
Mexico Annual Silver Production, 2020-2025

That creates a balancing act.

Existing operations need additional exploration and capital to replace depleted reserves and maintain output. At the same time, past-producing assets can offer opportunities to add production without starting from an undeveloped site.

Sierra Madre’s strategy reflects both sides.

  • At La Guitarra, the company is expanding a restarted operation and increasing processing capacity.
  • Del Toro is considering restarting a former production site. They are also doing more exploration and technical work.

The two assets are at different stages. However, both show how established Mexican mining infrastructure is being revived or expanded.

The Next Mexican Silver Ounces May Already Have Infrastructure Behind Them

Mexico’s position in the silver market is unlikely to depend on a single new discovery. The country’s importance comes from the depth of its mining industry and the scale of its existing production base.

Its 172.9 million ounces of silver production in 2025 demonstrate the country’s enormous contribution to global supply. But the 5% decline from 2024 also shows why maintaining that position will require continued investment.

That is where established assets can become relevant.

La Guitarra is already producing and being expanded. Del Toro has a production history, extensive underground development, and a substantial processing facility.

Neither project guarantees future production, and both require continued capital and execution. But they illustrate a broader point about the next silver supply cycle.

When global mine production is struggling to grow, the industry’s response may not come only from newly discovered deposits.

Some of the next ounces could come from old mining districts, existing mills, past-producing mines, and brownfield expansions.

Mexico has more of that infrastructure than almost any other silver-producing country. And as the global silver market searches for additional supply, that existing foundation could make the country an important part of the next production cycle.

DISCLAIMER
New Era Publishing Inc. and/or CarbonCredits.com (“We” or “Us”) are not securities dealers or brokers, investment advisers, or financial advisers, and you should not rely on the information herein as investment advice. Sierra Madre Gold and Silver Ltd. (“Company”) made a one-time payment of $25,000 to provide marketing services for a term of one month. None of the owners, members, directors, or employees of New Era Publishing Inc. and/or CarbonCredits.com currently hold, or have any beneficial ownership in, any shares, stocks, or options of the companies mentioned.

This article is informational only and is solely for use by prospective investors in determining whether to seek additional information. It does not constitute an offer to sell or a solicitation of an offer to buy any securities. Examples that we provide of share price increases pertaining to a particular issuer from one referenced date to another represent arbitrarily chosen time periods and are no indication whatsoever of future stock prices for that issuer and are of no predictive value.

Our stock profiles are intended to highlight certain companies for your further investigation; they are not stock recommendations or an offer or sale of the referenced securities. The securities issued by the companies we profile should be considered high-risk; if you do invest despite these warnings, you may lose your entire investment. Please do your own research before investing, including reviewing the companies’ SEDAR+ and SEC filings, press releases, and risk disclosures.

It is our policy that information contained in this profile was provided by the company, extracted from SEDAR+ and SEC filings, company websites, and other publicly available sources. We believe the sources and information are accurate and reliable, but we cannot guarantee them.

CAUTIONARY STATEMENT AND FORWARD-LOOKING INFORMATION

Certain statements contained in this news release may constitute “forward-looking information” within the meaning of applicable securities laws. Forward-looking information generally can be identified by words such as “anticipate,” “expect,” “estimate,” “forecast,” “plan,” and similar expressions suggesting future outcomes or events. Forward-looking information is based on current expectations of management; however, it is subject to known and unknown risks, uncertainties, and other factors that may cause actual results to differ materially from those anticipated.

These factors include, without limitation, statements relating to the Company’s exploration and development plans, the potential of its mineral projects, financing activities, regulatory approvals, market conditions, and future objectives. Forward-looking information involves numerous risks and uncertainties and actual results might differ materially from results suggested in any forward-looking information. These risks and uncertainties include, among other things, market volatility, the state of financial markets for the Company’s securities, fluctuations in commodity prices, operational challenges, and changes in business plans.

Forward-looking information is based on several key expectations and assumptions, including, without limitation, that the Company will continue with its stated business objectives and will be able to raise additional capital as required. Although management of the Company has attempted to identify important factors that could cause actual results to differ materially, there may be other factors that cause results not to be as anticipated, estimated, or intended.

There can be no assurance that such forward-looking information will prove to be accurate, as actual results and future events could differ materially. Accordingly, readers should not place undue reliance on forward-looking information. Additional information about risks and uncertainties is contained in the Company’s management’s discussion and analysis and annual information form for the year ended December 31, 2025, copies of which are available on SEDAR+ at www.sedarplus.ca.

The forward-looking information contained herein is expressly qualified in its entirety by this cautionary statement. Forward-looking information reflects management’s current beliefs and is based on information currently available to the Company. The forward-looking information is made as of the date of this news release, and the Company assumes no obligation to update or revise such information to reflect new events or circumstances except as may be required by applicable law.

For more information on the Company, investors should review the Company’s continuous disclosure filings available on SEDAR+ at www.sedarplus.ca.

Disclosure: Owners, members, directors, and employees of carboncredits.com have/may have stock or option positions in any of the companies mentioned: None.

Carboncredits.com receives compensation for this publication and has a business relationship with any company whose stock(s) is/are mentioned in this article.

Additional disclosure: This communication serves the sole purpose of adding value to the research process and is for information only. Please do your own due diligence. Every investment in securities mentioned in publications of carboncredits.com involves risks that could lead to a total loss of the invested capital.

Please read our Full RISKS and DISCLOSURE here.

The post Mexico Produces One-Fifth of the World’s Silver: Why the Country Still Matters to the Next Supply Cycle appeared first on Carbon Credits.
BlackRock-Backed Akaysha Energy Secures A$1.75 Billion Financing for Australia’s Battery Storage Growth

Australian battery storage developer Akaysha Energy has secured an A$1.75 billion (approximately US$1.22 billion) portfolio financing facility to refinance debt linked to four battery energy storage system (BESS) projects. Founded in 2021, the company develops, owns and operates large-scale batteries designed to support electricity grids as renewable generation increases.

Significantly, BlackRock’s Climate Infrastructure business acquired Akaysha in 2022, marking its first battery storage investment in the Asia-Pacific region.

The press release says eleven banks supported the financing, including ANZ, BNP Paribas, Bank of China, CIBC, Commonwealth Bank of Australia, Deutsche Bank, DNB, ING, Mizuho, MUFG and Rabobank. The deal brings existing project loans under a single financing structure and gives the company greater flexibility to develop additional storage assets.

Akaysha Consolidates Debt Across Four Battery Projects

The agreement comes as Australia expands battery storage to support renewable energy, improve grid reliability and manage fluctuations in electricity supply. For investors, the deal highlights how portfolio-level financing can help developers manage capital requirements as battery projects grow in scale.

The new facility refinances debt associated with four Australian projects: Brendale and Ulinda Park in Queensland, Orana in New South Wales, and Elaine in Victoria. Three assets are operational, while Elaine remains under construction and is expected to be completed in the second half of 2027.

The financing includes three facilities with terms of five, seven and ten years. It also provides revolving liquidity and contingent instrument facilities, giving Akaysha additional flexibility to manage funding needs as its projects advance.

Andrew Wegman, Managing Director and Chief Financial & Investment Officer of Akaysha Energy, said:

“This is an important milestone for Akaysha and it was pleasing to see continued strong support from lenders for our operating portfolio, our pipeline and Australia’s energy transition. As well as refinancing our existing operating and construction assets, this portfolio-level facility gives us the flexibility to accelerate our next wave of projects while we continue deploying capital where we see the strongest opportunities across the pipeline. We’re grateful to our fantastic bank group, our advisors and of course the broader Akaysha team, all of whom worked tirelessly to get this done.”

The transaction creates a common financing platform for operating and construction-stage assets. Rather than managing separate project-level loans, Akaysha can use the consolidated structure to support portfolio growth and allocate capital across development opportunities.

Australia’s Battery Storage Market Is Expanding

Australia’s battery storage industry is attracting investment as the country adds renewable generation and prepares for the retirement of ageing coal-fired power stations.

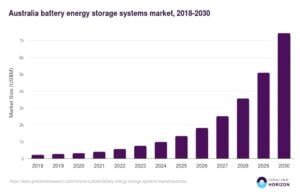
The Australian BESS market generated an estimated US$988.9 million in revenue in 2024, according to Grand View Research. Its market outlook projects revenue of US$7.42 billion by 2030, representing a compound annual growth rate of 41.1% from 2025 to 2030. These figures are commercial market estimates, rather than a measure of installed battery capacity.

Australia battery storage

Utility-Scale Battery Additions

Deployment is also accelerating. The Clean Energy Council reported that nine utility-scale battery projects, representing 2.3 gigawatts (GW) of power capacity and 7.1 gigawatt-hours (GWh) of storage, began operating in the first half of 2026. For comparison, Australia added 2 GW and 5.1 GWh during the whole of 2025.

australia clean energy battery storage
Source: CEC

The first half of 2026 delivered more new storage capacity than the whole of 2025.

This shows that the market is moving beyond pilot projects toward larger, commercially operated assets. Batteries can store surplus electricity when supply is high and release it when demand rises. They can also provide fast grid services that help maintain stable electricity supply.

How Much Battery Capacity Will Australia Need?

The Australian Energy Market Operator (AEMO) published its 2026 Integrated System Plan in June, outlining the investment needed to maintain a reliable electricity system as coal generation declines and electricity consumption grows. The plan identifies renewable generation supported by storage and transmission as a cost-effective route to a lower-emissions grid.

energy transition Australia

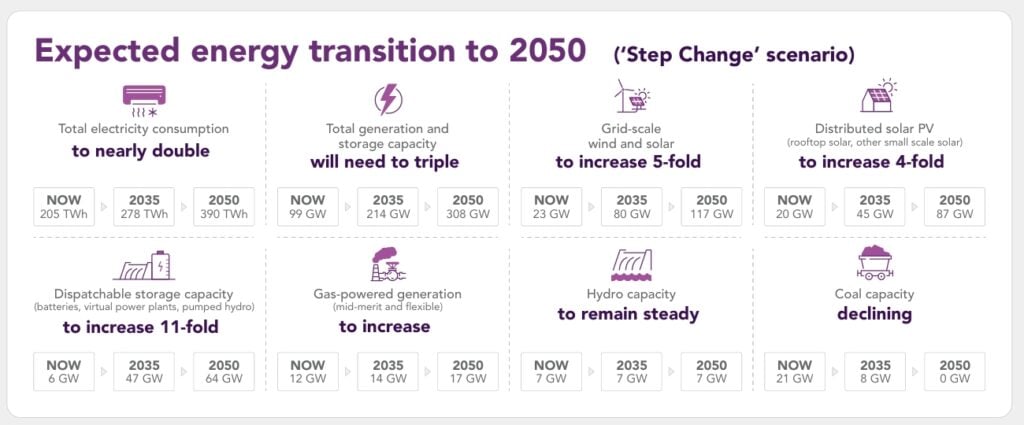
Under the plan’s development pathway, the National Electricity Market (NEM) is expected to need approximately 27 GW of total storage capacity by 2030. This includes different storage durations and technologies. Longer-term requirements extend to around 33 GW of utility-scale storage by 2050, including 27 GW of grid-scale batteries and 6 GW of pumped hydro.

These are planning requirements, not guaranteed installation targets. Actual deployment will depend on project economics, grid connections, electricity market conditions, permitting, and financing.

Household batteries are expanding too. The Clean Energy Council reported that 276,011 home batteries were installed in the first half of 2026, bringing the number of Australian homes and small businesses with battery systems to more than 700,000. This distributed storage can complement large grid-scale facilities by storing rooftop solar power for use later in the day.

Akaysha’s Pipeline Offers Further Growth Potential

Akaysha’s financing supports a reported Australian development pipeline of approximately 6 GW of power capacity and 25 GWh of storage across the NEM. This pipeline gives the company opportunities to expand as demand for flexible electricity supply increases.

The company has also advanced the Waratah Super Battery in New South Wales, which reached final commercial operations in September 2026. The project has a power capacity of 850 megawatts (MW) and storage capacity of 1,680 megawatt-hours (MWh), making it a major source of grid support.

Waratah Super Battery in New South Wales

For investors, the refinancing is significant because it combines debt across several projects and provides a structure that can accommodate further development. However, the facility is primarily a refinancing transaction, not entirely new construction capital. Future growth will still depend on project delivery, operating performance, electricity market revenues and access to additional funding.

White & Case, RBC Capital Markets, and Chatham advised Akaysha Energy. Allens acted for the lenders, while several technical, financial, insurance and other advisers supported the due diligence process.

Australia’s growing storage requirements create a substantial opportunity for battery developers. Akaysha’s ability to turn its pipeline into operating assets will determine how effectively it can use this financing platform to capture that opportunity.

The post BlackRock-Backed Akaysha Energy Secures A$1.75 Billion Financing for Australia’s Battery Storage Growth appeared first on Carbon Credits.
Carbon Credit Economics: The Real Cost of Delivering High-Integrity Credits

The cost of producing a carbon credit varies widely by project type, financing needs, and operating conditions. A new report from carbon credit ratings provider Sylvera, developed in collaboration with the Integrity Council for the Voluntary Carbon Market (ICVCM), examines these costs across different carbon project categories.

The report draws on 53 responses from project developers working across afforestation, reforestation and revegetation (ARR), biochar, REDD+, cookstoves, regenerative agriculture and mangroves. It examines capital expenditure, operating costs, financing assumptions, additional revenue streams and community benefit-sharing.

The findings show that producing high-integrity credits can require very different levels of investment. They also highlight how financing costs and limited transparency can affect project economics, particularly for nature-based solutions and community-led projects.

Biochar Has the Highest Carbon Credit Production Costs

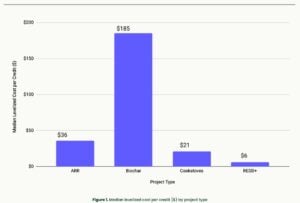
The report found a significant gap in the median cost of delivering a carbon credit across the project types with sufficient data for detailed analysis.

Biochar had the highest median levelized cost at $185 per credit, followed by ARR at $36. Cookstove projects recorded a median of $21, while REDD+ projects had the lowest median at $6.

biochar
Source: Sylvera

These differences reflect how each project operates. Biochar projects often require specialized equipment, processing facilities, and significant upfront investment. Their economics can also depend on access to suitable biomass, reliable operations, and demand for the biochar product.

ARR projects face a different challenge. Developers must invest in land preparation, planting, and project establishment before forests generate substantial volumes of credits. REDD+ projects, by contrast, focus on protecting existing forests, making their cost structure less dependent on establishing new tree cover.

However, the figures are benchmarks rather than universal production costs. The report’s sample is limited, and the $6 REDD+ median should be treated as directional rather than a definitive industry-wide estimate.

Upfront Investment and Operating Costs Shape Project Economics

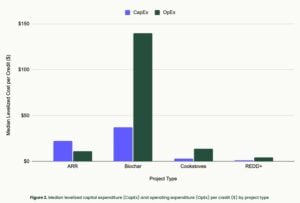
Carbon credit production costs depend on both the money developers spend to establish projects and the expenses they incur to keep them running. Capital expenditure (CapEx) includes early investments, while operating expenditure (OpEx) covers activities such as monitoring, verification, and project management.

  • ARR stands out because 71% of its median levelized cost comes from upfront investment. Developers must finance land preparation and planting before they can generate meaningful credit volumes.
  • Biochar, REDD+, and cookstove projects have a lower median CapEx share, leaving a greater proportion of their costs associated with ongoing operations.

This difference also affects how projects respond to financing conditions. Developers that need substantial upfront capital face greater exposure to interest rates, investor return expectations, and country-specific risks.

high costs carbon credits
Source: Sylvera

Higher Financing Costs Can Make Carbon Credits More Expensive

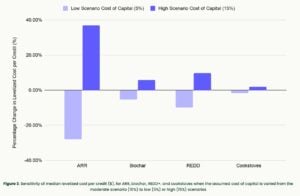
Sylvera tested how changing the assumed cost of capital affects the levelized cost of credits. Its central scenario uses a 10% discount rate, with alternative scenarios at 5% and 15%.

ARR costs rise by nearly 37% when the assumed discount rate increases from 10% to 15%. The increase is much smaller for the other project types.

The report links this difference to ARR’s capital-intensive structure and longer investment horizon. Higher financing costs can make projects less attractive to investors and limit the amount of capital available for development.

Community-led and Indigenous-led projects may face additional barriers because they often operate in markets with higher perceived risks and have less access to institutional finance. Blended finance, concessional loans and investment guarantees could help reduce these barriers, although access remains uneven.

Project Scale Can Reduce Costs, but Other Factors Matter

The report also identifies a relationship between project size and production costs. Across biochar, ARR, REDD+, and cookstove projects, higher annual credit volumes generally correspond to lower costs per credit.

For biochar, the highest-cost project in the sample produces fewer than 500 credits annually and has a levelized cost of about $544 per credit. Lower-cost projects, with costs ranging from approximately $25 to $140 per credit, cluster around annual volumes of 2,300 credits or more.

Larger operations may spread equipment, staffing, and other fixed expenses across more credits. However, scale alone does not determine costs. Technology, location, access to feedstock, and local market conditions also influence project economics. Sylvera cautions that its limited sample cannot establish a statistically reliable relationship between project size and unit costs.

project costs carbon credits
Source: Sylvera

Community Benefit-Sharing Needs Greater Transparency

Carbon projects can support local communities through direct payments, employment, infrastructure, training, and other services. However, Sylvera found that reported benefit-sharing arrangements vary widely, partly because developers use different definitions and reporting methods.

The reported range does not necessarily show how much cash communities receive. Some projects count direct payments, while others include employment, infrastructure, or in-kind support. This makes it difficult for buyers to compare projects or determine whether communities receive a fair share of the economic benefits.

The report recommends clearer disclosure of benefit-sharing arrangements, including the type of benefit, its recipient, payment schedule, and governance. It also proposes considering a minimum direct monetary benefit share of 30% to 35% of gross carbon revenue for projects on community-titled land. This is a recommendation for future standards, not an existing universal requirement.

Conclusion

Sylvera and ICVCM’s findings show why carbon credit buyers need more than a quoted price to assess a project. Production costs vary with technology, financing, scale, and community commitments. Better cost disclosure could help buyers compare projects, developers justify prices, and investors identify financing gaps.

Standardized reporting on community benefits would also improve accountability and help direct funding toward credible, high-integrity carbon projects.

The post Carbon Credit Economics: The Real Cost of Delivering High-Integrity Credits appeared first on Carbon Credits.
NextEra Energy Secures $5.7B for Federal Gas Hubs Serving AI Demand

NextEra Energy Secures $5.7B for Federal Gas Hubs Serving AI Demand

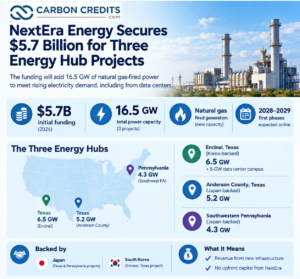
NextEra Energy has secured $5.7 billion in initial funding for three federally backed energy hub projects in Texas and Pennsylvania. The projects will add large amounts of natural gas-fired power to meet rising electricity demand, including demand from data centers.

The company announced the funding during its third-quarter 2026 earnings call on October 21. The three projects are expected to provide about 16.5 gigawatts (GW) of power capacity, according to NextEra. The company has signed definitive agreements to develop, build, and operate the hubs, with the first phases expected to begin serving customers as early as 2028 and 2029.

The deals also offer NextEra a way to earn revenue from new power infrastructure without investing its own capital in the projects. But they raise wider questions about how the United States will meet fast-growing electricity demand while managing emissions from fossil fuels.

Three Energy Hubs Will Add New Natural Gas Capacity

Two of the projects are planned for Texas and Pennsylvania. They are backed by the Government of Japan and the U.S. Department of Commerce as part of a wider U.S.-Japan investment effort.

The U.S. government announced the two natural gas projects in March 2026. Its fact sheet put their estimated costs at up to $16 billion for the Texas project and $17 billion for the Pennsylvania project. NextEra Energy Resources is the operator for both facilities.

The Texas project is planned for Anderson County and could provide up to 5.2 GW of natural gas-fired generation. The Pennsylvania project, planned for the southwestern part of the state, is expected to provide 4.3 GW. Both projects are designed to serve large electricity users, including data centers.

The third hub is backed by the Republic of Korea and the U.S. Department of Commerce. It is planned for Encinal, Texas, and will include about 6.5 GW of natural gas generation to serve a planned 5-GW data center campus. The first phase could begin operating in 2029.

NextEra said the three hubs have secured $5.7 billion in initial funding so far in 2026. An initial $3.3 billion funding release in August will support the purchase of turbines and other equipment that can take years to deliver.

The funding supports early project development and equipment procurement. It should not be confused with the full construction costs of all three hubs.

NextEra Will Earn Project Fees Without Investing Its Own Capital

The projects use a different business model from power plants that NextEra owns and operates with its own money. Under the agreements, NextEra Energy Resources will develop, build, and operate the hubs for fees. The company expects to receive fees during development and construction, as well as during the first 20 years of operations.

NextEra says it will not need to invest its own capital in these three projects. Even so, the hubs are expected to provide about 50% of the adjusted earnings per share that the company would expect if it owned the power assets itself.

This approach could allow NextEra to earn long-term income while limiting the amount of its own money tied up in construction. It also gives the company a role in building new power capacity as electricity demand grows.

The model does not remove all project risks. The hubs still need to move through construction, secure required permits and approvals, and bring their power supply online on schedule. NextEra is also working on power purchase arrangements for the projects while construction planning moves forward.

The company expects electricity supply to increase in stages. It aims to serve some demand as early as 2028 and 2029, then expand supply to meet the full needs of the campuses between 2030 and 2032.

AI Data Centers Drive Demand for New Electricity Supply

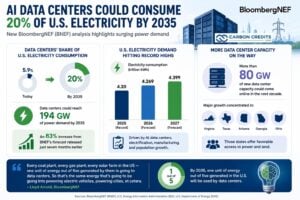
The projects reflect a wider change in the U.S. electricity market. Data centers, especially those used for artificial intelligence (AI), need large amounts of power to run computing equipment and cooling systems. Their demand can also grow quickly as companies expand their digital services.

US AI electricity consumption 2030 BNEF

Building new power generation close to large electricity users can help developers bring supply online faster. The approach may also reduce pressure on existing grids if the projects provide dedicated generation and infrastructure for new customers.

NextEra says the hubs are designed to match new electricity demand with new power generation. Its view is that data centers should pay for the generation and infrastructure they require, rather than shifting those costs to existing utility customers.

However, the impact on other electricity users will depend on how each project is financed, connected to the grid, and operated. New power plants alone do not guarantee lower bills. Fuel prices, construction costs, transmission limits, and the rules for sharing grid costs will also matter.

The projects are part of NextEra’s wider effort to serve large electricity users. During the third quarter, NextEra Energy Resources added 3.7 GW to its development backlog, including 2.4 GW of battery storage. Its total backlog reached about 36.7 GW.

The company is also discussing a pipeline of 30 to 40 potential energy hub projects. That is a development pipeline, not a set of approved projects or a guarantee that all will be built.

Natural Gas Adds Power But Raises Climate and Emissions Questions

Natural gas can provide electricity when customers need it, including during periods when wind and solar output is low. That flexibility can help data centers and other large users that need a steady power supply.

However, gas-fired power plants also produce carbon dioxide when they burn fuel. Natural gas supply chains can release methane, a powerful greenhouse gas, during production and transport. The total climate impact depends on plant efficiency, how often the plants operate, and methane leakage across the supply chain.

The three hubs are designed mainly around natural gas generation, rather than renewable energy. Their planned capacity could help meet new electricity demand, but it could also add to long-term fossil fuel use if the plants operate for decades.

The company has pointed to the potential to add battery storage alongside the hubs. Batteries can store electricity and release it when needed, helping balance supply and demand. However, storage does not generate electricity on its own. Its climate benefits depend in part on the source of the power used to charge it.

The projects therefore highlight a key challenge for the U.S. power sector: meeting the rapid growth in electricity demand while keeping emissions in check. The result will depend on how much the gas plants operate, whether additional clean energy is built, and how the wider electricity system changes over time.

NextEra Energy’s Three Power Hubs

Federal Energy Hubs Reflect a Wider Push to Meet AI Power Demand

The three projects are part of a broader effort to build energy infrastructure around large industrial and technology users. The U.S. government has promoted energy hubs as a way to expand domestic power supply, support economic activity, and meet demand from data centers.

NextEra is also involved in a separate project in western Kentucky. There, the company is part of a coalition planning a data center campus with up to 2 GW of natural gas generation and up to 2.6 GW of battery storage. That project is distinct from the three hubs tied to the $5.7 billion in initial funding.

For NextEra, the new agreements create a path to earn fees from large power projects without providing the construction capital itself. For the U.S. energy market, they show how quickly data center demand is shaping investment decisions

The post NextEra Energy Secures $5.7B for Federal Gas Hubs Serving AI Demand appeared first on Carbon Credits.
Lithium Needs $100 Billion and 134 New Mines to Meet 2050 Demand and Power the EV Boom

Lithium Needs $100 Billion and 134 New Mines to Meet 2050 Demand and Power the EV Boom

The world may need the equivalent of 134 new lithium mines by 2050 to meet rising demand for electric vehicles (EVs) and battery storage. The projects could require more than $100 billion in investment, before counting the contribution of recycled lithium, according to Benchmark Mineral Intelligence.

The forecast highlights a major challenge for the energy transition. Lithium demand is expected to grow sharply over the next 24 years, but mining companies must secure funding, permits and buyers before they can bring new projects into production.

Benchmark’s base-case forecast puts global lithium demand at about 7 million tonnes of lithium carbonate equivalent (LCE) in 2050, up from 2.11 million tonnes in 2026. However, the amount of new mining needed will depend on future demand, recycling rates, technology, and how quickly projects can be developed.

Lithium Demand Could More Than Triple by 2050

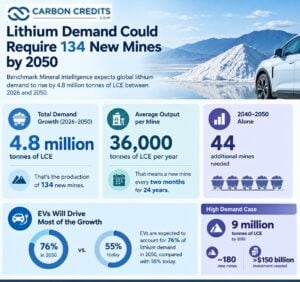
Benchmark expects global lithium demand to increase by about 4.8 million tonnes of LCE between 2026 and 2050. At an average output of 36,000 tonnes of LCE per mine each year, that growth would equal the production of 134 new mines.

In practical terms, the industry would need to bring a mine of that average size online roughly every two months for the next 24 years. Demand growth between 2040 and 2050 alone would require the equivalent of 44 additional mines.

Electric vehicles are expected to drive most of this growth. Benchmark forecasts that EVs will account for 76% of lithium demand in 2050, compared with 55% today.

Battery storage will also contribute as power grids add more renewable energy. Lithium-ion batteries help store electricity from solar and wind projects and supply it when generation falls or demand rises.

The International Energy Agency (IEA) reported that lithium demand rose by 25% in 2025, driven by electric vehicles (EVs), stationary battery storage, and clean energy technologies. These forecasts do not guarantee a particular level of demand. EV sales, government policies, battery technology and economic conditions will all affect how much lithium the market needs.

More Than $100 Billion Must Flow Into New Mines

Meeting the base-case demand forecast will require more than $100 billion in investment for new lithium mining capacity, Benchmark estimates. Its higher-demand scenario raises the challenge further:

  • Demand could approach 9 million tonnes of LCE by 2050, requiring the equivalent of around 180 mines and well over $150 billion.

The figures show why securing capital is as important as finding lithium deposits. A mineral resource does not become a producing mine overnight. Developers must complete studies, arrange financing, obtain permits, build processing facilities and connect projects to transport and power infrastructure.

Lithium Demand 134 New Mines by 2050 benchmark mineral intelligence

Projects can also face delays from technical problems, environmental reviews and community concerns. These risks can increase costs and push production further into the future.

Benchmark lithium product director Cameron Perks identified another hurdle: keeping investors committed when lithium prices fall. He stated:

“Meeting 2050 demand requires the equivalent of 134 new lithium mines, more than US$100 billion of investment before any contribution from recycling, rising to more than 180 mines in our upside scenario. The biggest challenge is sustaining that investment through price cycles, while competing for capital with AI, defence and the wider energy transition.”

The investment estimate is a forecast, not a record of money already committed. It also depends on Benchmark’s assumptions about average mine size, demand, and future supply. Actual spending could vary by project and region.

Lithium Prices Show Why Funding Can Be Difficult

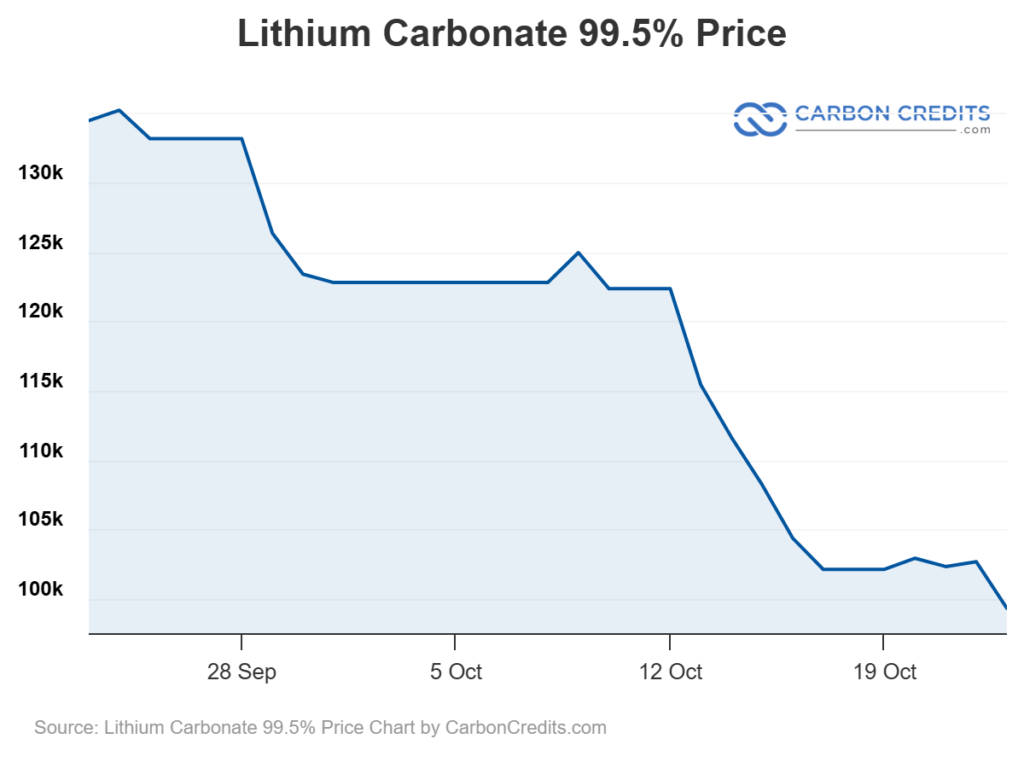
The lithium market has already experienced sharp price swings. Benchmark data cited by Investing News Network show that battery-grade lithium carbonate ended the third quarter of 2026 at $19,025 per tonne, down 20.8% from the previous quarter. Spodumene concentrate, a key hard-rock lithium feedstock, fell 23.5% over the same period to $1,780 per tonne.

Lower prices can benefit battery makers and other buyers by reducing raw-material costs. However, they can also make it harder for mining companies to finance new projects, particularly those with high construction costs or more complex deposits.

This creates a difficult cycle. When prices rise, companies have a stronger incentive to expand supply. If many projects enter production around the same time, extra supply can then push prices down. When prices fall, developers may delay or cancel projects, potentially limiting future supply.

The IEA notes a big change in critical minerals. Market ups and downs have led to less capital spending. Following a sharp slowdown in previous years, global investment in critical mineral development declined by 9% in 2025, ending several consecutive years of growth.

The pullback was particularly severe for battery materials, where investment dropped by 20%. Mineral prices hit rock bottom for years. Then, they rebounded in late 2025 and early 2026. This change happened as supply tightened and export controls increased.

Lithium Carbonate 99.5% Price - CarbonCredits (8)

A market that appears well supplied today can therefore face a different outlook later. New mines take years to develop, so investment decisions must account for demand well beyond the current price cycle.

Australia, China and North America Face Shifting Supply Roles

The location of new mines will shape the future lithium supply chain. Benchmark forecasts that Australia will remain a major producer, but its share of mined lithium could fall from 29% in 2026 to 20% by 2050.

China’s share of mined supply is expected to remain around 25%, according to the forecast. Its position is stronger in processing, where Benchmark estimates that China controls roughly 70% of refined lithium production.

2025 lithium global production

North America could gain a larger role. Benchmark projects that its share of mined lithium will rise from 1.7% in 2026 to 13% by 2050 as the region seeks to meet more of its own demand and reduce reliance on imported materials.

Europe faces a different gap. The region currently produces less than 1% of mined lithium while accounting for 7% of demand from battery-cell production. By 2050, Benchmark expects Europe to supply 5.5% of mined lithium against 8% of cell-production demand.

These projections depend on projects moving forward. New mines in North America and Europe may help diversify supply, but some face higher costs, permitting delays, and environmental or community concerns.

More geographically diverse supply could reduce dependence on a small number of producers. However, building mines and processing facilities in new regions will require long-term funding and reliable demand from battery manufacturers.

benchmark-134-new-lithium-mines-infographic
Source: Benchmark Mineral Intelligence

Battery Recycling Could Ease Pressure on New Lithium Mines

Mining is not the only way to meet future lithium demand. Recycling used batteries can return lithium to the supply chain and reduce the need for newly mined material.

Benchmark expects recycled material to account for almost half of lithium supply by 2050. Its separate capital-spending analysis estimates that meeting 2040 demand would require around $64 billion in investment, assuming recycling supplies a significant share of future needs.

However, recycling cannot replace new mines immediately. Large volumes of EV batteries must reach the end of their useful lives before recyclers can recover their materials. Collection systems, processing capacity and the cost of recovered lithium will also affect how much material returns to the market.

Battery technology could change the outlook, too. Different battery chemistries use different amounts of lithium and other minerals. Advances in battery design, improved efficiency and changes in EV demand could alter the amount of lithium required for each unit of storage.

For now, Benchmark’s estimates suggest that recycling will help meet future demand but will not remove the need for substantial new mining capacity. If recycled supply falls short of expectations, the industry may need more mines than its base case assumes.

Lithium’s Long-Term Outlook Depends on Investment Today

Benchmark’s forecast puts a clear figure on the scale of the task: 134 mines and more than $100 billion in investment under its base case. Yet, the central issue is not simply whether enough lithium exists in the ground. It is whether the industry can finance, approve and build the projects needed to bring that supply to market.

The IEA’s analysis reinforces the importance of investment, supply chain diversification and recycling across critical minerals. But forecasts remain sensitive to prices, policy decisions, technology and project delays.

For the lithium industry, the next 24 years will require a steady flow of capital through both strong and weak market conditions. Recycling can ease pressure on new supply, while new mining projects will remain important to meeting demand.

The outcome will shape more than the fortunes of mining companies. Lithium is a key material for EV batteries and energy storage, which support the shift toward lower-emission transport and electricity systems. Whether the industry can build enough supply at the right time will be an important factor in how smoothly that transition progresses.

The post Lithium Needs $100 Billion and 134 New Mines to Meet 2050 Demand and Power the EV Boom appeared first on Carbon Credits.
Can Nuclear Energy Attract $6 Trillion in Investment by 2050? WNA Sees Massive Opportunity

Global investment in nuclear energy could reach approximately $6 trillion by 2050 as governments expand nuclear power to meet rising electricity demand and reduce carbon emissions. The World Nuclear Association (WNA) estimates that annual investment must rise to more than $250 billion to support government ambitions to more than triple global nuclear capacity.

Its July 2026 report, A $6 Trillion Investment Opportunity: Nuclear Value Chain Investment Through 2050, identifies opportunities across reactor construction, small modular reactors (SMRs), uranium mining, nuclear fuel processing and waste management.

The WNA’s October 2026 outlook estimates that global nuclear capacity could reach 1,467 gigawatts electric (GWe) by 2050 if existing reactors continue operating, planned projects advance and national capacity targets are achieved. However, meeting these ambitions will require much faster construction, stronger supply chains and greater access to private financing.

Nuclear Power Reaches Record Generation as Investment Needs Grow

Nuclear energy is attracting renewed interest as countries seek reliable, low-carbon electricity for industrial facilities, data centers and power grids. The latest WNA outlook reports that global nuclear electricity generation reached a record 2,701 terawatt-hours (TWh) in 2025, supplying around 9% of global electricity.

The existing reactor fleet also continues to perform strongly. The average nuclear reactor capacity factor reached 83.7% in 2025, reflecting the ability of operating plants to generate electricity consistently.

However, construction activity remains below the level needed to achieve global expansion targets. Eleven reactors started construction in 2025, including nine in China and two in Russia. The WNA estimates that construction rates must eventually rise to around six times current levels to triple nuclear capacity by 2050.

The investment opportunity extends beyond building new power plants. Existing reactors may require upgrades and lifetime extensions, while expanding nuclear capacity will increase demand for uranium, fuel processing, specialized equipment, and waste management.

NUCLEAR INVESTMENT
Source: WNA

Where Could the $6 Trillion Nuclear Investment Go?

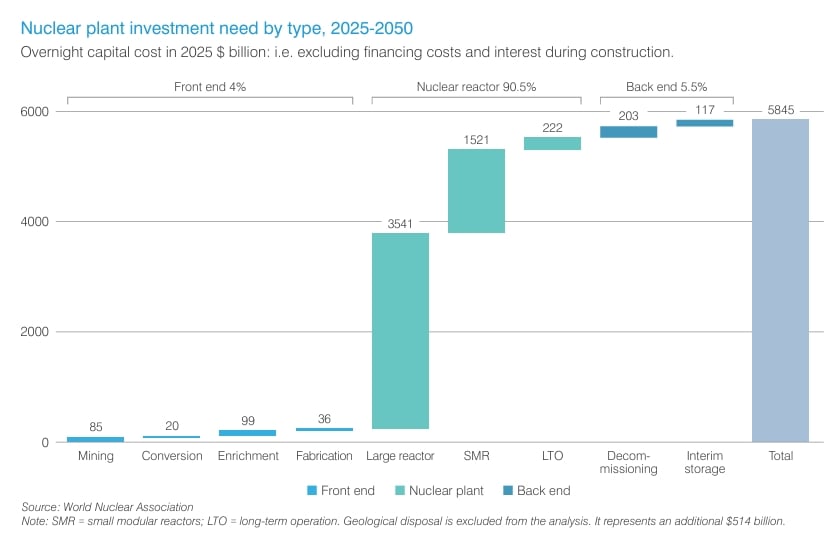
The WNA estimates that nuclear reactors will account for approximately $5.3 trillion, or 90.5%, of total investment across the nuclear value chain through 2050.

The main opportunities include:

  • Large nuclear reactors: Approximately $3.5 trillion in projected investment.
  • Small modular reactors: Around $1.5 trillion to support approximately 260 GW of capacity.
  • Existing nuclear plants: About $222 billion for lifetime extensions.
  • Nuclear fuel supply: Approximately $240 billion for uranium mining, conversion, enrichment and fuel fabrication.
  • Decommissioning and interim storage: Around $320 billion for managing the back end of the nuclear industry.

Geological disposal of nuclear waste could require another $514 billion, according to the report, although this amount is excluded from the headline $6 trillion estimate.

nuclear investment
Source: WNA

SMRs could become an important part of the expansion. These smaller reactors are designed to support standardized manufacturing and potentially shorter construction schedules. However, investors still need evidence that commercial projects can achieve competitive costs and reliable delivery.

The wider nuclear supply chain could also benefit. Uranium producers, enrichment companies, fuel fabricators, engineering firms and specialized equipment manufacturers may see stronger demand if reactor construction accelerates.

Can Nuclear Capacity More Than Triple by 2060?

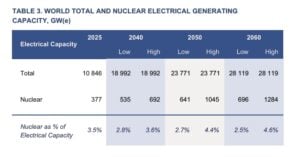
The International Atomic Energy Agency (IAEA) has extended its nuclear power projections to 2060 for the first time in its 2026 Energy, Electricity and Nuclear Power Estimates report.

The agency’s projections show a wide range of possible outcomes:

  • Low case: Global nuclear capacity reaches 696 GWe by 2060.
  • High case: Capacity rises to 1,284 GWe, more than three times the level at the end of 2025.
  • New capacity: The high case assumes approximately 1,017 GWe of additions by 2060, offset by around 128 GWe of retirements.
  • SMR contribution: Small modular reactors account for about 28% of new capacity in the high case.
IAEA
Source: IAEA

The IAEA also reported that 72 reactors, with a combined capacity of 77.2 GWe, were under construction at the end of 2025.

These projections are scenarios rather than guaranteed outcomes. Achieving the higher growth case will depend on national policies, financing, construction capacity, and the ability to complete projects on time.

Uranium Supply Could Create Another Investment Opportunity

Expanding nuclear power will require a larger and more reliable uranium supply. A September 2026 report from the OECD Nuclear Energy Agency (NEA) and the IAEA found that identified uranium resources are sufficient to meet even the highest projected demand through 2050. However, turning those resources into mine production will require sustained investment.

  • The agencies estimate that annual uranium requirements could rise from approximately 64,500 tonnes of uranium in 2025 to between 84,800 and 143,900 tonnes by 2050, depending on nuclear capacity growth.
  • Investment in exploration and mine development is already increasing. Global uranium exploration and development spending exceeded $1.78 billion during 2023 and 2024, approximately 46% higher than in 2021 and 2022.
uranium
Source: NEA

Yet new supply takes time to develop. The NEA says uranium mining projects typically require 15 to 20 years of development. Long-term contracts and adequate uranium prices will therefore be important to encourage new mines and reduce future supply risks.

This creates a potential opportunity for uranium miners and fuel suppliers, but rising demand alone does not guarantee higher profits. Project costs, uranium prices, permitting and the timing of new supply will influence returns.

What Could Hold Back Nuclear Investment?

Despite the scale of the opportunity, nuclear projects require substantial upfront capital and can take years to complete. Construction delays, cost overruns, licensing requirements, and supply-chain constraints can weaken project economics.

The WNA’s July 2026 financing roadmap identifies several conditions needed to attract more institutional capital:

  • Standardized reactor designs and repeatable project structures.
  • Clear rules for allocating construction and operating risks.
  • Predictable revenue models and long-term financing arrangements.
  • Stronger manufacturing capacity and skilled workforces.
  • Government support and credible plans for waste management and decommissioning.

Private investors may be more willing to finance nuclear projects when governments provide stable policies and developers demonstrate a track record of delivering plants on schedule.

Is Nuclear Energy a Long-Term Investment Opportunity?

The $6 trillion estimate highlights the potential scale of nuclear investment through 2050. Large reactors are expected to attract most of the spending, while SMRs, uranium mining, enrichment and fuel fabrication could offer additional opportunities across the supply chain.

For investors, the central question is whether governments can convert ambitious capacity targets into funded, operating projects. Nuclear power could become more important as electricity demand rises, but the industry must overcome financing challenges and improve construction performance.

The projected investment represents potential market demand, not guaranteed revenue or investment returns. Companies that can deliver projects efficiently and supply critical nuclear materials may be better positioned to benefit if the industry enters a sustained growth cycle.

The post Can Nuclear Energy Attract $6 Trillion in Investment by 2050? WNA Sees Massive Opportunity appeared first on Carbon Credits.