Amazon (Nasdaq: AMZN) and Constellation Energy (Nasdaq: CEG) have signed a 20-year power agreement to support the expansion and continued operation of the Calvert Cliffs nuclear power plant in Maryland.
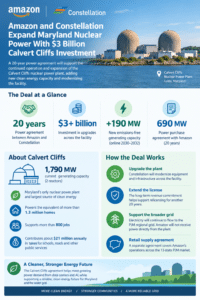
The agreement will help fund more than $3 billion in upgrades across the facility and add about 190 megawatts (MW) of new emissions-free generating capacity. The additional power is expected to come online between 2030 and 2032.
The EIA estimates data center servers already accounted for about 7% of U.S. commercial electricity consumption in 2025. By 2050, server electricity use could reach 446–818 billion kWh, depending on how quickly data center power demand grows.
The Deal Supports 190 MW Nuclear Capacity Increase
Calvert Cliffs currently has 1,790 MW of generating capacity, making it Maryland’s only nuclear power plant and its largest source of clean electricity.
Under the new agreement, Amazon will purchase 690 MW of power through a 20-year arrangement with Constellation. The deal includes the planned 190 MW uprate, which will increase the plant’s output without requiring construction of an entirely new reactor.
Constellation plans to use the investment to modernize equipment and infrastructure throughout the plant. The company also expects Amazon’s long-term revenue commitment to support the process of relicensing Calvert Cliffs for another 20 years.
The companies have also signed a separate retail electricity supply agreement covering Amazon’s operations across the 13-state PJM power market.
Importantly, the electricity generated at Calvert Cliffs will continue to enter the PJM regional grid. Amazon will not receive electricity directly from the plant. Instead, its long-term commitment helps support the economics of maintaining and expanding generation that serves the wider electricity system.
Calvert Cliffs Strengthens Maryland’s Power Supply
Calvert Cliffs plays an important role in Maryland’s electricity system. Constellation says the plant produces about 80% of the state’s clean energy and generates enough electricity to serve more than 1.3 million homes.
The facility also supports more than 800 jobs and contributes approximately $21 million in annual taxes for public services, including schools and roads.
The planned expansion will therefore affect more than the plant’s electricity output. The investment will support upgrades at an existing nuclear facility while helping maintain its workforce and local economic contribution.
Constellation also sees the site as a potential location for future clean energy projects. The company said Amazon’s long-term commitment will help it move forward with additional clean energy development at Calvert Cliffs.
U.S. Nuclear Power Remains a Major Electricity Source
The Calvert Cliffs agreement comes as nuclear power continues to provide a significant share of U.S. electricity.
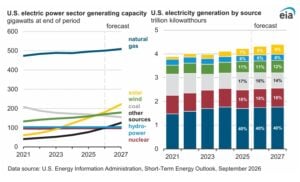
According to the U.S. Energy Information Administration’s September 2026 data, U.S. utility-scale nuclear capacity stood at about 98.4 gigawatts (GW) in July 2026. Nuclear power represented roughly 7.5% of total U.S. utility-scale generating capacity at that time.
Nuclear plants also generated about 460.1 terawatt-hours (TWh) of electricity during the first seven months of 2026, according to EIA data released in September. That was 1.5% higher than the comparable period in 2025.
EIA’s September 2026 Short-Term Energy Outlook also expects nuclear power to account for about 18% of U.S. electricity generation in both 2026 and 2027.
Source: EIA
These figures show why extending the operating life of existing reactors can add dependable generation without waiting for an entirely new nuclear plant to be built.
Amazon Builds a Large Clean Energy Portfolio
The Calvert Cliffs agreement adds to Amazon’s growing clean-energy portfolio. In 2025, Amazon said it had more than 700 renewable and carbon-free energy projects across 30 countries, representing more than 40 GW of capacity.
BloombergNEF has also ranked Amazon among the world’s largest corporate buyers of clean energy. The company contracted 10.22 GW of clean energy capacity in 2025.
Amazon’s major clean-energy and nuclear deals include:
X-Energy: In 2024, Amazon joined a $500 million funding round for X-Energy, which is developing small modular reactors. Amazon expects the partnership to support more than 5 GW of new nuclear capacity in the U.S. by 2039.
Energy Northwest: Amazon is supporting a planned SMR project in Washington state. The initial project is expected to provide 320 MW, with potential to expand to 960 MW.
Talen Energy: Amazon signed a long-term agreement to access power from Talen Energy’s Susquehanna nuclear plant in Pennsylvania. The deal can provide up to 1,920 MW through 2042.
The Calvert Cliffs agreement takes a different approach by supporting an existing reactor fleet and increasing its output through an uprate. This can provide additional capacity while preserving an established nuclear facility and its connection to the regional grid.
As U.S. power demand grows, deals like this can help fund nuclear plant upgrades while adding more reliable, emissions-free power to the grid. They also highlight how long-term corporate power agreements can support existing nuclear facilities and help enable new generating capacity.
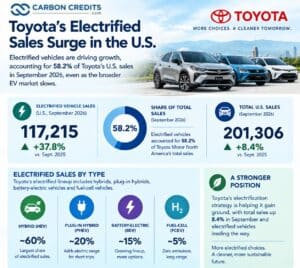
Toyota is showing that electrification can drive growth even as parts of the U.S. electric vehicle market slow. The Japanese automaker sold 117,215 electrified vehicles in the United States in September 2026, up 37.8% from a year earlier. Electrified vehicles accounted for 58.2% of Toyota Motor North America’s total September sales.
The result came as sales of Toyota’s gasoline-only vehicles fell sharply. Yet, total sales still increased 8.4% to 201,306 vehicles, outperforming the roughly 6.5% industry increase forecast by Cox Automotive.
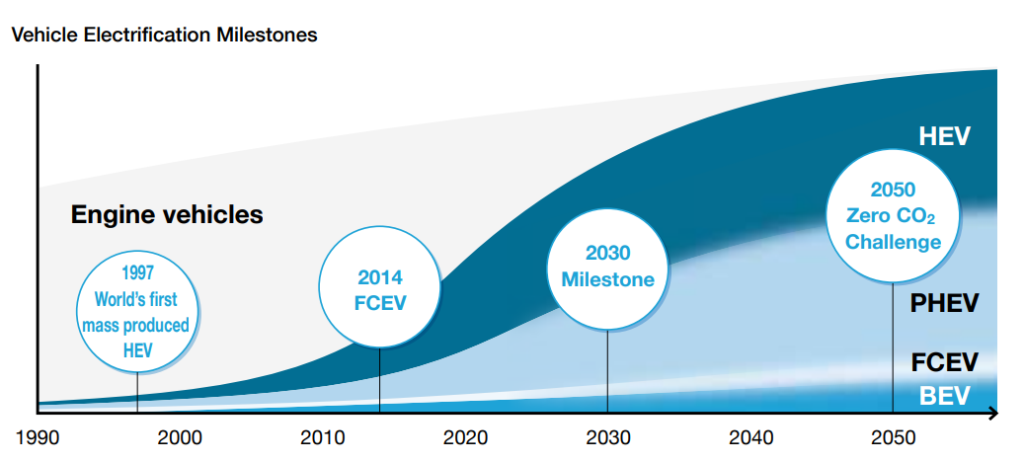
The numbers highlight Toyota’s different approach to electrification. Rather than relying mainly on battery-electric vehicles (BEVs), Toyota has built a broad lineup of hybrids, plug-in hybrids, BEVs and fuel-cell vehicles.
That strategy is now producing measurable sales growth.
Electrified Vehicles Are Driving Toyota’s U.S. Growth
Toyota’s September results were led by its electrified lineup. The company sold 117,215 electrified vehicles, up 32,125 units from September 2025. For the third quarter, electrified vehicle sales reached 363,367, up 28.5% year over year and representing 57.4% of total sales.
Toyota’s overall third-quarter sales reached 633,223 vehicles, up just 0.6%. That means electrified vehicles accounted for most of the company’s sales growth during the quarter.
The Toyota division sold 104,105 electrified vehicles in September, up 36.6%. Lexus added another 13,110, up 47.4%. Toyota also ended September with 32 electrified vehicle options across its Toyota and Lexus brands.
The contrast with conventional vehicles is significant. Toyota’s gasoline-powered sales fell 16.5% in September, according to reporting based on the company’s sales data. The figures suggest that electrification is increasingly supporting Toyota’s sales even when demand for traditional powertrains weakens.
Hybrids Are Doing Much of the Heavy Lifting
Toyota’s definition of “electrified” includes more than battery-electric vehicles. Its lineup includes conventional hybrids, plug-in hybrids, battery-electric vehicles, and fuel-cell vehicles. This gives the company a broader base for capturing consumers who want lower fuel consumption without moving immediately to a fully electric vehicle.
Source: Toyota
Andrew Gilleland, senior vice president, Automotive Operations Group, Toyota Motor North America, noted:
“Our third-quarter results reinforce a simple truth—customers want choices. From affordability to electrification, our multi-path strategy continues to meet customers where they are and give them options that fit their lifestyles. With solid momentum and disciplined inventory heading into Q4, we’re well-positioned to finish the year strong.”
That approach is particularly relevant in the U.S., where EV adoption has faced affordability and policy challenges.
The International Energy Agency estimates that electric cars accounted for just under 10% of U.S. car sales in 2025, compared with 25% globally. Global electric car sales exceeded 20 million units in 2025, up 20% from 2024.
Toyota’s results show that consumers can still shift toward electrified powertrains even when BEV adoption is slower.
The company’s June results had already shown the trend. Toyota sold 122,063 electrified vehicles in the U.S. that month, up 35%, while second-quarter electrified sales reached 383,091, up 19.5%. The September figures indicate that momentum continued into the third quarter.
Toyota Is Closing the Gap With GM
The electrification-led sales growth is also helping Toyota gain ground on General Motors in the U.S. Toyota sold 633,223 vehicles in the third quarter, compared with GM’s 670,974. GM’s sales fell 5.5%, while Toyota’s edged up 0.6%.
Toyota therefore trailed GM by only about 37,751 vehicles during the quarter.
Cox Automotive said Toyota was gaining market share as consumers shifted toward hybrids and passenger cars, areas where Asian automakers have maintained a strong position. Toyota’s growth is notable because its strategy does not depend solely on BEV sales.
It has continued investing in hybrids while expanding its battery electric lineup. This gives the company multiple ways to respond to changes in fuel prices, consumer preferences, incentives, and emissions regulations.
The approach also gives Toyota time to expand its BEV business while maintaining sales from its established hybrid franchise.
Global EV Sales Are Still Growing
Toyota’s results come against a global backdrop of continued EV expansion. The IEA expects global electric car sales to reach about 23 million vehicles in 2026, representing roughly 28% of total car sales. Europe is projected to see EV sales increase about 20%, taking electric vehicles to approximately one-third of new-car sales.
China’s electric car share is expected to approach 60% this year. However, growth is becoming less uniform.
Global EV sales were about 3.9 million in the first quarter of 2026, down 8% from the same period in 2025. The decline was largely linked to weaker sales in China and the U.S. following policy changes. Europe moved in the opposite direction, with first-quarter EV sales rising close to 30% year over year.
The IEA also expects the number of electric-car models available globally to exceed 1,100 in 2026, with about 150 new electric models announced for the year. That means competition is increasing even as the overall market expands.
Toyota’s own forecasts show that electrification will become a larger part of its global sales. For fiscal 2027, Toyota forecasts 10.5 million Toyota and Lexus vehicle sales, broadly flat from fiscal 2026.
But it expects electrified vehicle sales to rise from 5.04 million to 5.956 million units. That would increase the electrified share from 48.1% to 56.7%.
Toyota expects total electrified sales to approach 6 million vehicles in fiscal 2027. It also expects hybrid sales to exceed 5 million for the first time.
The numbers show where Toyota sees near-term demand. Hybrids remain the largest part of the strategy, while BEV sales are expected to more than double.
The Sales Surge Also Supports Toyota’s Climate Strategy
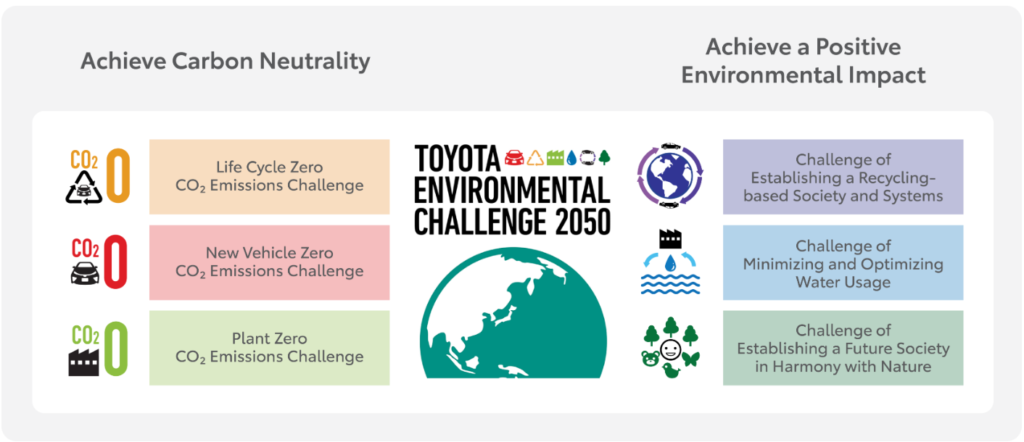
Toyota’s broader environmental strategy is built around its Environmental Challenge 2050, which includes six targets covering carbon emissions, water, circularity and biodiversity.
The company aims to achieve carbon neutrality across the vehicle lifecycle by 2050. In North America, Toyota aims to make all facilities carbon neutral by 2035.
Toyota reported a 32% reduction in Scope 1 and Scope 2 greenhouse-gas emissions from its North American operations compared with FY2019 as of FY2025.
Source: Toyota
It is also increasing renewable electricity use. At the end of FY2025, 114 participating Toyota dealerships had reduced their use of electricity from nonrenewable sources by 20% through the company’s environmental program.
Electrified vehicles form an important part of this strategy because they can reduce tailpipe emissions compared with conventional vehicles. However, Toyota’s multi-pathway approach also reflects the different infrastructure and energy conditions across markets.
Toyota Stock Reflects a More Complicated EV Story
Toyota’s electrification gains have not translated into a sustained rise in its U.S.-listed shares.
Toyota Motor’s NYSE-listed ADR closed at $183.10 on September 30, down 1.93% that day. It closed at $183.34 on October 1 and $181.49 on October 2. The stock had been trading near $198 in early September, putting it roughly 9% below its September 11 close by October 2.
The movement reflects broader concerns around the global auto market, including tariffs, China competition, fuel prices, interest rates, and changing EV policies. Still, Toyota’s sales data offer a different signal.
The company’s electrified vehicles are gaining share even as the broader U.S. auto market faces uneven EV demand. Its third-quarter electrified sales rose nearly 29%, while total sales were almost flat.
Hybrids Put Toyota on a Different EV Growth Path
Toyota’s latest U.S. results show a different path through the global auto industry’s transition. Globally, EV adoption continues to expand. The IEA expects electric vehicles to represent 28% of global car sales in 2026, with roughly 23 million electric cars sold.
Toyota’s own forecast points to nearly 6 million electrified vehicle sales in fiscal 2027, including almost 600,000 BEVs. The figures suggest Toyota’s electrification strategy is broadening rather than shifting entirely toward battery-electric vehicles.
For now, hybrids remain the company’s largest electrified segment. But with BEV sales forecast to more than double, Toyota is also increasing its exposure to the fastest-changing part of the automotive market. That combination is helping the automaker buck the recent U.S. EV slowdown while keeping its longer-term carbon neutrality targets in focus.
https://globalcarbonfund.com/wp-content/uploads/2018/10/GCF_header_logo_340x156.png00carbonfundhttps://globalcarbonfund.com/wp-content/uploads/2018/10/GCF_header_logo_340x156.pngcarbonfund2026-10-05 10:14:272026-10-05 10:14:27Toyota (TM Stock) Bucks the EV Slowdown as Electrified Sales Surge Nearly 40%
Tesla (NASDAQ: TSLA) delivered more vehicles than Wall Street expected in the third quarter of 2026, giving investors a reason to turn more positive on the electric vehicle maker’s near-term outlook.
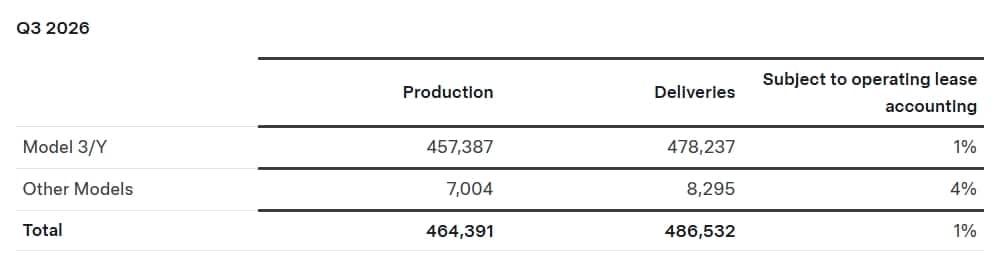
Tesla delivered 486,532 vehicles in Q3, beating the company-compiled analyst consensus of 461,974. Deliveries also rose 1.3% from 480,126 vehicles in Q2. However, they remained 2.1% below the 497,099 vehicles delivered in Q3 2025.
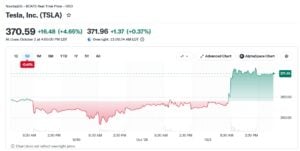
The stronger-than-expected result helped Tesla stock rebound. Shares closed at $370.59 on October 2, up 4.7% in the session. Reuters reported that the stock gained more than 5% earlier in trading after the delivery figures were released.
Source: Yahoo Finance
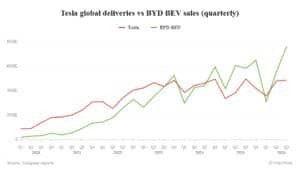
Still, Tesla faces a growing challenge from Chinese EV giant BYD. BYD’s battery-electric vehicle sales continued to pull further ahead of Tesla during the quarter.
Tesla Q3 Deliveries Beat Estimates
Tesla’s Q3 delivery result came in well above the latest company-compiled consensus.
Analysts surveyed by Tesla had expected 461,974 deliveries, with a median estimate of 463,406. Tesla ultimately delivered 486,532 vehicles, exceeding the consensus by about 24,600 vehicles.
The Model 3 and Model Y remained the company’s main volume drivers. Tesla delivered 478,237 Model 3/Y vehicles during the quarter, compared with just 8,295 deliveries across its other models.
Production, meanwhile, reached 464,391 vehicles.
Tesla also deployed 13.7 gigawatt-hours (GWh) of energy storage products during Q3. That figure was below the 15.9 GWh analyst consensus, highlighting that Tesla’s energy business remains an important part of the company’s broader growth story.
The delivery beat is significant because analysts had entered the quarter expecting a decline. FactSet estimates cited by MarketWatch had pointed to roughly 461,000 vehicles, or a 7% year-over-year decline.
Despite Tesla’s better-than-expected quarter, its competition with BYD is becoming more intense.
BYD sold 762,478 battery-electric passenger vehicles during Q3, according to data compiled by CnEVPost. That was up nearly 31% from a year earlier and 37% from Q2.
As a result, BYD sold about 275,946 more battery-electric vehicles than Tesla during the quarter.
The comparison needs some context. Tesla reports deliveries of its vehicles, while BYD sells both battery-electric vehicles and plug-in hybrids under its broader new-energy vehicle category.
BYD sold 1.32 million new-energy vehicles in Q3, including both types. Total NEV sales rose 18.8% year over year.
BYD also recorded 463,561 new-energy vehicle sales in September alone, its strongest monthly result of 2026. Overseas passenger vehicle and pickup shipments jumped 153.9% year over year to 179,877 in September, Reuters reported.
Source: CNeV
This international expansion could become increasingly important for the global EV market. It also shows how competition is moving beyond traditional EV strongholds as Chinese manufacturers expand into overseas markets.
Sustainability Remains a Key Part of Tesla’s Story
Tesla’s delivery numbers also matter from a sustainability perspective because more EV sales can accelerate the shift away from gasoline-powered vehicles.
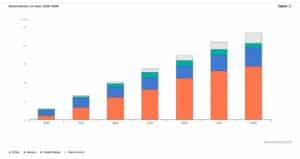
The International Energy Agency said global electric car sales exceeded 20 million in 2025, with EVs accounting for one in four new cars sold worldwide. China remained the largest EV market, accounting for six out of 10 electric cars sold globally.
Source: IEA
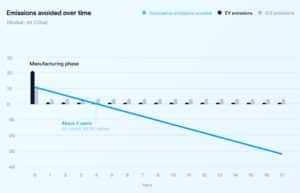
Tesla says its products helped avoid 37 million metric tons of CO₂e emissions in its 2025 Impact Report. The company’s sustainability strategy also extends beyond vehicles to battery storage, solar energy, and its supply chain.
The company also highlighted the emissions benefit of its electric vehicles over their operating lives. It estimates that one Tesla vehicle can avoid about 32 metric tons of CO₂ emissions over its lifetime compared with a comparable gasoline-powered vehicle. However, the actual benefit varies by factors such as electricity generation, vehicle efficiency, and driving patterns.
Source: Tesla
However, EV growth does not eliminate the environmental impact of manufacturing. Batteries require minerals such as lithium, nickel, graphite, and other materials, while vehicle production and electricity generation also create emissions.
That makes the growth of energy storage particularly relevant. Tesla deployed 13.7 GWh of storage products in Q3, while the company-compiled analyst consensus had expected 15.9 GWh.
Large-scale batteries can help integrate renewable power into electricity systems by storing electricity when supply is high and releasing it when demand rises.
Can Tesla’s Q3 Delivery Beat Support Its Stock?
Tesla stock entered October under pressure after a volatile year. Shares closed at $370.59 on October 2, although the latest delivery beat provided some relief.
Investors are now looking beyond vehicle sales. Tesla’s valuation increasingly depends on its plans for robotaxis, AI, robotics and energy storage, while its automotive business remains critical to funding those investments.
Tesla will report its full Q3 financial results on October 21. The earnings report should give investors a clearer view of vehicle margins, revenue, cash flow, and spending on its next-generation businesses.
For now, the delivery beat strengthens Tesla’s near-term position. However, BYD’s growing lead in battery-electric vehicle sales highlights the competitive pressure facing Tesla as global EV adoption accelerates.
The longer-term sustainability opportunity remains significant, but Tesla must balance EV growth with improving manufacturing efficiency, battery supply chains and the emissions impact of its operations.
https://globalcarbonfund.com/wp-content/uploads/2018/10/GCF_header_logo_340x156.png00carbonfundhttps://globalcarbonfund.com/wp-content/uploads/2018/10/GCF_header_logo_340x156.pngcarbonfund2026-10-05 10:14:272026-10-05 10:14:27Tesla (TSLA) Q3 Deliveries Beat Analysts’ Expectations, But BYD Widens EV Lead
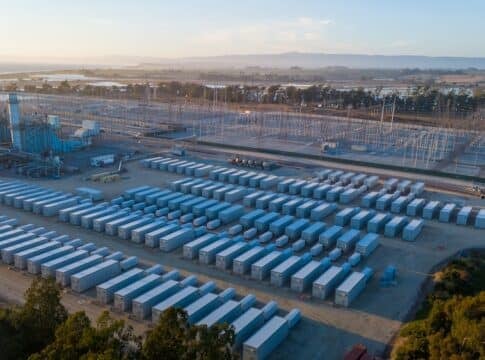
US-based Antora Energy is planning a 5.8 gigawatt-hour (GWh) multi-day thermal energy storage project at Pratt Energy’s biorefinery in Pratt, Kansas.
The project will provide reliable, around-the-clock energy to the ethanol facility while supporting local jobs, workforce training, and new investment in Pratt County.
The press release also highlighted that once completed, the project is expected to rank among the world’s largest battery storage systems. Antora plans to begin delivering energy to Pratt Energy next year under a long-term heat offtake agreement.
The project is backed by Copenhagen Infrastructure Partners (CIP), Australian investment firm Grok Ventures and University Pension Plan Ontario (UPP). CIP led the third-party equity financing through its credit platform investments.
The deal comes as U.S. industries face rising electricity demand and growing pressure to secure reliable, affordable energy while reducing emissions.
Antora’s Thermal Battery Targets Industrial Energy Demand
Antora Energy is a U.S. energy storage company focused on thermal batteries that store electricity as heat and later deliver it as heat or power.
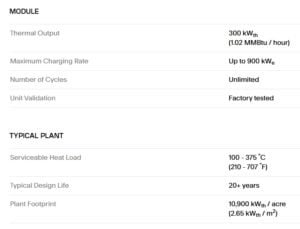
Instead of relying on conventional lithium-ion battery chemistry, Antora stores energy in insulated blocks of solid carbon. The system can absorb low-cost electricity when it is available and release energy when industrial customers need it.
This approach allows the company to target industrial facilities that require continuous heat and power.
Antora says its technology does not rely on supply-constrained critical minerals. It also uses factory-built modules, which could help reduce construction timelines compared with some large energy infrastructure projects.
“Antora’s thermal energy storage is the new standard for powering always-on operations with low-cost energy”
Source: Antora
Expanding Its U.S. Energy Storage Footprint
The Kansas project follows Antora’s recent expansion in the U.S. energy storage market. Earlier this year, the company commissioned a 5 GWh thermal energy storage system in Big Stone City, South Dakota.
The company also expects the project to create and support more than 100 construction and operations jobs.
David Bierman, co-founder and Chief Commercial Officer of Antora, said:
“American industry runs on affordable, reliable energy. Our partnership with Pratt Energy delivers it, helping meet Kansas’s rising energy demand without increasing power bills for homes or businesses. This biorefinery project is creating jobs and spurring local investment without straining the resources the community depends on.”
Pratt Energy Could Move Toward Lower-Carbon Ethanol
Pratt Energy operates an ethanol biorefinery that processes locally grown corn and sorghum into transportation fuel and co-products used in biodiesel and animal feed.
The company has operated in Pratt since 2013 and works with farmers across the region.
The new thermal storage system could help the facility improve energy efficiency while lowering the carbon intensity of its products.
Antora said the project could help Pratt Energy move toward producing ethanol with a 100% zero-carbon-intensity profile. Lower-carbon ethanol could also open additional markets for Kansas agricultural products as fuel buyers place greater emphasis on emissions.
Additionally, the project is expected to use little additional water beyond Pratt Energy’s existing operations. It is also designed to operate without increasing noise levels for nearby properties.
For the ethanol industry, access to lower-carbon energy can become increasingly important as producers seek to reduce emissions across their operations and improve the environmental profile of their fuels.
The long-term heat offtake agreement also gives Antora a committed industrial customer for the project, creating a direct link between energy storage and industrial demand.
Investors Back Large-Scale Thermal Energy Storage
Copenhagen Infrastructure Partners is one of the investors backing the Kansas project.
CIP is a global energy infrastructure investment firm that invests across areas including renewable power, energy storage, transmission, low-carbon fuels, advanced bioenergy and carbon capture.
The firm has raised about $49 billion to date and manages 15 funds, according to the company.
CIP’s involvement highlights the growing interest from infrastructure investors in energy storage technologies that can serve industrial customers and provide longer-duration energy.
Grok Ventures is also participating in the financing. The Australian investment firm focuses on technology-driven solutions across major global challenges, including the energy transition.
UPP, a Canadian pension fund, is the third financial participant in the project.
The investment group gives Antora access to capital as it moves from individual demonstrations toward larger commercial deployments.
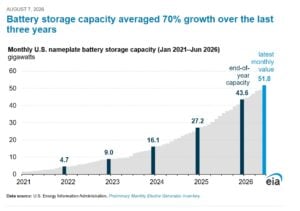
Utility-scale battery storage capacity reached nearly 52 gigawatts (GW) by June 2026, after operators added 8.3 GW during the first half of the year. The U.S. had 43.6 GW of operational utility-scale battery storage at the end of 2025, with capacity growing at an average annual rate of 70% over the past three years, according to EIA data.
The growth is expected to continue. U.S. developers plan to add about 24 GW of utility-scale battery storage in 2026, up from a record 15 GW added in 2025.
Battery storage accounts for about 28% of the 86 GW of new utility-scale generating capacity planned for the U.S. this year.
Source: EIA
Battery Storage Market Moves Beyond Short-Duration Systems
The Kansas project also highlights how the battery storage market is expanding beyond conventional short-duration electricity storage.
Most large battery projects deployed today use lithium-ion technology and typically provide power for a few hours. Thermal energy storage can address a different part of the market by storing energy for longer periods and delivering industrial heat directly.
That matters because many industrial facilities cannot simply replace fossil-fuel-based heat with electricity without changing how they operate.
Thermal batteries could provide another pathway by storing electricity during periods of lower prices and then supplying heat when needed.
The approach could become particularly useful as renewable energy expands and power markets experience larger differences between periods of high and low electricity prices.
Antora’s system is designed to provide both heat and power, allowing the same basic technology to serve industrial facilities or potentially support the wider grid.
The company says its thermal batteries can be deployed for industries including chemicals, food production and steel, as well as for grid applications.
The Bottom Line
For Antora, the Kansas project represents another step toward commercial-scale deployment. For Pratt Energy, it could provide reliable energy while supporting efforts to lower the carbon intensity of ethanol production.
The project also shows how energy storage investments can extend beyond batteries and grid services. By connecting storage directly with industrial heat demand, companies can use new energy technologies to improve operations, reduce emissions, and strengthen the economics of low-carbon products.
As more U.S. industries look for reliable energy and lower-carbon production, projects like Pratt could help expand the role of thermal batteries in the country’s energy transition.
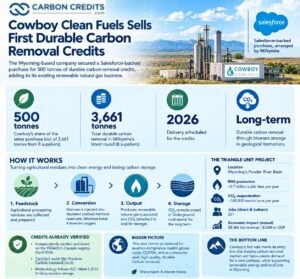
Cowboy Clean Fuels has sold its first durable carbon removal credits through a Salesforce-backed purchase arranged by Milkywire, with delivery scheduled for 2026. The Wyoming-based company said the transaction marks its entry into the durable carbon removal market. It adds carbon removal sales to its existing business producing renewable natural gas (RNG).
Cowboy is one of eight carbon removal suppliers included in Milkywire’s latest Salesforce-backed purchasing round. The group covers 3,661 tonnes of durable carbon removal across direct air capture, ocean alkalinity, biomass storage and related approaches.
Cowboy accounts for 500 tonnes of that total. The volume is small compared with the scale of global emissions. But the transaction is important for a different reason. Cowboy’s project is already operating, and the purchase helps create demand for a relatively new carbon removal pathway.
Ryan Waddington, Chief Executive Officer, Cowboy Clean Fuels, said:
“Durable carbon removal needs pathways that can be verified today and expanded tomorrow, and Wyoming’s subsurface gives us both. Buyers working with us get permanent removal alongside carbon-neutral renewable gas from the same operations, a combination very few suppliers can offer. This is an important step for Cowboy Clean Fuels and for the rural communities in Campbell County, Wyoming, that make the work possible.”
Cowboy Turns Farm Residues Into Carbon Removal
Cowboy’s process combines biomass carbon removal and storage (BiCRS) with renewable natural gas production. The company takes agricultural processing residues and injects them into depleted coalbed methane reservoirs in Wyoming’s Powder River Basin. Microorganisms inside the coal seams break down the biomass without oxygen.
That process produces methane and carbon dioxide.
Cowboy captures the methane as renewable natural gas, while the CO2 becomes attached to the coal and remains stored underground. The company calls this its BiCRS+RNG process.
The model differs from traditional bioenergy with carbon capture and storage (BECCS). In BECCS, biomass is burned for energy, and the CO2 produced is captured.
Cowboy instead relies on natural microbial activity underground. The company uses existing coalbed methane wells and infrastructure. This cuts down on the need for new infrastructure.
The Triangle Unit Is Already Operating
The carbon removal credits come from Cowboy’s Triangle Unit project, located in Wyoming’s Powder River Basin. The project is already operating. Cowboy says the facility started commercial operations after getting approval from Wyoming authorities. It has been injecting biomass to convert it into methane and CO2.
When fully operational, the Triangle Unit will produce about 0.7 billion cubic feet of renewable natural gas each year. It will also sequester around 180,000 metric tons of CO2 annually, as stated by the company. The project is also designed around existing energy infrastructure.
That approach could help lower capital requirements compared with building an entirely new carbon removal facility. Cowboy says it can also extend the useful life of existing wells and infrastructure while creating new income for land and resource owners.
The company estimates the project will support 221 jobs directly and indirectly. It will generate $8.8 million in annual tax revenue. Also, it will add over $36 million to Wyoming’s GDP each year when fully operational. These are company estimates rather than measured economic results.
Source: Cowboy
Carbon Removal Credits Were Already Verified
The Salesforce-backed purchase is not the first time Cowboy has brought its carbon removal credits to the market. In April 2026, the company announced that its credits were independently verified and listed on the Evident C-Capsule registry. This means they are now available for purchase. The projects were certified under the Absolute Carbon Standard (ACS).
Cowboy has said its methodology follows ISO 14064-2:2019 and is designed for long-duration geological storage.
Climate Vault Solutions picked the Triangle Unit project for its carbon removal portfolio. This decision followed a review by its Technology Experts Chamber. Climate Vault said the project was the first BiCRS project to pass its review and that Cowboy became part of its independently vetted supplier portfolio.
These steps are important because carbon removal buyers increasingly want evidence that projects can measure and account for their net climate benefit.
Cowboy has also faced questions because its process uses coal formations and creates methane. The company says no coal is burned in its process and that the methane is captured for use as renewable natural gas. The CEO said the company is tackling issues like permanence, methane, and lifecycle emissions. They focus on measurement and third-party review.
The purchase is part of Salesforce’s commitment to contract $100 million of durable carbon dioxide removal by 2030. Salesforce made the commitment in 2022 as a founding member of the First Movers Coalition. The company says the goal is to help create demand for carbon removal technologies before they reach full commercial scale.
Milkywire is helping Salesforce deploy part of that commitment through smaller purchases from early-stage suppliers.
In January 2026, Milkywire made over 12,500 tonnes of Salesforce-backed purchases. These came from 19 suppliers and involved six carbon removal methods across 15 countries. That programme was valued at about $5 million and focused on technologies that were not yet attracting enough buyers.
The latest round adds another 3,661 tonnes from eight suppliers. Cowboy’s 500-tonne purchase is therefore one piece of a broader portfolio.
Milkywire says it has now facilitated more than $12 million of durable CDR purchases across 45-plus projects in more than 20 countries. The approach is important for newer technologies because early buyers can provide revenue before projects reach large commercial scale.
Durable CDR Is Growing, But Delivery Is Still Limited
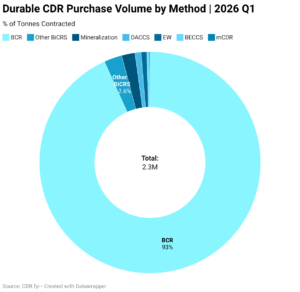
The Cowboy transaction comes as the durable carbon removal market grows rapidly. CDR.fyi reported that durable carbon removal purchases in Q1 2026 reached about 2.3 million tonnes, the largest first quarter on record.
Source: CDR.fyi
The total was 564% of Q1 2024’s volume. More than 113 buyers other than Microsoft contracted about 1.3 million tonnes during the quarter. But there is still a large difference between contracts and actual deliveries.
CDR.fyi said in June that durable CDR purchases outside Microsoft and Frontier had grown at a 151% compound annual rate from 2021 to 2025, while deliveries had grown at 131%. Biomass carbon removal and storage methods accounted for 96% of purchase volume and 91% of delivered volume in 2025.
This makes Cowboy’s sale notable. The company is not only signing a future purchase agreement. It is selling credits from an operating project with delivery in 2026. That moves the transaction closer to actual market performance rather than a long-term promise.
Could BiCRS Become CDR’s Next Growth Engine?
Biomass-based removal is receiving growing attention because it can combine carbon storage with energy production or waste management.
Cowboy’s model is one example. Other projects use biochar, BECCS, or underground biomass storage. The common idea is to take carbon absorbed by plants and keep it out of the atmosphere for a long period.
The challenge is proving the full climate benefit. Projects need to account for emissions from growing, collecting, and transporting biomass, as well as energy use and other parts of the supply chain. They must also show that the carbon remains stored for the required period.
Cowboy’s use of agricultural processing residues could help because the company is using an existing waste stream rather than growing dedicated energy crops. However, the sustainability and availability of feedstock will remain important as the company scales.
Cowboy is exploring more projects in the Powder River Basin. They are also contracting stronger carbon removal volumes and carbon-negative RNG supply.
The First Sale Tests a New Business Model
Cowboy’s first durable CDR sale is small in volume, but it links several parts of the emerging carbon market.
Salesforce’s approach also shows how large companies can help finance early CDR projects through smaller, targeted purchases. The bigger test is scale. Cowboy must demonstrate that it can grow while ensuring reliable carbon accounting, a sustainable biomass supply, and long-term storage.
The 500-tonne purchase does not prove that the technology can deliver hundreds of thousands of tonnes of removals. But it gives the company an important commercial milestone and provides a real-world test of its carbon removal pathway.
For the wider market, the development shows that durable carbon removal is slowly moving from early commitments toward actual deliveries. More buyers are entering the market. Projects that show measurable removals, clear accounting, and strong performance may secure bigger contracts.
Chinese electric-vehicle makers are finding a new way to monetize their lead in electrification: selling regulatory carbon credits to global automakers that need them to meet emissions rules. XPENG is the latest example.
The Chinese EV maker has signed carbon credit agreements with Porsche and other international automakers covering the European Union, the UK, and Australia, according to recent reports. The total transaction value is expected to exceed 1 billion yuan ($149 million), while XPENG expects to receive more than 500 million yuan ($74.5 million) from carbon-credit trading in 2026. An XPENG vice president confirmed the figures publicly.
The development points to a wider shift in the global auto industry. Chinese manufacturers are no longer only exporting electric cars. Their growing EV sales are also creating regulatory assets that other automakers can use to manage fleet emissions.
Europe’s Carbon Rules Put a Price on EV Advantage
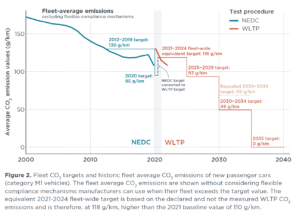
The European Union’s CO₂ rules are the main driver behind this market. Under the current framework, new passenger cars registered in the EU face a fleet-wide target of 93.6 grams of CO₂ per kilometer for 2025–2029. The target falls to 49.5 g/km from 2030 to 2034, before reaching 0 g/km from 2035 under the existing regulation.
Source: ICCT
Automakers can form emissions pools. This allows manufacturers with lower fleet emissions to combine their results with manufacturers that have higher emissions. The system creates a financial value for automakers that sell large numbers of zero-emission vehicles.
The EU also applies an excess-emissions premium of €95 for each gram of CO₂ per kilometer above the applicable target for each new vehicle, subject to the rules governing the relevant compliance period. For manufacturers selling large numbers of higher-emission vehicles, surplus credits from EV-heavy manufacturers can therefore have significant financial value.
The system is already operating at scale. In 2025, several major automakers formed pools involving Tesla, while Mercedes established a pool involving Volvo Cars, Polestar and Smart.
XPENG is now entering this market as a supplier of compliance capacity.
XPENG and Porsche Open a New China-Europe Link
The most notable agreement involves Porsche.
According to an official European Commission filing cited in recent reporting, Porsche withdrew from the Volkswagen Group’s internal emissions pool and established an independent, open pool for 2026 and 2027, with XPENG as a key partner. Financial terms have not been disclosed.
The structure is important because Porsche has a large portfolio of performance and premium vehicles, while XPENG’s fleet is centered on battery-electric vehicles.
In a regulatory emissions pool, the calculation is straightforward: more zero-emission vehicles can lower the average emissions of the combined fleet.
XPENG therefore gains another source of revenue from its EV sales without needing to sell the credits as conventional voluntary carbon offsets. That distinction matters.
These are regulatory CO₂ compliance credits, created by vehicle-emissions rules. They are not the same as voluntary carbon credits generated by projects such as forests, methane capture, or direct air capture.
China’s EV Boom Is Creating the Credit Supply
XPENG’s ability to generate credits comes from the rapid expansion of its electric vehicle business. The International Energy Agency estimates that global electric car sales exceeded 20 million units in 2025, up 20% from 2024. One in four new cars sold worldwide was electric.
China remained the largest EV market, with more than 13 million electric cars sold in 2025. Nearly 55% of all new cars sold in China were electric. Chinese manufacturers also accounted for 60% of global electric car sales in 2025.
Source: IEA
The production advantage is just as large. China produced about 16 million electric cars in 2025, nearly 75% of global EV output. Chinese electric car exports more than doubled to over 2.5 million units.
Europe is becoming an increasingly important destination.
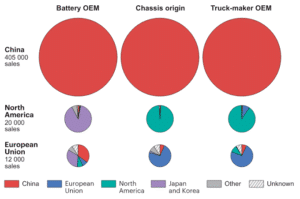
Sales of Chinese-made electric cars in Europe increased by almost 50% in 2025 to about 940,000 units, according to the IEA. Chinese brands accounted for more than 70% of Chinese-made EV imports into the EU, up from 50% in 2023. This expanding overseas EV fleet is also expanding the potential pool of regulatory credits.
XPENG’s Global EV Expansion Adds Another Revenue Stream
XPENG’s overseas business is expanding rapidly. The company delivered 45,008 vehicles outside China in 2025, up 96% year over year, while total deliveries reached 429,445, up 126%. It was selling vehicles in 60 countries and regions by year-end.
In Q2 2026, overseas sales topped 20,000 vehicles for the first time, up 81% year over year. Overseas revenue accounted for more than 25% of first-half revenue, with an average selling price above €40,000.
XPENG has also expanded its partnership with Volkswagen, which acquired a 4.99% stake for about $700 million in 2023. Their first jointly developed model entered mass production in March 2026.
The growing overseas EV business can therefore support both vehicle sales and XPENG’s ability to generate compliance value in regulated markets.
Leapmotor Shows XPENG Is Not Alone
XPENG is not the first Chinese automaker to monetize surplus emissions performance. Leapmotor transferred EU carbon credits to Stellantis for European and UK sales, generating 1.11 billion yuan ($165 million) in 2025. Its 2026 credit trading cap was later raised to 2.8 billion yuan ($417 million).
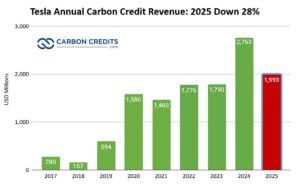
Tesla has used the same model for years, reporting about $2 billion in regulatory credit revenue in 2025, down from $2.76 billion in 2024.
For EV makers, regulatory credits can provide additional revenue. For automakers with higher fleet emissions, they can offer another compliance tool. However, their value remains dependent on emissions rules, pooling arrangements, and future regulatory changes.
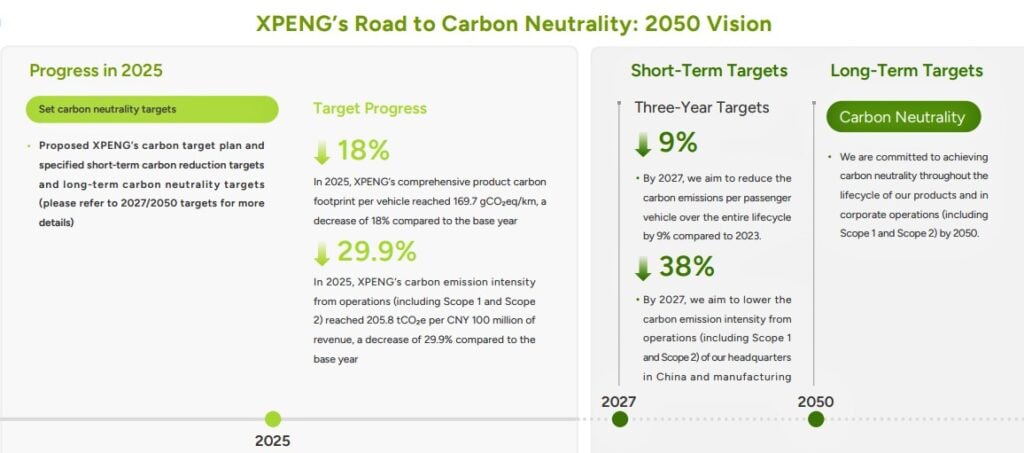
XPENG’s carbon strategy extends beyond regulatory credits. Its 2025 ESG report targets a 9% reduction in lifecycle carbon emissions per passenger vehicle by 2027 from 2023 levels, alongside a 38% reduction in operational carbon emissions intensity.
The company aims for carbon neutrality across its product lifecycle and corporate operations by 2050.
Source: XPENG
In 2025, XPENG reported a product carbon footprint of 169.7 grams of CO₂e per kilometer, down 18% from 2023. Operational carbon emissions intensity fell 29.9% to 205.8 tonnes of CO₂e per CNY 100 million.
It also recorded 73,000 MWh of clean energy consumption and 106,000 MWh of photovoltaic generation. XPENG estimates its 2025 vehicles will avoid more than 6 million tonnes of lifecycle greenhouse-gas emissions compared with conventional vehicles.
More EVs Mean a Bigger Compliance Credit Pool
The expanding EV market provides the underlying supply of these compliance assets. The IEA expects global electric-car sales to reach about 23 million vehicles in 2026, or roughly 28% of total car sales. EVs could account for about one-third of European sales and nearly 60% of China’s market.
By 2035, the global EV fleet could exceed 450 million vehicles under the IEA’s Current Policies Scenario.
Europe’s fleet is also becoming cleaner. Average CO₂ emissions from new passenger cars fell 28% between 2019 and 2024, while zero-emission vehicles accounted for 14.5% of new registrations in 2024.
As EV adoption rises and emissions rules tighten, the market for regulatory carbon credit transfers could expand.
Chinese EV Makers Are Turning Electrification Into a New Asset Class
XPENG’s agreements with Porsche and other international automakers show how China’s EV advantage is creating a new source of commercial value. Chinese EV exports exceeded 2.5 million vehicles, and Europe imported about 940,000 Chinese-made EVs.
Against this backdrop, XPENG expects more than 500 million yuan ($74.5 million) in carbon credit revenue in 2026. For European automakers, these credits provide another compliance tool as emissions standards tighten. For Chinese EV makers, they create an additional revenue stream from their growing zero-emission vehicle fleets.
Chinese automakers are therefore increasingly selling not only electric vehicles into Europe, but also the emissions-compliance value created by those vehicles.
https://globalcarbonfund.com/wp-content/uploads/2018/10/GCF_header_logo_340x156.png00carbonfundhttps://globalcarbonfund.com/wp-content/uploads/2018/10/GCF_header_logo_340x156.pngcarbonfund2026-10-02 12:14:352026-10-02 12:14:35Chinese EV Makers Sell Carbon Credits to Porsche and Other Europe’s Auto Giants
Canada is exploring a new policy framework that could let Canadian companies participate in international carbon markets by trading internationally transferred mitigation outcomes (ITMOs).
The federal government announced the initiative on September 24, saying an ITMO framework could attract investment into Canadian climate projects, expand demand for carbon removal and nature-based solutions, and create new export opportunities for Canadian companies.
The move comes as international carbon markets develop under Article 6 of the Paris Agreement. At the same time, countries and companies are looking for ways to finance emissions reductions and carbon removals as they work toward net-zero targets.
For Canada, the opportunity is particularly significant because the country combines large natural resources, geological storage capacity, clean electricity and established expertise in energy and industrial infrastructure.
Canada’s Emissions Create a Large Decarbonization Challenge
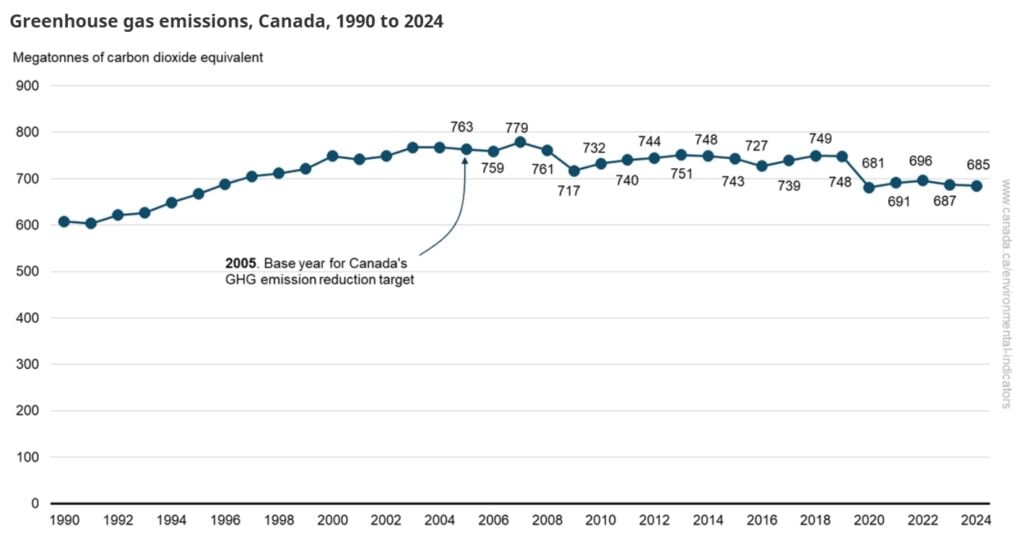
The country emitted about 685 million metric tons (Mt) of greenhouse gases in 2024, excluding emissions and removals from the land-use, land-use change and forestry sector. That was down 0.3% from 2023 and 10.3% below 2005 levels.
Oil and gas remained Canada’s largest source of emissions. The sector accounted for 208 Mt in 2024, although emissions have declined from their 2014 peak. Electricity emissions have fallen much more sharply, dropping 57% between 2005 and 2024 as Canada reduced coal-fired generation.
Canada’s government projects that emissions could fall to 600 Mt by 2030 under its “With Measures” scenario. Under a more ambitious “With Additional Measures” scenario, emissions could reach 546 Mt by 2030.
These figures show why Canada will need a combination of emissions reductions, carbon removal and other climate solutions to reach net zero.
An international market could provide another source of capital for some of those activities.
What Are ITMOs and Why Do They Matter?
ITMOs are internationally transferred mitigation outcomes created under Article 6.2 of the Paris Agreement.
In simple terms, one country can authorize the transfer of an emissions reduction or removal to another country under a cooperative approach. The receiving country can then use the mitigation outcome toward its climate target, subject to the applicable Article 6 accounting rules.
The system is designed to prevent the same emissions reduction from being counted toward the climate targets of both countries. This process, known as a corresponding adjustment, is central to maintaining the environmental integrity of international transfers.
Canada’s proposed framework would establish how these transfers could operate in the Canadian context.
The government said it will work with provinces and territories, Indigenous organizations and other stakeholders while developing the potential framework. It also said any ITMO trading would have to follow Article 6 rules, including requirements related to additionality, verification, permanence and avoiding double counting.
International Carbon Markets Are Expanding
Canada is considering the framework as carbon pricing and carbon-credit systems expand globally.
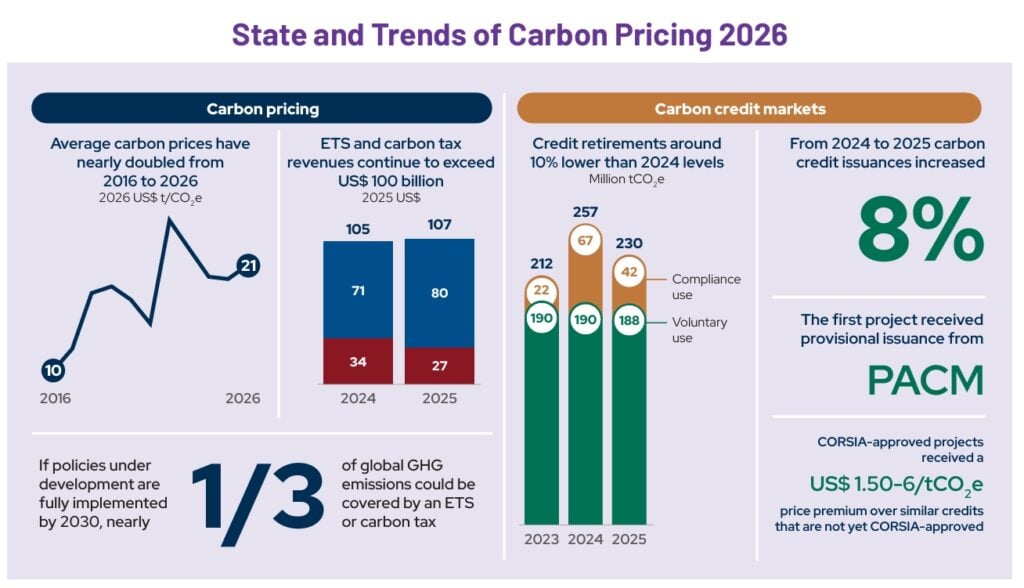
The World Bank’s 2026 State and Trends of Carbon Pricing report found that 87 carbon-pricing policies were operating worldwide, seven more than the previous year. Direct carbon pricing now covers nearly 30% of global greenhouse gas emissions, while carbon pricing generated more than $107 billion in public revenue in 2025.
The broader carbon-credit market is also attracting investment. The World Bank estimates that annual capital committed to future carbon-credit projects ranged from $12 billion to $16 billion in 2025.
The estimated annual value of traded carbon credits was about $535 million in 2024, although this figure covers a narrower segment of the overall carbon market than carbon taxes and emissions trading systems.
The growth opportunity extends beyond today’s market.
The World Bank’s international carbon-market research has highlighted the potential for carbon markets to mobilize climate finance, particularly where domestic public funding cannot cover the investment needed for emissions reductions and removals.
Other market research has projected that voluntary carbon-credit demand could grow several-fold by 2030, while the World Bank’s Emission Reduction Program has cited estimates of a $10 billion to $40 billion voluntary carbon market by 2030 under one industry scenario.
This expanding market could create opportunities for countries that can supply credible emissions reductions and carbon removals.
Canada Sees Carbon Removal as an Economic Opportunity
Carbon removal is one area where Canada could potentially benefit from international demand.
Its earlier modelling suggested that a Canadian industry capable of removing more than 300 Mt of CO₂ annually could create more than 330,000 jobs and add about $143 billion to GDP.
More recent modelling from the organization estimates that carbon removal could add $78 billion to Canada’s annual GDP by 2050 and create or support about 300,000 jobs.
Source: Carbon Removal Canada
Canada has several resources that could support this expansion. These include geological formations suitable for CO₂ storage, clean electricity, agricultural and forestry resources, industrial infrastructure and a workforce with experience in engineering, energy and large-scale construction.
Carbon removal technologies such as direct air capture and bioenergy with carbon capture and storage could therefore become part of Canada’s emerging clean-technology export industry.
ITMOs Could Bring More Capital Into Canadian Projects
The proposed ITMO framework could give developers another potential route to monetize verified emissions reductions and removals.
For example, a Canadian project could generate an eligible mitigation outcome, receive the required authorization, and transfer it internationally under an Article 6.2 agreement. Revenue from that transfer could help support project development and potentially improve the economics of technologies that remain expensive at early stages.
Nature-based projects could also benefit if they meet the requirements.
However, international transfers require more than simply creating a carbon credit. Countries need systems to authorize activities, track units, report transactions, and apply corresponding adjustments. These requirements are intended to ensure that a transferred mitigation outcome is not counted twice.
That accounting framework could also provide greater certainty for investors and buyers.
Canada Wants to Turn Climate Technology Into an Export Opportunity
The Honourable Julie Dabrusin, Minister of the Environment, Climate Change and Nature, said international ITMO trading could help Canadian companies attract capital and expand climate technologies.
She quoted:
“The trading of ITMOs under the Paris Agreement can unlock greater global climate action by making it easier to transfer emission reductions and removals between countries. This is about turning our natural advantages and homegrown climate innovation into investment, good jobs, and new export opportunities. A clear framework for international carbon credit transfers can help Canadian companies scale, attract capital, and bring more innovative technologies to market, strengthening our position as a leader in the global clean economy.”
$13 Billion in International Climate Finance
The government is also linking the initiative to more than $13 billion in international climate finance announced through the Spring Economic Update.
For Canada’s carbon market, the proposed framework could therefore represent more than a new trading mechanism. It could connect Canadian climate projects and technologies with international sources of demand and finance.
The framework is still under development, and its final rules will determine which projects and mitigation outcomes can participate. Canada will need to balance market access with rigorous accounting and environmental safeguards as it develops the system.
If implemented, the framework could give Canadian carbon removal developers, technology companies, and nature-based projects another potential pathway into the growing international market for emissions reductions and removals.
https://globalcarbonfund.com/wp-content/uploads/2018/10/GCF_header_logo_340x156.png00carbonfundhttps://globalcarbonfund.com/wp-content/uploads/2018/10/GCF_header_logo_340x156.pngcarbonfund2026-10-02 12:14:352026-10-02 12:14:35How Canada’s New ITMO Framework Could Unlock International Carbon Markets
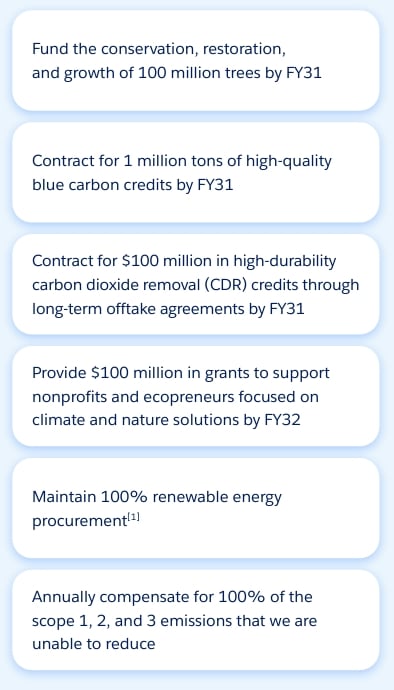
Salesforce is supporting new early-stage carbon dioxide removal (CDR) projects. The company aims to contract $100 million in durable carbon removal by 2030.
Through Milkywire, Salesforce has pre-purchased 3,661 tonnes of durable carbon removal from eight suppliers. This portfolio includes direct air capture (DAC), ocean alkalinity enhancement, and biomass storage. Projects are located in Europe, Canada, India, and the U.S.
The press release says these purchases follow a larger round announced in January, where Milkywire bought over 12,500 tonnes from 19 suppliers. That earlier portfolio featured biochar, BioCCS, enhanced rock weathering, mineralization, biomass storage, and next-generation DAC.
Therefore, the company is not only focusing on commercially available carbon removal. Instead, it uses Salesforce funding to support technologies that need testing and investment.
Salesforce Aims for Early-Stage Carbon Removal
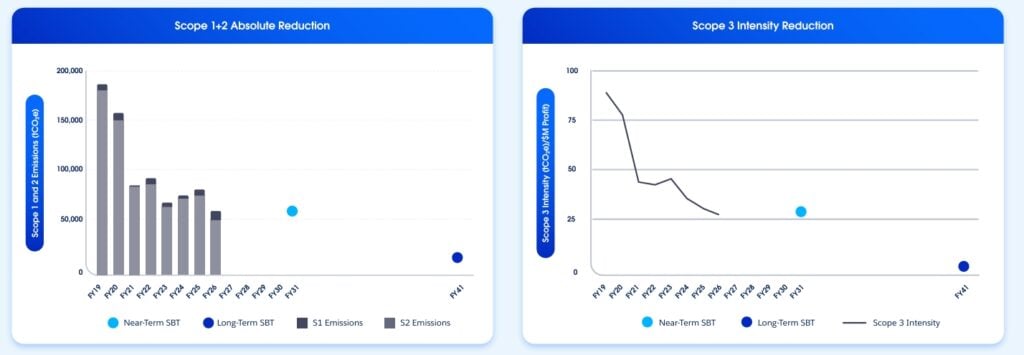
Salesforce plans to contract $100 million in high-durability CDR credits by fiscal 2031, aligning with 2030. The company started investing in early-stage CDR suppliers through partners like Milkywire and Frontier in FY25.
The strategy addresses a major challenge in the carbon removal market. Many new technologies require years of development before they can deliver large volumes of verified removals. Startups often struggle to get funding during this early stage.
Early purchases can provide revenue and help developers prove their technology.
Source: Salesforce
“Catalytic” Purchasing
Milkywire calls this approach “catalytic” purchasing. Instead of buying the most tonnes available, it targets projects where early funding can advance technology.
For Salesforce, these purchases fit into a broader climate strategy. The company plans to use durable carbon removal credits to offset its remaining emissions after reducing them across its value chain. It aims for durable carbon removals to equal 100% of its remaining Scope 1, 2, and 3 emissions by 2040.
Four of the eight purchases support direct air capture projects at various stages.
Sirona Technologies is developing a commercial DAC project that integrates a heat pump. The goal is to test if this can improve energy efficiency in DAC.
Yama operates France’s first DAC pilot and is creating a facility to remove 365 tonnes of CO₂ each year.
In the Netherlands, Brineworks combines electrochemical DAC with green hydrogen production. This method captures CO₂ while creating another low-carbon product.
Deep Sky in Canada is developing a DAC project that combines carbon capture with mineralization at Thetford Mines in Quebec. Mineralization stores CO₂ in solid forms for long-term storage.
These projects tackle the challenge of reducing energy use and costs in removing CO₂ directly from the atmosphere.
Ocean Carbon Removal Expands
The new portfolio also features two ocean alkalinity enhancement (OAE) projects.
OAE aims to boost the ocean’s capacity to absorb and store CO₂ by adding alkaline materials. This method is still emerging, with developers working to show its effectiveness and scalability.
PRONOE runs the EU’s first land-based OAE system linked to an industrial desalination plant.
In India, Alkamy Carbon is using wastewater treatment facilities in the Mumbai area to enhance alkalinity. This project should provide valuable data on wastewater-based alkalinity in tropical conditions.
The India project is crucial because carbon removal developers need more real-world data from diverse climates. This data helps researchers understand how these methods perform in different environments.
The last two purchases focus on storing biomass in durable forms.
Carba converts waste biomass into stable biocarbon before burying it in landfills. This process prevents carbon in organic waste from quickly re-entering the atmosphere.
Cowboy Clean Fuels injects agricultural residues into unmineable coal seams in Wyoming. Microorganisms underground convert the biomass into CO₂, which binds permanently to the coal.
These projects illustrate how durable carbon removal can involve various technologies and storage methods.
The eight purchases are:
Alkamy Carbon: 667 tonnes
Brineworks: 500 tonnes
Carba: 816 tonnes
Cowboy Clean Fuels: 500 tonnes
Deep Sky: 394 tonnes
PRONOE: 131 tonnes
Sirona Technologies: 390 tonnes
Yama: 263 tonnes
This totals 3,661 tonnes.
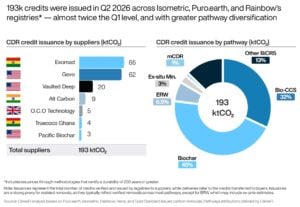
Credit Issuance
Source: ClimeFi CDR Market Report
Why Early Buyers Matter for the CDR Market
These latest purchases come as the carbon removal industry faces challenges.
While the sector has seen significant investment, many companies developing new technologies encounter high costs, long timelines, and limited demand.
Milkywire says the market needs buyers who will back technologies early on. Without early demand, promising projects might find it hard to secure funding. They may also struggle to transition from pilot stages to commercial operations.
This approach can also yield technical insights. A first-of-a-kind project may remove small amounts of CO₂, but its operation can provide data to improve performance and reduce costs.
Notably, Milkywire has enabled more than $12 million in carbon removal purchases. This includes over 45 projects in 20+ countries.
The latest portfolio spreads funding across multiple technologies instead of focusing on one method.
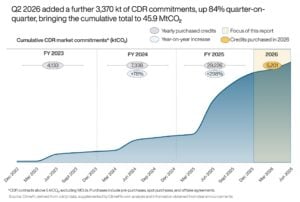
CDR Market Growth
Source: ClimeFi CDR Market Report
For Salesforce, these purchases further its long-term carbon removal strategy. The company announced its $100 million durable CDR commitment in 2022 as part of the First Movers Coalition.
As the CDR market grows, these early purchases could help identify which technologies move from pilot to commercial deployment. For developers, funding means early buyers. For the industry, these projects offer real-world data on effective pathways for durable carbon removal at scale.
https://globalcarbonfund.com/wp-content/uploads/2018/10/GCF_header_logo_340x156.png00carbonfundhttps://globalcarbonfund.com/wp-content/uploads/2018/10/GCF_header_logo_340x156.pngcarbonfund2026-10-01 12:14:252026-10-01 12:14:25Salesforce and Milkywire Back 3,661 Tons of Carbon Removal Across 8 Projects
Disseminated on behalf of Sierra Madre Gold & Silver Ltd.
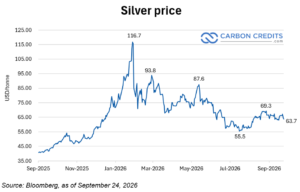
Silver has had a volatile 2026. It has pulled back sharply from its 2026 peak. The metal reached a 52-week high of about $115 per ounce in January before falling sharply during the year.
By mid-September, silver futures had dropped to about $63 per ounce, roughly 45% below that peak. Prices later recovered to around $66.70 by September 18.
That move highlights an important shift for silver producers. The market is no longer simply a story of rising prices. Producers now have to operate through a much wider price range while managing costs, production growth, and capital spending.
The decline has changed the operating backdrop for silver producers, but the underlying supply picture remains tight.
According to the World Silver Survey 2026, global silver mine production increased 3% in 2025 to 846.6 million ounces. Recycling added another 197.6 million ounces. Yet, total demand reached 1.13 billion ounces, leaving the market with a 40.3 million-ounce deficit, the fifth consecutive annual shortfall.
Metals Focus expects another deficit in 2026, estimated at 46.3 million ounces. That backdrop matters for Sierra Madre Gold & Silver as it moves from restarting one mine to building a larger production base.
The changing silver price environment, therefore, tests the company’s strategy: how does an operating producer manage growth when the commodity price can move sharply in either direction?
Silver’s 2026 Rally Gives Way to a Sharp Reset
Silver entered 2026 at elevated levels after a strong run in late 2025 and early 2026, but it significantly dropped this month. The decline was not driven by one factor alone.
Higher U.S. Treasury yields, a stronger dollar, and changing expectations for Federal Reserve policy have affected precious metals. Silver can also experience larger price swings than gold because it combines investment demand with industrial uses.
Recently, silver had recovered to over $66 per ounce. That rebound, however, does not erase the earlier decline. Instead, it shows why mining companies must plan around changing commodity prices rather than rely on a single price environment.
For Sierra Madre, that distinction matters because the company is already generating revenue from an operating mine.
La Guitarra Is Already Generating Silver Revenue
La Guitarra is no longer simply a development project. Sierra Madre restarted commercial production at the Mexican mine on January 1, 2025. The operation includes an underground mine and a processing plant that previously operated at 500 tonnes per day.
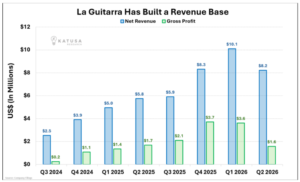
Moreover, the company reported 66,691 ounces of silver sold in Q2 2026, compared with 65,683 ounces in the same quarter of 2025.
The mine generated US$25 million of revenue and US$8.9 million of gross profit in 2025, its first full year back in production.
In the first half of 2026, La Guitarra generated another US$18.3 million of revenue and US$3.5 million of adjusted EBITDA. Sierra Madre also repaid its US$5 million First Majestic loan in July and ended June with US$22.2 million in cash and US$25 million in working capital.
The company received US$75.65 per silver-equivalent ounce sold in Q2 2026, compared with US$33.22 a year earlier.
Those figures show the effect that higher realized metal prices had on revenue. But they also highlight why future results cannot simply be extrapolated from the second quarter.
The spot and futures market has since moved below the $75.65 realized silver price reported for Q2. If lower prices persist, the company could face lower revenue per ounce even as production increases. That makes the production ramp-up increasingly important.
That higher realized price helped offset higher costs during a development-heavy quarter.
Sierra Madre reported all-in sustaining costs of US$54.73 per ounce produced, up from US$32.54 a year earlier. The company attributed the increase to development ore, lower recoveries, power outages, a stronger Mexican peso, and higher royalties.
The cost increase shows why the silver price pullback matters. Higher metal prices can support revenue and margins, but production growth can also bring temporary cost pressure.
Sierra Madre Pushes La Guitarra Toward Higher Throughput
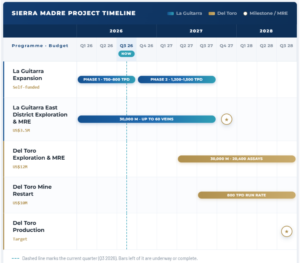
Sierra Madre is working to increase processing capacity at La Guitarra. The first phase is expected to bring capacity to about 750–800 tonnes per day, with the company expecting the expansion to come online before the end of Q3 2026.
A second phase is planned to increase capacity to 1,200–1,500 tonnes per day by Q3 2027.
Source: Sierra Madre Gold and Silver Ltd. corporate presentation,
The company reported that throughput had reached as high as 672 tonnes per day in August, as it continued to ramp up the operation. This timing matters.
Higher throughput can increase the number of ounces produced and sold, although the actual financial benefit will depend on factors including grades, recoveries, operating costs, capital requirements and the silver and gold prices received.
Sierra Madre reported Q2 2026 cash costs of $49.28 per silver-equivalent ounce produced, compared with $26.89 in Q2 2025. Its all-in sustaining cash cost was $54.73 per silver-equivalent ounce, versus $32.54 a year earlier.
The company said it expects higher production from the expansion, along with a reduction in costs as the operation scales up. That makes the next stage of the ramp-up particularly important in a lower-price environment.
Del Toro Adds Another Mexican Silver Asset
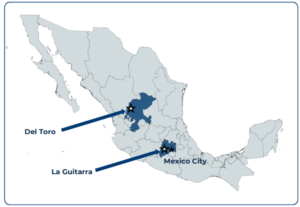
Sierra Madre added a second permitted silver mine to its portfolio in June 2026 with the acquisition of the Del Toro Silver Mine in Zacatecas, Mexico.
The company closed the deal with First Majestic Silver on June 22, 2026. First Majestic previously operated Del Toro from 2013 to 2019 and invested about US$175 million to build the operation.
The site includes three underground mines — San Juan, Perseverancia and Dolores — with more than 60 kilometres of underground development. It also has a 3,000-tonne-per-day flotation circuit and about 3,650 tpd of installed mill capacity.
Del Toro has a production history. It averaged 2.54 million silver-equivalent ounces per year from 2015 to 2018 under First Majestic.
Sierra Madre plans to restart the mine at a smaller scale. The company expects to spend about US$10 million initially, targeting 800 tpd, with a potential increase to 1,600 tpd. The restart is targeted for mid-2027, with production expected to begin in mid-2028.
Exploration will also be important. Sierra Madre has identified 23 deposits at Del Toro and plans about 30,000 metres of diamond drilling at a cost of roughly US$12 million.
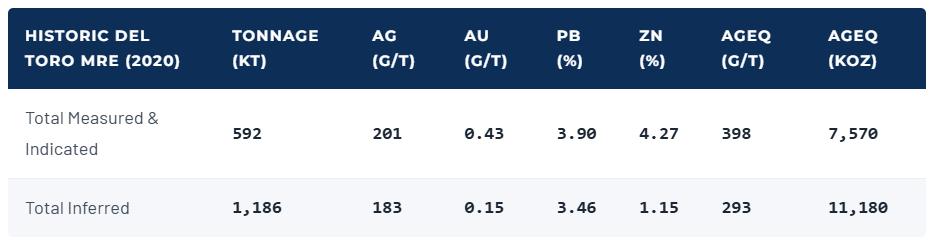
A 2020 historical estimate reported 7.57 million silver-equivalent ounces of measured and indicated material and 11.18 million ounces of inferred material. These figures are historical and are not current mineral resources.
Sierra Madre plans new drilling and resource modelling to establish an updated resource.
The acquisition gives the company another developed Mexican silver asset with existing infrastructure, past production and exploration upside, while the company continues expanding La Guitarra.
Mexico Matters to the Silver Supply Story
Del Toro also places Sierra Madre in one of the world’s most important silver-producing countries.
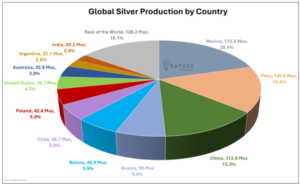
Mexico produced 172.9 million ounces of silver in 2025, down 5% from 181.1 million ounces in 2024. Still, it remained the world’s largest silver-producing country and accounted for about 20% of global mine supply.
That makes Mexico an important part of the global supply story, while Zacatecas itself has a long history of silver production.
The Katusa Research report notes that roughly half of global silver production comes from Latin America, with Mexico accounting for about one-fifth of global output.
Sierra Madre’s strategy therefore combines existing Mexican infrastructure with a market where new supply remains difficult to bring online quickly.
Lower Silver Prices Put More Focus on Mine Execution
The silver pullback changes the economics of new production, even if the longer-term supply deficit remains. For Sierra Madre, the key issue is no longer simply whether silver prices are rising. The company now has to execute two different stages of growth.
La Guitarra needs to increase throughput while bringing costs under control. Del Toro needs to move through drilling, resource definition, mine planning, and restart work before it can contribute production.
The company is therefore entering a more demanding phase. The next stage of Sierra Madre’s story will depend on how efficiently it converts existing infrastructure, resources, and permits into production.
For now, La Guitarra provides an operating base while Del Toro offers a second potential source of growth. The silver price has pulled back, but Sierra Madre’s production strategy is moving forward.
DISCLAIMER New Era Publishing Inc. and/or CarbonCredits.com (“We” or “Us”) are not securities dealers or brokers, investment advisers, or financial advisers, and you should not rely on the information herein as investment advice. Sierra Madre Gold and Silver Ltd. (“Company”) made a one-time payment of $25,000 to provide marketing services for a term of one month. None of the owners, members, directors, or employees of New Era Publishing Inc. and/or CarbonCredits.com currently hold, or have any beneficial ownership in, any shares, stocks, or options of the companies mentioned.
This article is informational only and is solely for use by prospective investors in determining whether to seek additional information. It does not constitute an offer to sell or a solicitation of an offer to buy any securities. Examples that we provide of share price increases pertaining to a particular issuer from one referenced date to another represent arbitrarily chosen time periods and are no indication whatsoever of future stock prices for that issuer and are of no predictive value.
Our stock profiles are intended to highlight certain companies for your further investigation; they are not stock recommendations or an offer or sale of the referenced securities. The securities issued by the companies we profile should be considered high-risk; if you do invest despite these warnings, you may lose your entire investment. Please do your own research before investing, including reviewing the companies’ SEDAR+ and SEC filings, press releases, and risk disclosures.
It is our policy that information contained in this profile was provided by the company, extracted from SEDAR+ and SEC filings, company websites, and other publicly available sources. We believe the sources and information are accurate and reliable but we cannot guarantee them.
CAUTIONARY STATEMENT AND FORWARD-LOOKING INFORMATION
Certain statements contained in this news release may constitute “forward-looking information” within the meaning of applicable securities laws. Forward-looking information generally can be identified by words such as “anticipate,” “expect,” “estimate,” “forecast,” “plan,” and similar expressions suggesting future outcomes or events. Forward-looking information is based on current expectations of management; however, it is subject to known and unknown risks, uncertainties, and other factors that may cause actual results to differ materially from those anticipated.
These factors include, without limitation, statements relating to the Company’s exploration and development plans, the potential of its mineral projects, financing activities, regulatory approvals, market conditions, and future objectives. Forward-looking information involves numerous risks and uncertainties and actual results might differ materially from results suggested in any forward-looking information. These risks and uncertainties include, among other things, market volatility, the state of financial markets for the Company’s securities, fluctuations in commodity prices, operational challenges, and changes in business plans.
Forward-looking information is based on several key expectations and assumptions, including, without limitation, that the Company will continue with its stated business objectives and will be able to raise additional capital as required. Although management of the Company has attempted to identify important factors that could cause actual results to differ materially, there may be other factors that cause results not to be as anticipated, estimated, or intended.
There can be no assurance that such forward-looking information will prove to be accurate, as actual results and future events could differ materially. Accordingly, readers should not place undue reliance on forward-looking information. Additional information about risks and uncertainties is contained in the Company’s management’s discussion and analysis and annual information form for the year ended December 31, 2025, copies of which are available on SEDAR+ at www.sedarplus.ca.
The forward-looking information contained herein is expressly qualified in its entirety by this cautionary statement. Forward-looking information reflects management’s current beliefs and is based on information currently available to the Company. The forward-looking information is made as of the date of this news release, and the Company assumes no obligation to update or revise such information to reflect new events or circumstances except as may be required by applicable law.
For more information on the Company, investors should review the Company’s continuous disclosure filings available on SEDAR+ at www.sedarplus.ca.
Disclosure: Owners, members, directors, and employees of carboncredits.com have/may have stock or option positions in any of the companies mentioned: None.
Carboncredits.com receives compensation for this publication and has a business relationship with any company whose stock(s) is/are mentioned in this article.
Additional disclosure: This communication serves the sole purpose of adding value to the research process and is for information only. Please do your own due diligence. Every investment in securities mentioned in publications of carboncredits.com involves risks that could lead to a total loss of the invested capital.
https://globalcarbonfund.com/wp-content/uploads/2018/10/GCF_header_logo_340x156.png00carbonfundhttps://globalcarbonfund.com/wp-content/uploads/2018/10/GCF_header_logo_340x156.pngcarbonfund2026-10-01 10:14:282026-10-01 10:14:28Silver Falls 45% From Its 2026 Peak as Sierra Madre Scales Up Production