US Biofuel Credit Market Faces Major Shake-Up From EPA Exemptions

us biofuel

Reuters reported that prices for U.S. ethanol blending credits plunged on Monday after the Environmental Protection Agency (EPA) extended a key compliance deadline and said it would rule on long-pending small refinery exemption requests by the end of August.

The move sent a shock through the U.S. biofuel credit market. Conventional ethanol Renewable Identification Numbers (D6 RINs) fell to $1.75 each, down 34 cents from Friday and their lowest level since April 15, according to Argus Media. The credits had traded as high as $2.50 on July 7.

Prices for 2026 biomass-based diesel RINs also weakened. They were last assessed at around $1.92 each, their lowest level since late April.

The sharp decline shows how closely the U.S. biofuel market depends on federal blending rules and the supply of compliance credits.

us biofuel market

What Are RINs and Why Do They Matter?

Renewable Identification Numbers, or RINs, are tradable credits created under the U.S. Renewable Fuel Standard (RFS).

The RFS requires obligated fuel companies, mainly refiners and importers, to demonstrate that they have met federal renewable fuel blending requirements. Companies can generate RINs by blending eligible biofuels into the fuel supply or buy credits from other market participants.

RINs therefore create a financial value around renewable fuel use.

When refiners need more credits than they can generate through their own blending activities, they must buy RINs. Higher compliance obligations or tighter credit supplies can push prices higher.

The opposite can also happen.

If the EPA grants exemptions that reduce the number of RINs refiners need, the market can suddenly have more credits available. That is what traders are now anticipating.

US Biofuel Market Remains Large

The United States is the world’s largest producer and consumer of fuel ethanol and one of the biggest markets for biodiesel and renewable diesel.

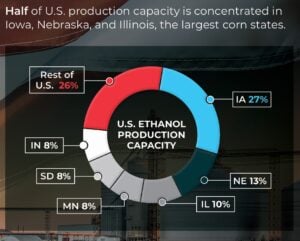
us ethanol
Source: ethanolrfa.org

Corn-based ethanol dominates the U.S. biofuel market. Most gasoline sold in the country contains some ethanol, with E10, a blend containing about 10% ethanol, forming the backbone of the market.

Higher ethanol blends such as E15 and E85 also contribute to demand, although their use remains much smaller.

The U.S. ethanol industry produces billions of gallons of fuel each year. That creates a large and established market for corn, ethanol production, transportation, blending and RIN generation.

The diesel side of the market has also expanded. Biodiesel and renewable diesel provide another major source of renewable fuel and compliance credits.

Renewable diesel is particularly important because it can be used in existing diesel infrastructure and is increasingly produced from feedstocks such as vegetable oils, animal fats and used cooking oil.

Demand for Biofuel Credits Is Driven by Federal Rules

The biggest source of demand for RINs is not simply fuel consumption. It is the federal compliance system.

Each year, the EPA establishes Renewable Volume Obligations (RVOs) that determine how much renewable fuel the market must account for.

Refiners and fuel importers receive obligations based on their share of the U.S. transportation fuel market. They then need enough RINs to demonstrate compliance.

That makes RIN demand closely tied to EPA policy.

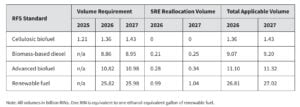
The EPA recently finalized record-high renewable fuel blending requirements for 2026 and 2027. Those requirements have increased compliance pressure on refiners and helped support RIN prices.

But the market is now facing a potential reversal.

biofuel renewable fuel EPA
Source: EPA

EPA Exemptions Could Add Billions of Credits

The EPA is reviewing 34 small refinery exemption petitions, with some dating back to July 2024.

Small refinery exemptions allow qualifying facilities to receive relief from their renewable fuel obligations when they can demonstrate that compliance would impose disproportionate economic hardship.

The market expects the EPA’s decisions to free up a significant number of RINs.

Representatives from the refining and ethanol industries, along with an analyst, estimate that the exemptions could free between 1.2 billion and 1.8 billion RINs for small refiners to use toward their 2025 compliance obligations.

The EPA had previously indicated that it could reallocate about 990 million RINs associated with exemptions. This potential supply is large enough to materially change the balance between RIN supply and demand.

Why RIN Prices Fell So Quickly

The selloff is largely about expectations.

Jessica Dell, head of U.S. biofuel pricing at Argus Media, said RIN prices lost substantial value during Monday’s session as the market reacted to the pending exemption decisions.

RIN prices had already fallen 5% on Friday. The EPA’s decision to extend the September 1 compliance deadline has added another layer of uncertainty.

Under the RFS, refiners must show that they met their 2025 biofuel blending obligations by September 1. They can do this by generating RINs through renewable fuel blending or purchasing credits from other market participants.

Giving refiners more time to comply could reduce immediate buying pressure.

More importantly, the deadline extension has been interpreted by some market participants as a possible signal that refiners could receive broader relief from their 2026 and 2027 obligations.

Agricultural economist Scott Irwin of the University of Illinois described the move as potentially signaling some form of “RIN relief” for future obligations.

Ethanol Producers Face a Different Equation

Lower RIN prices are not necessarily positive for the ethanol industry. Ethanol producers can generate RINs when they blend their fuel into the transportation system. Those credits provide an additional source of revenue.

When RIN prices fall, the value of that revenue stream also declines.

That can put pressure on producer margins, particularly when corn prices, energy costs, transportation expenses or other operating costs are high. Furthermore, the impact can vary across producers because ethanol economics depend on several factors, including corn prices, ethanol selling prices, distillers grains revenue and energy costs.

Still, the RIN market remains an important part of the broader economics of U.S. ethanol production.

Supply Could Become the Market’s Biggest Concern

The immediate question is how many credits will become available if the EPA grants the pending exemptions.

  • A release of 1.2 billion to 1.8 billion RINs would represent a significant addition to the pool of credits available for compliance. This could create a supply overhang and keep prices under pressure.

It could also reduce the incentive for some refiners to purchase additional credits in the spot market.

For the ethanol industry, this creates a difficult environment. Demand for renewable fuel may remain strong, but the value of the compliance credits attached to that fuel can fall when regulatory relief increases RIN availability.

What Happens Next?

The EPA’s decisions on the 34 exemption petitions will be the next major catalyst for the market. If the agency grants a large number of exemptions, RIN prices could face additional pressure as more credits become available or obligations are reduced.

On the other hand, if fewer exemptions are granted, the market could tighten again, particularly given the record renewable fuel requirements for 2026 and 2027.

The outcome will also influence the economics of U.S. refiners and biofuel producers.

For refiners, lower RIN prices can reduce the cost of meeting federal obligations. For ethanol and renewable diesel producers, however, weaker credit prices can reduce the value of an important revenue stream.

The episode highlights a central feature of the U.S. biofuel market: fuel demand, government mandates and carbon-related compliance markets are closely connected.

The U.S. can continue consuming large volumes of ethanol, biodiesel and renewable diesel while RIN prices fall sharply if regulatory changes increase credit supply.

For carbon and clean energy investors, the RIN market is therefore worth watching alongside traditional biofuel production data. Changes in EPA policy can quickly reshape the economics of renewable fuels, alter demand for compliance credits and influence investment decisions across the U.S. bioenergy sector.

The post US Biofuel Credit Market Faces Major Shake-Up From EPA Exemptions appeared first on Carbon Credits.
Alberta Carbon Price Barely Raises Oil Sands Costs, Study Finds

Alberta Carbon Price Barely Raises Oil Sands Costs, Study Finds

Alberta’s industrial carbon price has had only a small effect on the cost of producing oil sands crude, according to a new study from the C.D. Howe Institute.

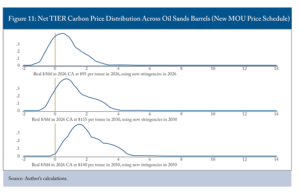
The report, published by economist G. Kent Fellows, finds that Alberta’s Technology Innovation and Emissions Reduction (TIER) system added an average of just C$0.70 per barrel to oil sands marginal production costs in 2023. On a production-weighted basis, the increase was even smaller at C$0.34 per barrel.

The findings come as Canada and Alberta prepare to raise the industrial carbon price over the next decade. Under their May 2026 agreement, Alberta’s headline TIER price will rise from C$95 per tonne in 2026 to C$115 in 2030, C$130 in 2035 and C$140 in 2040.

Despite those higher headline prices, the study finds that most oil sands projects should continue to face relatively modest carbon costs.

Carbon Price, Small Cost: Oil Sands Barely Feel the Heat

The C.D. Howe analysis uses project-level production and emissions data to estimate how TIER affects the marginal cost of producing oil sands crude.

In 2023, the system’s impact ranged from an effective C$1.09-per-barrel reduction in marginal costs at the low end to an additional C$4.05 per barrel at the high end. The negative figures represent an effective benefit under TIER because some facilities performed better than their emissions benchmarks and received more credits than they needed.

The average facility saw a C$0.70-per-barrel increase. But larger facilities generally performed better against their emissions targets, bringing the production-weighted average down to C$0.34 per barrel.

Alberta TIER carbon price oil sands 2023
Source: G. Kent Fellows. 2026. Buckets of Oil and Barrels of Steam: Quantifying Carbon Pricing’s Impact in Alberta’s Oil Sands. Toronto: C.D. Howe Institute.

That is small compared with oil sands operating costs. The study says 99% of operators have operating costs between C$21 and C$65 per barrel.

Some major projects, including Horizon Mine, Jackpine Mine, Muskeg River Mine, Kearl and Peace River, actually received a net benefit from TIER on a per-barrel basis.

Why the Headline Carbon Price Is Misleading

The study highlights an important difference between Alberta’s headline carbon price and the actual cost many oil sands facilities face. Under TIER, large industrial emitters do not simply pay the full carbon price on every tonne of emissions. The system uses emissions benchmarks and performance credits.

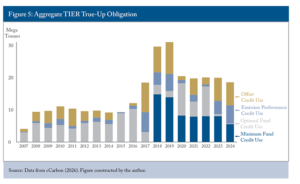
Facilities must also use fund contributions to meet a minimum portion of their true-up obligation, reducing from 40% in 2023 to 10% in 2026 and beyond. Data from 2023 and 2024 show facilities met only the minimum requirement, opting for cheaper market credits over higher-cost TIER fund contributions.

Alberta TIER true up obligations
Source: G. Kent Fellows. 2026. Buckets of Oil and Barrels of Steam: Quantifying Carbon Pricing’s Impact in Alberta’s Oil Sands. Toronto: C.D. Howe Institute.

Moreover, facilities that perform better than their benchmark can generate credits. Facilities that perform worse must acquire credits or otherwise meet their compliance obligations.

This means the headline price can rise substantially without creating the same increase in average production costs. That distinction becomes even more important under the new Canada-Alberta agreement.

The headline TIER price will reach C$140 per tonne by 2040, but Canada and Alberta have agreed to target an effective carbon price of C$130 per tonne. Alberta will also introduce a minimum transfer price for TIER credits beginning in 2030. That floor starts at C$60 per tonne in 2030 and rises to C$110 by 2040.

The government says the changes are designed to make Alberta’s industrial carbon market more stable and predictable.

Costs Stay Below C$5 Per Barrel Through 2050

The most important finding for the oil sands is that higher future carbon prices do not translate into extremely high per-barrel costs under the new system.

Fellows projects that no oil sands facility analyzed would face carbon pricing costs above C$5 per barrel through 2050 under the updated Canada-Alberta pricing and emissions-intensity schedules.

The study also says the estimates intentionally use assumptions that overstate carbon pricing costs. The results should therefore be viewed as an upper bound rather than a forecast of what companies will actually pay.

  • Under the new policy, most projects are expected to remain well below the C$5-per-barrel level.
TIER carbon price under new MOU
Source: G. Kent Fellows. 2026. Buckets of Oil and Barrels of Steam: Quantifying Carbon Pricing’s Impact in Alberta’s Oil Sands. Toronto: C.D. Howe Institute.

That matters because oil sands producers sell into global markets. Their carbon costs may affect profitability, but individual producers generally cannot set the global price of crude.

Cheap to Pay, Harder to Decarbonize

The relatively small cost does not mean the oil sands have a small climate impact.

Canada’s oil and gas sector produced 208 million tonnes of pollution in 2024. This was the country’s top source of greenhouse gases, making up 30% of national emissions. These sector emissions were 1.8% higher than the year before and 76% higher than in 1990.

However, newer data shows that the industry is starting to break the link between rising oil production and rising pollution. According to a June 2026 report from S&P Global Energy, absolute greenhouse gas emissions from Canadian oil sands rose by only 2% between 2024 and 2025, reaching an estimated 89 million tonnes.

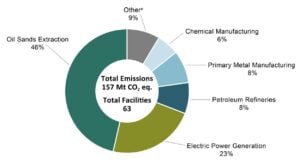
Despite these efficiency gains, oil sands operations still account for a huge chunk of Canada’s heaviest industrial footprints. In the latest federal registry, 63 individual facilities reported over 1 million tonnes of emissions each. Together, they accounted for 157 million tonnes (or 54%) of all emissions tracked under Canada’s federal reporting framework.

oil sands emissions share in Canada 2024
Source: Environment and Climate Change Canada (ECCC)

If carbon pricing adds only a small amount to production costs, will it be strong enough to push companies toward major emissions cuts? The answer depends partly on how companies respond to the financial signal.

Carbon Price Is Designed to Drive Investment

Carbon pricing is not intended only to increase operating costs. TIER also creates incentives for companies to invest in lower-emissions technologies and earn credits by improving their performance.

The new Canada-Alberta agreement reinforces that approach. The two governments plan to jointly support 75 million tonnes of emissions reductions through Carbon Contracts for Difference (CCfD), with costs shared equally. These contracts are designed to give companies more certainty about the future value of emissions reductions.

The agreement also sets annual tightening rates for oil sands emissions benchmarks. For large oil sands facilities, the rate is 2% annually from 2027 through 2040. Small oil sands facilities face a 1.5% rate from 2027 to 2030 and 1% from 2031 to 2040.

Those tightening rules could become more important than the headline carbon price itself. As benchmarks become stricter, companies may need to invest more in emissions reduction projects to avoid higher compliance costs.

Carbon Capture Could Change the Equation

The oil sands industry’s biggest proposed emissions reduction project is the Pathways Project, a carbon capture, utilization and storage network backed by major producers.

The May 2026 Canada-Alberta agreement sets a goal of 16 million tonnes per year of emissions reductions from Pathways projects. That includes at least 6 million tonnes per year of CCUS reductions by 2035, another 5 million tonnes by 2040 and a further 5 million tonnes by 2045.

The project is important because carbon capture could allow oil sands producers to reduce emissions without cutting production. Recent industry plans, however, remain under development.

Oil sands companies are targeting a final investment decision in late 2027 or early 2028 for the proposed first phase, according to the Oil Sands Alliance. The project’s cost and the structure of government support remain key issues.

The Real Test: Can a Small Cost Deliver Big Emissions Cuts?

Alberta’s experience shows why the headline carbon price alone does not tell the full story. The province will raise its TIER headline price from C$95 per tonne in 2026 to C$140 in 2040, yet the C.D. Howe study estimates that most oil sands facilities will continue to face carbon costs below C$5 per barrel.

That could make the system easier for producers to absorb. However, it also raises questions about whether the financial signal is strong enough to drive major emissions cuts. The answer will depend on what companies do with the policy incentives.

If producers use TIER credits and carbon contracts to fund carbon capture, efficiency improvements, and other lower-emissions technologies, the system could support both oil production and emissions reductions.

For Alberta, the bigger test is therefore not whether carbon pricing hurts oil sands profits. It is whether the system can turn a relatively modest cost into meaningful emissions cuts.

The post Alberta Carbon Price Barely Raises Oil Sands Costs, Study Finds appeared first on Carbon Credits.
ExxonMobil Hit as Germany Revokes 2.1 Million Carbon Credits From Chinese Projects

ExxonMobil Hit as Germany Revokes 2.1 Million Carbon Credits From Chinese Projects

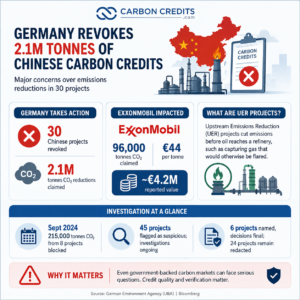
Germany has revoked carbon credits linked to 30 projects in China after authorities found serious concerns about the emissions reductions they claimed to deliver. The action has also affected ExxonMobil, which bought credits from one of the projects now under scrutiny.

The projects claimed a combined 2.1 million tonnes of CO2 reductions. One project backed by an ExxonMobil unit claimed nearly 96,000 tonnes of reductions, with the credits priced at about €44 per tonne. That puts the reported value at roughly €4.2 million.

The case highlights a wider problem for carbon credit markets. Even credits used in a government-backed compliance system can face questions over whether the promised emissions cuts actually happened.

Germany Finds Problems With Chinese Carbon Projects

The revoked credits came from upstream emissions reduction (UER) projects. These projects aim to cut emissions before crude oil reaches a refinery, such as by capturing gas that would otherwise be flared during oil production.

Germany allowed companies to use UER certificates to help meet their fuel emissions obligations. The system attracted interest because it offered a relatively low-cost way to reduce reported emissions.

However, German authorities began finding serious problems in several projects.

In September 2024, the German Environment Agency (UBA) announced it blocked certificates for 215,000 tonnes of CO2 from eight projects. Seven project applications were withdrawn after UBA identified serious legal and technical inconsistencies. In another Chinese project, UBA rejected certificates after finding that the project had started too early.

The agency also said it was investigating additional projects and had asked project operators to allow on-site inspections. The latest action goes much further, with authorities withdrawing credits from 30 Chinese projects.

ExxonMobil’s 96,000 Tonnes of Credits Under the Microscope

A Belgian ExxonMobil entity supported one of the projects, as stated in a German Environment Agency report, per a Bloomberg report. The project claimed to reduce nearly 96,000 tonnes of CO2. The credits sold for about €44 per tonne, putting their reported value at approximately €4.2 million.

ExxonMobil told Bloomberg that it operates in line with legal requirements and generally does not comment on ongoing investigations. The company’s involvement does not mean the oil giant has been accused of creating false emissions reductions itself.

The German investigation focuses on the projects and the claims behind the credits. This distinction is crucial. Companies can purchase credits in good faith and still face losses if authorities later invalidate them.

30 Projects, 2.1M Tonnes and Growing Questions

The 30 projects together claimed about 2.1 million tonnes of emissions reductions. That is roughly equivalent to the annual emissions from 500,000 cars, according to reporting on the German findings.

The investigation originally identified 45 projects as suspicious. Authorities have now withdrawn credits from 30 of them. However, the full picture is still developing.

Germany’s report names only six projects, while information on 24 projects remains redacted because investigations are still underway. The revocation decisions for the six named projects are final, according to Bloomberg’s reporting. This means it would be too early to describe every project in the wider investigation as fraudulent.

German authorities found enough issues to revoke credits from 30 projects. They are still investigating other cases.

Germany carbon credits Exxonmobil

Beijing Karbon Faces Scrutiny

The investigation also points to Beijing Karbon, a Chinese consultancy involved in many of the projects. According to the German report, Beijing Karbon was the main developer behind the 45 projects under investigation.

The report alleges that the company created the appearance of legitimate UER projects through deception. The case also raises questions about third-party verification.

Bloomberg reported that European auditing firms, like TÜV Rheinland, Müller-BBM Cert, and Verico SCE, checked some of the projects. This creates a bigger concern for carbon markets. Verification should offer an independent check that a project has achieved its claimed emissions reductions.

  • If questionable projects get through many layers of development and checks, buyers may struggle to assess credit quality.

Germany Tightens the Rules After the Credit Scandal

The scandal has already changed Germany’s approach to these credits. In 2024, UBA found that remote checks, satellite images, and document reviews often didn’t fully catch misuse. The agency brought in an international law firm to support its investigations in China.

The agency also said it would continue reviewing other critical UER projects worldwide.

The German government has since moved to end the use of UER certificates for the country’s fuel emissions quota. Under the updated rules, recognition of these certificates was allowed only through 2025. That makes the current revocations part of a broader shift away from the system.

For carbon market participants, the episode shows how quickly regulatory decisions can change the value of credits that once qualified for compliance.

When a Carbon Credit Loses Its Climate Value

Carbon credits only have environmental value if they represent real emissions reductions. A company can use a credit to claim that one tonne of emissions was reduced, avoided or removed elsewhere. But if the underlying project did not deliver that reduction, the climate benefit disappears.

That creates a serious problem for buyers.

A credit may pass project reviews, receive third-party verification and enter a regulated market. Years later, a regulator can still discover problems and withdraw it.

Germany’s action shows that regulatory approval is not necessarily a permanent guarantee of credit quality. It shows why strong monitoring and on-site checks are important. This is especially true for projects in countries or sectors with limited oversight from authorities.

Invalid Credits Can Leave Buyers With a Bigger Bill

The financial impact extends beyond the original purchase price. When authorities revoke credits used for compliance, companies may need to obtain replacement units to meet their emissions obligations.

That can create an additional cost if valid credits are more expensive than the original ones.

For ExxonMobil, the reported €4.2 million value of the affected project provides a measure of the potential exposure tied to that one project. The overall financial impact depends on how many credits the company bought, used, or held. It also depends on the replacement obligations that apply.

The issue is therefore larger than the value of one transaction. Credit quality risk can turn into a financial risk for companies relying on carbon markets to meet regulations.

A Warning for the Wider Carbon Market

Germany’s move tests carbon market integrity. This comes as governments boost carbon pricing and international emissions trading.

The EU’s Emissions Trading System (ETS) covers more than 10,000 installations across the power, industrial and aviation sectors. Since 2005, it has helped reduce emissions from covered installations by about 50%, says the European Environment Agency.

That progress depends partly on confidence in the rules and measurement systems behind carbon markets. The ExxonMobil case shows what can happen when that confidence breaks down.

For project developers, stronger monitoring and verification will become increasingly important. For buyers, the episode is a reminder to look beyond the price and label attached to a credit.

And for regulators, it shows that removing questionable credits after they enter the market is not enough. Stronger checks are needed before credits reach buyers in the first place.

Germany’s investigation is still developing, with 24 of the 30 projects remaining under investigation. Still, the revocations already send a clear message: carbon credits must represent real emissions reductions, or their market value can disappear.

The post ExxonMobil Hit as Germany Revokes 2.1 Million Carbon Credits From Chinese Projects appeared first on Carbon Credits.
Oman Turns Landfill Methane Into Carbon Credits and Clean Energy

Oman Turns Landfill Methane Into Carbon Credits and Clean Energy

Oman is turning a major waste problem into a potential carbon market opportunity. Oman Environmental Services Holding Company (be’ah) is expanding its work to capture landfill gas and develop carbon credits from the resulting emissions reductions. The state-owned waste-management company is also moving beyond simply burning the gas and plans to use recovered methane to generate electricity.

The effort focuses on the Al Multaqa and Barka landfills, where be’ah has already registered landfill gas recovery projects under Verra’s Verified Carbon Standard (VCS). The strategy could give Oman another way to cut methane emissions while creating potential revenue from carbon markets.

Landfill Methane Is Oman’s Major Emissions Source

Landfills are central to be’ah’s climate strategy because they produce large amounts of methane as organic waste breaks down.

Methane is a powerful greenhouse gas. Capturing it before it reaches the atmosphere can therefore create significant emissions reductions.

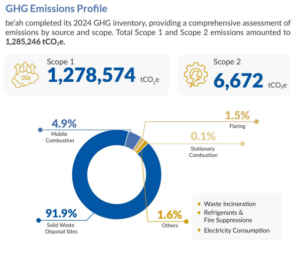
be’ah’s 2024 GHG inventory shows how important this issue is. The company reported 1.285 million tonnes of CO2e in combined Scope 1 and Scope 2 emissions. Scope 1 accounted for 1.279 million tonnes, while Scope 2 emissions stood at 6,672 tonnes.

Solid waste disposal sites produced 91.9% of be’ah’s Scope 1 emissions. Mobile combustion, mainly from the municipal waste-collection fleet, contributed another 4.9%, while flaring accounted for 1.5%. That makes landfill methane the clearest target for emissions reductions.

be'ah 2024 ghg emissions profile
Source: be’ah 2025 Sustainability Report

Two Landfills Already Generate Carbon Credits

be’ah’s carbon credit program centers on the Al Multaqa and Barka landfill gas recovery projects. Moosa Al Aamri,
Landfill Operations Engineer at be’ah, remarked:

“The certification of carbon credits for Barka and Al Multaqa landfills marks a significant milestone in Oman’s waste management journey. Through landfill gas capture and greenhouse gas reduction, be’ah has transformed these sites into benchmarks of environmental responsibility and innovation. This achievement aligns with Oman Vision 2040’s goals of sustainability and economic diversification, underscoring the critical role of modern waste management in tackling global climate challenges.”

The projects were registered under Verra’s VCS in 2024 as Project #4544 for Al Multaqa and Project #4550 for Barka. Al Multaqa received credits for 2021 and 2022, while Barka received credits for 2022.

By May 2025, be’ah reported that the two projects had generated a combined 67,700 VCUs. Al Multaqa accounted for about 39,000 credits, while Barka generated about 28,700. One VCU represents one metric tonne of CO2e reduced or removed under the VCS.

The projects were developed with support from OQ Trading (OQT), which helps identify carbon credit opportunities and supports project development, certification, verification, and marketing.

This gives be’ah a potential new source of revenue while supporting its emissions reduction work.

Oman Wants to Turn Methane Into Power, Not Just Flare It

The next stage goes beyond carbon credits. be’ah is developing projects to capture landfill gas and turn it into electricity. The projects began in January 2025 and were scheduled for completion in July 2026. By the end of 2025, overall progress had reached about 55%, according to be’ah’s 2025 Annual Report.

At Al Multaqa, the existing flaring system has a capacity of 2,000 normal cubic meters per hour (Nm³/hr). The site has estimated recoverable landfill gas of about 430 Nm³/hr and potential electricity generation of around 460 kilowatts (kW).

At Barka, the flaring system has a capacity of 2,500 Nm³/hr. Estimated recoverable gas is about 530 Nm³/hr, with potential electricity generation of around 600 kW. Together, the two sites could therefore produce about 1.06 MW of electricity at the estimated recovery levels.

be’ah plans to use the electricity at the landfill sites. At full recovery capacity, it could also potentially export power.

be'ah at a glance carbon emissions
Source: be’ah 2025 Sustainability Report

One Waste Stream, Three Climate Benefits

Using landfill gas for electricity can create more than one environmental benefit.

  • First, capturing methane prevents some of it from escaping into the atmosphere.
  • Second, using the gas for power can reduce the need for electricity from other sources.
  • Third, the emissions reductions can support carbon credit generation when projects meet the required standards.

Oman’s own climate reporting also identifies landfill gas recovery as an important mitigation measure.

In its first Biennial Transparency Report submitted to the UN Framework Convention on Climate Change, Oman listed landfill methane recovery for direct use and electricity generation among its waste-sector mitigation initiatives. The report estimated average annual emissions reductions of 113,864 tonnes of CO2e for direct methane use at Al Multaqa and 303,542 tonnes of CO2e for electricity generation at Barka and Al Multaqa.

These are estimated mitigation potentials, not verified carbon credits. That distinction is important. Actual credits depend on project monitoring, verification, methodology requirements, and issuance under the relevant carbon standard.

be’ah Builds a Wider Carbon Management System

The landfill projects form part of a broader carbon management plan. be’ah has created a Carbon Management Framework covering five stages:

  • Carbon accounting,
  • Identifying emissions-reduction projects,
  • Carbon credit registration and verification,
  • Issuing and selling or retiring credits, and
  • Integrating carbon activity into financial management.

This approach could help be’ah identify more carbon projects across its waste operations. The company has already said it is exploring other opportunities in waste management and waste-to-energy. Its earlier sustainability reporting also identified possible projects involving other landfill cells and the use of captured gas.

The strategy fits Oman’s wider Vision 2040 goals, which include economic diversification, environmental protection and more sustainable resource use.

Oman 2040 vision goals
Source: Climate Change Laws of the World

More Waste Could Mean More Methane and More Carbon Projects

The need for better landfill management is also increasing as waste volumes rise. be’ah reported that Oman received 2.88 million tonnes of municipal solid waste in 2025, up from 2.57 million tonnes in 2024. Industrial waste intake also increased sharply to 43,216 tonnes, from 12,649 tonnes a year earlier.

  • be’ah commissioned about 2.2 million tonnes of new engineered landfill capacity during 2025 and is developing another 3.4 million tonnes at Thumrait.

More waste means more landfill gas over time. That makes methane capture increasingly important if Oman wants to limit emissions from its waste sector. It also creates a larger potential base for future carbon projects.

Carbon Credits Could Turn Methane Cuts Into Revenue

The carbon credit opportunity is important because landfill gas projects can turn an emissions problem into a marketable environmental asset. be’ah’s partnership with OQ Trading gives the company support in developing, verifying, and marketing credits.

The projects’ registration under Verra also provides a recognized framework for measuring and issuing credits. But carbon credits are not guaranteed revenue.

Project developers must prove that emissions reductions occurred and meet monitoring and verification requirements. Credit volumes can also vary depending on how much gas a landfill produces and how much the project captures.

That means be’ah’s future carbon revenue will depend on actual gas recovery, project performance, and demand from carbon credit buyers.

Oman landfill waste to carbon credits be'ah

Oman Tests a Waste-to-Carbon Model

Oman’s landfill strategy shows how carbon markets can support practical waste management projects. be’ah is targeting methane, which accounts for the vast majority of its measured emissions. It is also moving from simple gas flaring toward electricity generation at two major landfills.

The generated VCUs already provide an early example of how landfill emissions reductions can create tradable carbon assets. The next step will be scaling gas recovery and electricity generation while maintaining strong measurement and verification.

If be’ah can expand these projects across more landfills, Oman could develop a larger waste-based carbon market while reducing methane emissions and producing useful energy.

The post Oman Turns Landfill Methane Into Carbon Credits and Clean Energy appeared first on Carbon Credits.
EU Carbon Prices May Push Bitcoin Mining Toward Russia, Study Finds

EU Carbon Prices May Push Bitcoin Mining Toward Russia, Study Finds

A new study suggests that higher European Union carbon prices may be linked to more Bitcoin mining activity in Russia, raising concerns about carbon leakage from Europe’s climate policies.

The study, “Does Carbon Pricing Displace Crypto-Mining Emissions? Quantile Evidence on Carbon Leakage from EU27, Russian and Rest-of-World Power Grids,” was submitted to MDPI. Researchers analyzed daily data from January 2019 to January 2026.

The researchers found a significant link between Bitcoin returns, EU carbon allowance returns, and Russian power sector emissions. They say the result is consistent with mining activity shifting toward Russia when Bitcoin prices and EU carbon prices rise.

However, the study does not prove that mining machines physically moved from Europe to Russia. The authors say miners with equipment in both markets could instead switch machines on or off depending on which location offers better returns.

That distinction is important for carbon credit market policy.

How EU Carbon Pricing Can Affect Bitcoin Mining

The EU’s Emissions Trading System (ETS) puts a price on greenhouse gas emissions from covered sectors. Companies generally need one allowance for each tonne of CO2 they emit.

Carbon costs can affect electricity prices, especially where fossil fuel power plants set wholesale prices. That matters for Bitcoin miners because electricity is one of their highest operating costs.

Bitcoin uses a proof-of-work system. Miners run specialized computers to process transactions and secure the network. When electricity becomes more expensive, mining becomes less profitable, but higher Bitcoin prices can improve mining returns.

The new study examines what happens when these two factors work together with EU carbon prices.

What the Study Found

The researchers used 2,550 daily observations covering January 2019 through January 2026. They compared power sector CO2 emissions in the EU27, Russia, and the rest of the world with Bitcoin returns and EU carbon allowance returns.

Russia showed the strongest result.

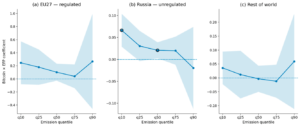
The interaction between Bitcoin returns and EU carbon allowance returns was positive and statistically significant in Russia’s lower emissions range, with a beta of 0.066 and a p-value of 0.001.

EU carbon pricing bitcoin mining russia
Source: Toan, P.N. et al. Risks 2026. https://doi.org/10.3390/risks14080187

The relationship also remained significant under other tests. The study reports p = 0.012 using ordinary least squares with robust errors and p = 0.010 in a dynamic model that accounts for past emissions. Russia was the only region where the overall model was jointly significant.

The same relationship did not appear consistently in the EU27 or the rest of the world.

The researchers say the Russian effect emerged mainly after 2020, around the time of China’s crackdown on Bitcoin mining and a sharp rise in European carbon allowance prices.

Russia Could Offer Lower Mining Costs

The study points to Russia as a possible destination because it does not have an EU-style carbon pricing system.

For miners, that can create a cost difference. If carbon costs push up electricity prices in Europe while Bitcoin prices remain attractive, miners may have an incentive to use equipment in locations with lower power costs.

The researchers suggest that some companies could hold mining hardware in both regions and change where they run the machines. This would look like a migration in the data even if no physical equipment crossed the border.

The study therefore describes the result as possible operational carbon leakage. Carbon leakage occurs when climate policies reduce emissions in one place but cause some activity and emissions to move elsewhere.

Russia’s Mining Rules Could Limit the Shift

Russia’s position is not as simple as offering cheaper power. The country introduced a legal framework for cryptocurrency mining in 2024. It has also restricted mining in regions facing electricity shortages.

The restrictions became important from 2025, when Russia banned mining in several areas and introduced seasonal limits in others. Further restrictions could make it harder for miners to relocate operations to Russia solely to avoid higher energy costs.

The study also recognizes these limits. It notes that Russia’s changing mining rules could reduce operators’ ability to shift activity between countries.

This means carbon pricing is only one part of the mining location decision. Electricity prices, regulations, hardware efficiency, and access to the grid also matter.

Bitcoin Prices Can Change the Equation

Bitcoin’s price is another major part of the equation. When Bitcoin becomes more valuable, miners can potentially earn more from the same amount of computing power. That can make higher electricity costs easier to absorb.

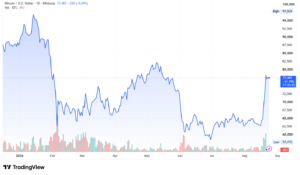
Bitcoin BTCUSD stock price

Bitcoin has remained highly volatile in 2026, making mining economics change quickly. This is why the study looks at Bitcoin returns rather than Bitcoin’s price alone. It tests whether changes in Bitcoin profitability interact with changes in European carbon prices and power sector emissions.

The research does not say carbon pricing alone causes mining to move. Instead, it finds a statistical relationship that becomes stronger when Bitcoin returns and EU carbon allowance returns rise together.

Crypto’s Power Footprint Raises the Stakes

The issue matters because Bitcoin mining consumes large amounts of electricity.

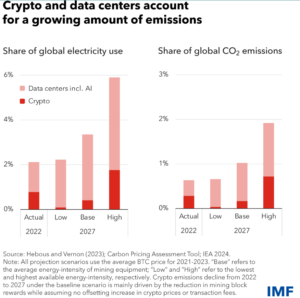
The International Monetary Fund (IMF) has sharply increased its estimates on the environmental footprint of digital technology. When combining crypto mining with Artificial Intelligence (AI) data centers, their collective electricity consumption has surged to 2% of global electricity.

This combined power demand is now equivalent to the entire power grid of Japan, the world’s fifth-largest energy user.

Individually, crypto mining remains a major source of pollution. The IMF projects that crypto mining alone will account for 0.7% of global carbon dioxide emissions by 2027. This is a dramatic increase from the 0.33% estimated back in 2022.

crypto and data center energy and emissions IMF
Source: IMF

To help curb these rising emissions, the IMF proposes a targeted electricity tax of $0.047 per kilowatt-hour on crypto mining operations worldwide. Including local air pollution costs would raise the figure to about $0.089 per kWh.

These estimates show why electricity and carbon costs can have a major effect on mining economics.

They also explain the policy concern. If carbon pricing makes mining more expensive in one market but miners simply increase activity in a less regulated market, global emissions may not fall as much as expected.

The Study Comes With Important Caveats

The findings should not be treated as proof that EU carbon prices directly caused Bitcoin miners to move to Russia. The paper is currently a preprint, not a final peer-reviewed study. More importantly, the researchers did not track individual mining companies or physical mining equipment.

The study also notes that China’s May 2021 Bitcoin mining ban disrupted the relationship between mining activity and emissions. Other factors affecting Russian power sector emissions are not fully captured by the model.

These limits make the results better viewed as evidence of a possible link rather than a definitive cause-and-effect finding. Still, the Russia result is notable because the same relationship did not appear in the EU27 or the rest of the world.

Could Bitcoin Become a New Carbon Leakage Test?

The findings raise a wider question for carbon markets. Carbon pricing aims to make pollution more expensive and encourage cleaner energy.

The EU ETS has helped drive large emissions reductions in covered sectors. However, mobile activities such as Bitcoin mining can respond quickly to changes in electricity costs.

That makes Bitcoin different from industries such as steel or cement, where moving an entire production plant is costly and slow.

For policymakers, the challenge is therefore not only reducing emissions inside a carbon pricing system. It is also limiting the risk that energy-intensive activity shifts to markets with weaker climate rules.

The new study does not prove that EU carbon pricing is pushing Bitcoin miners into Russia. Yet, it provides statistical evidence consistent with that possibility.

As Bitcoin prices, mining technology and carbon costs continue to change, the issue could become more important for policymakers trying to cut emissions without simply moving them across borders.

The post EU Carbon Prices May Push Bitcoin Mining Toward Russia, Study Finds appeared first on Carbon Credits.
Google Commits $60 Million to Water Projects as AI Data Center Demand Grows

Google is stepping up its water stewardship as AI drives data center growth. The company has pledged $60 million to new water projects in the U.S. Its goal is to achieve water positivity across data center operations by 2030. This means Google aims to replenish more freshwater than it uses while also supporting water quality and ecosystem health.

This effort builds on a water strategy launched in 2021. At that time, Google aimed to use water wisely, replenish what it uses, and enhance watershed health in its operational areas.

The challenge is growing as Google’s data center footprint expands. The company consumed 10.9 billion gallons of water in 2025. This is a 34% increase from the previous year and over twice its 2021 usage.

Google Replenished 78% of Its Water Use in 2025

Despite rising use, Google has grown its water replenishment efforts.

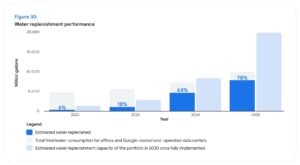
  • In 2025, its projects replenished about 7.7 billion gallons of water, or roughly 78% of its consumption. This is up from 63% in 2024.

During the year, Google added 54 projects, boosting its total to 165 across 97 watersheds. The company estimates these projects could replenish over 19.7 billion gallons annually by 2030 when fully operational.

Google measures replenishment benefits using the Volumetric Water Benefit Accounting 2.0 method through a third-party partner. It counts projects in watersheds linked to its operations with confirmed benefits.

google water positive
Source: Google

The new funding will help expand Google’s projects to 12 states, including five new initiatives in:

  • Ohio
  • Indiana
  • Arizona
  • Oklahoma
  • Virginia

These projects address local water challenges rather than just offsetting consumption.

In Arizona, Google supports removing culverts to restore natural streamflow for Apache trout. In Indiana, it collaborates with Fort Wayne City Utilities to improve water reuse and cut withdrawals from the St. Joseph River.

An Ohio project will enhance agricultural drainage through H2Ohio. In Oklahoma, Google is removing invasive Eastern Red Cedar trees and restoring native wetlands. In Virginia, stormwater filtration systems will improve water quality in the Chesapeake Bay and Roanoke River watersheds.

AI Is Increasing the Water Challenge

Google’s progress comes as AI drives rapid growth in computing.

AI servers use a lot of electricity and generate heat. Many data centers rely on evaporative cooling systems, which need water to remove heat.

  • In 2025, Google’s freshwater consumption rose by 37% due to expanding data centers for AI and other services. The company expects its water use to keep increasing.

This presents a tough sustainability challenge. Google must speed up its replenishment projects to match rising demand while ensuring meaningful benefits in the watersheds where it operates.

  • This issue goes beyond Google’s operations. Estimates suggest that the water footprint from data center electricity could reach 9.3 trillion liters by 2030.

Data centers often locate in areas with attractive land, electricity, and tax incentives. Unfortunately, these spots can overlap with water-stressed regions, leading to competition for water among data centers, households, agriculture, and industry.

google data center

Consequently, water availability is becoming a pressing concern for investors, regulators, and local communities. Companies may face more scrutiny when seeking approval for large data center projects, especially in water-scarce areas.

Water Positive Does Not Mean Water Use Is Low

The term “water positive” is increasingly common among tech companies.

Google, Microsoft, Meta, and Amazon have all set water stewardship or replenishment targets tied to their data centers. These commitments help address concerns about the environmental impact of infrastructure supporting cloud computing and AI.

However, replenishing water doesn’t mean a data center has low consumption.

A better approach starts with reducing freshwater needs. Companies can use air cooling, closed-loop systems, and reclaimed water to limit withdrawals. Then, they can enhance water efficiency per computing unit before investing in replenishment.

The location of these projects matters too. Replenishing water far from stressed watersheds may show measurable benefits but doesn’t tackle local water challenges caused by a data center.

This is why Google’s focus on projects within connected watersheds is crucial. Its projects aim to combine water replenishment with improvements to water quality, biodiversity, and community water security.

Google’s Climate Impact Is Also Growing

Water is just one part of the environmental challenge from AI infrastructure growth.

Google reported about 14.5 million metric tons of carbon emissions in 2025, an 18% rise from 2024. Much of this increase came from supply chain activities supporting rapid business growth.

  • However, it also estimates its decarbonization efforts avoided over 58 million metric tons of CO2e in 2025.

Clean energy purchases played a big role in these avoided emissions. Google estimates that its clean energy buys prevented about 57 million metric tons of CO2e from 2012 to 2025, including around 12 million metric tons in 2025.

These figures highlight the broader sustainability challenge for AI companies. Efficiency improvements and clean energy can lessen the environmental impact of computing capacity, but rapid growth can still push overall resource use higher.

google emissions
Source: Google

Water Stewardship Could Become a Competitive Advantage

Google’s expansion of its water investments shows how strategically important water is becoming for tech companies.

As AI infrastructure grows, companies will need more electricity, cooling, land, and water. Responsible management of these resources could be key for securing permits, gaining community support, and meeting investor demands.

For Google, the aim is more than just replenishing water used by its facilities. The company is linking its investments to watershed restoration, water quality, and ecosystem health.

The next challenge will be whether these efforts can keep up with AI’s rapid expansion.

Google’s 2030 target is to replenish 120% of the freshwater it uses in its offices and data centers. Achieving this will require ongoing investment, better water efficiency, and projects that deliver measurable benefits to local communities.

As AI changes the tech industry, competition may shift from just computing power to also include who can build infrastructure while minimizing pressure on natural resources.

The post Google Commits $60 Million to Water Projects as AI Data Center Demand Grows appeared first on Carbon Credits.
CORSIA and SAF: The Complete Guide to Aviation’s Net-Zero Future

Aviation is entering a new phase in its efforts to cut carbon emissions. As air travel grows, airlines face pressure to reduce emissions while meeting the demands of long-distance flight. Carbon Offsetting and Reduction Scheme for International Aviation (CORSIA) and sustainable aviation fuel (SAF) are becoming key tools, creating new policies, markets, and investment opportunities across the aviation industry.

This guide explains how CORSIA works, how SAF fits into aviation’s decarbonization strategy, and where the market is headed. It covers CORSIA rules and timelines, eligible carbon credits and fuels, SAF production pathways, market trends, costs, policy drivers, and the supply gap the industry must close to reach net zero.

CORSIA and SAF: Why Aviation Needs a New Decarbonization Strategy 

Aviation is one of the harder sectors to decarbonize. Aircraft need energy-dense fuels that can support long flights without adding excessive weight. Unlike cars, most commercial aircraft cannot yet switch to large battery systems at scale.

Aviation produces about 2.5% of global human-caused CO₂ emissions, according to the International Air Transport Association (IATA). Its wider climate impact also includes non-CO₂ effects such as contrails and nitrogen oxide emissions.

This makes aviation’s transition more complex than simply replacing fossil fuels with electricity. More efficient aircraft, improved flight operations and new propulsion systems can all reduce emissions. However, sustainable aviation fuel could play a major role in the near term.

SAF can be produced from feedstocks such as used cooking oil, agricultural waste and other renewable materials. It can also be used in existing aircraft as a drop-in fuel, allowing airlines to reduce lifecycle emissions without replacing their fleets. IATA estimates SAF could provide about 65% of the emissions reductions needed for aviation to reach net-zero CO₂ emissions by 2050.

SAF is not the only solution. CORSIA, ICAO’s global market-based measure for international aviation, addresses emissions that remain after other reduction measures. Together, SAF and CORSIA form two important parts of aviation’s broader path toward net zero.

What Is CORSIA? 

CORSIA is a global system created by the International Civil Aviation Organization (ICAO) to address the growth of CO₂ emissions from international aviation. It works alongside cleaner fuels, aircraft efficiency, and improved flight operations.

CORSIA’s offsetting requirements apply to eligible international flights between participating states. Domestic aviation is outside the scheme’s offsetting system. Airlines covered by CORSIA must also monitor, report, and verify their emissions under the program’s MRV requirements.

For 2024–2035, CORSIA uses a baseline equal to 85% of 2019 emissions. When an airline has an offsetting requirement, it must cancel eligible emissions units to cover the required amount.

CORSIA is therefore different from a conventional carbon tax. It creates a framework for managing specific international aviation emissions through approved emissions units.

The scheme also recognizes the emissions benefits of CORSIA Eligible Fuels, including qualifying SAF. This creates an important link between aviation fuel markets and carbon markets.

  • In simple terms, SAF helps reduce aviation’s emissions, while CORSIA provides a framework for addressing some emissions that remain.

CORSIA Timeline: From Pilot Phase to Full Implementation

CORSIA was adopted by ICAO in 2016 and is being introduced in stages. This phased approach gives airlines, governments, and carbon-market participants time to build the systems needed for monitoring emissions and meeting offsetting requirements.

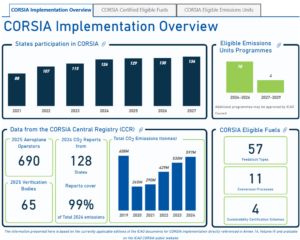
The Pilot Phase ran from 2021 to 2023. During this period, participation was voluntary, allowing countries and airlines to gain experience with CORSIA’s monitoring, reporting, and verification requirements.

The First Phase covers 2024 to 2026, with states participating voluntarily. However, airlines operating on routes between participating states can still be subject to CORSIA offsetting requirements. This is the phase CORSIA is currently in.

The Second Phase will run from 2027 to 2035. Participation becomes broader, although ICAO provides exemptions for certain states based on factors such as their level of international aviation activity and development status.

CORSIA implementation overview ICAO
Source: ICAO

As of 2026, 130 states participate voluntarily in CORSIA. ICAO lists 134 participating states from 2027, when the Second Phase begins. Together, these phases are designed to expand the system while giving countries time to establish the necessary regulatory and reporting frameworks.

Beyond 2035, CORSIA will continue to operate as part of ICAO’s wider strategy for achieving net-zero carbon emissions from international aviation by 2050.

How CORSIA Calculates Airline Offset Requirements

CORSIA does not require airlines to offset all of their international aviation emissions. Instead, it focuses on emissions above a set baseline.

  • From 2024 to 2032, the system mainly uses the growth of international aviation as a whole (100%). This is called the sectoral approach. It means an airline’s offset requirement is linked to the industry’s overall emissions growth, rather than only its own growth.
  • From 2033 to 2035, the calculation will use both industry-wide and airline-specific emissions growth. The sectoral share will be 85%, while the airline-specific share will be 15%.

Airlines can also reduce their CORSIA obligation by using CORSIA Eligible Fuels, including qualifying SAF. They must provide records showing the amount of fuel used and its emissions savings.

This gives airlines two main ways to lower their CORSIA costs:

  1. reduce emissions, and
  2. use eligible lower-carbon fuels.

CORSIA Carbon Credits: What Can Airlines Use?

Airlines with a CORSIA offsetting requirement must cancel approved CORSIA Eligible Emissions Units (carbon credits) to cover it. These are not the same as any carbon credits sold in the voluntary carbon market. ICAO has a specific approval process for carbon credit programs that want to supply units for CORSIA.

The organization checks programs against rules covering areas such as additionality, monitoring, verification, and double counting. These rules are designed to make sure the claimed emissions reductions are real and properly tracked.

ICAO updates its list of eligible programs and units over time. As of April 2026, the framework includes programs such as the American Carbon Registry, Climate Action Reserve, Gold Standard, Isometric, and Verra’s Verified Carbon Standard, subject to specific eligibility conditions.

Importantly, being part of an approved program does not mean every credit from that program can be used under CORSIA. Eligibility can depend on factors such as the credit type, vintage, compliance period, and additional authorization requirements.

This has created a potential supply problem…

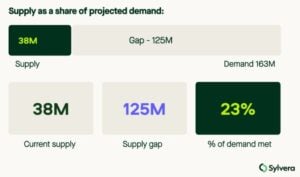
A July 2026 analysis from Sylvera estimates that CORSIA could create demand for about 163 million eligible emissions units (EEUs) during its first compliance phase, rising to 198 million credits under full implementation. Yet only about 38 million credits currently qualify, covering just 23% of expected first-phase demand. This creates a potential 125 million-credit supply gap.

corsia credit demand and supply gap sylvera
Source: Sylvera

The problem is not a lack of issued credits. About 300 million credits have been issued. However, many can’t qualify for CORSIA. They lack the necessary host-country Letters of Authorization or Corresponding Adjustments under Article 6 of the Paris Agreement.

By January 2028, the eligible supply might hit 640 million credits. However, Sylvera estimates that only about 104 million could be eligible due to authorization risks. Just 48 million are fully confirmed.

Airline purchases also remain limited. Only around 400,000 tonnes of CORSIA credits had been retired, equal to about 0.2% of expected first-phase demand. Delayed buying could create a rush for eligible credits as compliance deadlines approach.

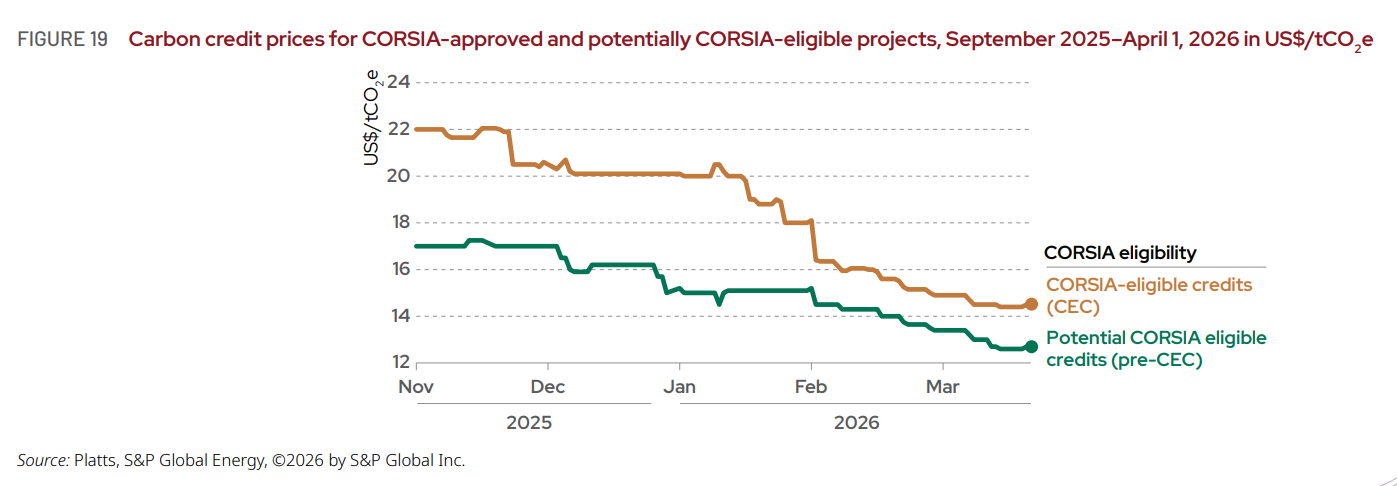
Carbon credit prices for CORSIA-approved

That shortage could push prices higher. Sylvera’s modeling puts first-phase credit prices at about $15 per tonne in a low case, $33 in a base case, and $53 in a high case by January 2028.

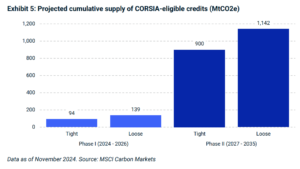
The long-term cost could be much larger. An MSCI Carbon Markets analysis shows that if supply tightens, CORSIA compliance costs might hit $127 billion from 2024 to 2035. By 2035, eligible credit prices could reach nearly $100 per tonne. Estimated exposure includes about $8 billion for Emirates, $6 billion for Qatar Airways, and $5 billion for United Airlines.

CORSIA eligible carbon credits supply

These figures show why CORSIA is becoming a distinct carbon market. The challenge is not simply finding credits, but securing enough high-quality, authorized units that meet CORSIA’s eligibility rules.

What Is Sustainable Aviation Fuel (SAF)?

Sustainable aviation fuel is aviation fuel made from renewable or waste-based materials. It is designed to replace part of the fossil jet fuel used by aircraft while producing lower emissions over its full lifecycle.

SAF can be made from feedstocks such as used cooking oil, animal fats, crop residues, forestry waste, and other biomass. Newer pathways can also use renewable electricity, hydrogen, and captured carbon to make synthetic fuels.

One of SAF’s main advantages is that it can work with today’s aircraft and fuel systems. Airlines can use approved SAF by blending it with conventional jet fuel, without replacing their existing fleets.

However, SAF is not automatically low-carbon. Its climate benefits depend on the feedstock, production method, energy source, and land-use impacts. CORSIA therefore uses lifecycle emissions to measure the climate performance of eligible fuels.

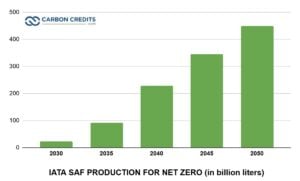
SAF also remains a very small part of the global fuel market. IATA expects global SAF production to reach about 2.4 million tonnes in 2026, equal to only 0.8% of total jet fuel use. But it must increase tremendously to 449 million tonnes by 2050 for net-zero aviation.

IATA SAF production for net zero 2050

This large gap between current supply and future demand is one of the biggest challenges facing aviation’s net-zero plans.

SAF Feedstocks and Production Technologies: How SAF is Made

SAF can be made from many different materials. The choice of feedstock affects the fuel’s cost, emissions, and ability to scale.

Today, some of the main feedstocks include used cooking oil, animal fats, agricultural residues, forestry waste, and other forms of biomass. Waste and residue feedstocks are attractive because they can avoid some of the land and food concerns linked to conventional crops. ICAO groups SAF feedstocks into categories such as primary products, by-products, wastes and residues.

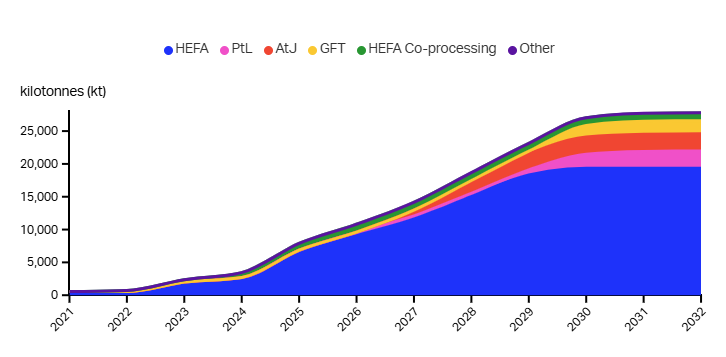
Several technologies can turn these materials into jet fuel. One of the most widely used is HEFA, which processes oils and fats with hydrogen. Other pathways include Fischer-Tropsch (FT), which can turn biomass or other carbon sources into fuel, and alcohol-to-jet (ATJ), which converts alcohols such as ethanol into aviation fuel.

Another emerging option is e-SAF, also called power-to-liquid fuel. It uses renewable electricity, hydrogen, and captured carbon to produce synthetic aviation fuel. This could greatly expand SAF supply because it is less dependent on biomass.

Announced SAF facilities
Announced SAF Facilities, Source: International Air Transport Association

However, each pathway faces challenges. Waste feedstocks are limited, while newer technologies are still expensive and need more production capacity.

  • This creates a key issue for the SAF market: the aviation industry needs much more fuel, but sustainable feedstocks and production capacity remain limited.

What Makes SAF Eligible Under CORSIA?

Not all SAF automatically qualifies under CORSIA. To receive CORSIA benefits, the fuel must meet ICAO sustainability rules and come from a producer certified under an ICAO-approved sustainability certification scheme.

One key requirement is emissions performance. CORSIA SAF produced from 2024 onward must achieve at least a 10% reduction in lifecycle greenhouse gas emissions compared with the baseline aviation fuel.

ICAO also considers factors such as land use, carbon stocks and the sustainability of the feedstock. This helps prevent fuels with poor environmental performance from receiving CORSIA benefits.

The system measures emissions across the fuel’s full lifecycle. This can include feedstock production, processing, transport, fuel production and aircraft use. It can also account for emissions linked to land-use change.

For airlines, this matters because qualifying SAF can lower their CORSIA offsetting requirement. The fuel must be properly certified, and its emissions savings must be supported by the required records. This creates a strong link between SAF production, sustainability certification, and the aviation carbon market.

ICAO’s CORSIA Eligible Fuels page was updated in June 2026. It now lists the Fourth Edition of the CORSIA Approved Sustainability Certification Schemes, and on June 22, 2026, ICAO approved Bonsucro as a new CORSIA-approved sustainability certification scheme.

The SAF Supply Gap: From 2.4M Tonnes to 500M

The biggest question for SAF is whether production can grow fast enough to meet future demand. As mentioned, IATA expects global SAF production to reach only 2.4 million tonnes in 2026. Yet, its net-zero pathway points to millions of tonnes of SAF per year by 2050.

  • That means production must increase by more than 200 times from today’s level.

The challenge is not only building more SAF plants. The industry also needs enough sustainable feedstock, hydrogen, renewable power, refining capacity, and transport infrastructure.

Waste oils and fats are useful today, but their supply is limited. Other options, such as agricultural and forestry waste, could provide more fuel but require large collection and processing networks.

E-SAF could eventually reduce some feedstock limits by using renewable electricity, hydrogen and captured carbon. But the technology remains expensive and needs much more clean power.

The 2030s will therefore be critical. Governments will need stronger policies, while airlines and fuel producers will need to commit more capital.

If production grows slowly, SAF could remain a scarce and expensive fuel. If investment and technology scale quickly, it could become a much larger part of the global aviation fuel market.

What Could Slow CORSIA and SAF Growth?

CORSIA and SAF face different challenges, but they are connected by the same goal: reducing aviation’s climate impact.

  • For CORSIA, one challenge is coverage. The system applies to international aviation, while domestic flights are outside its offsetting system. Its impact also depends on how many states participate and how effectively airlines follow the rules.
  • SAF faces a larger physical challenge. There is simply not enough low-carbon fuel available today. Production must grow much faster, while sustainable feedstocks remain limited.
  • Cost is another major barrier. Airlines operate in a price-sensitive industry, so buying large amounts of expensive SAF can be difficult without policy support or customer demand.
  • There is also a need for clear sustainability rules. SAF should deliver real emissions cuts without causing major damage through land-use change or other environmental impacts.

These challenges do not mean SAF or CORSIA will fail. They show why aviation needs a mix of solutions rather than relying on one technology or policy.

Conclusion: CORSIA and SAF Have Different Jobs

CORSIA and SAF are becoming important parts of aviation’s climate strategy, but they serve different purposes.

SAF tackles emissions at the fuel level. CORSIA helps address emissions that remain from international aviation. Together, they support a wider strategy that also includes better aircraft, more efficient operations and new technologies.

Closing the huge SAF production gap will require more than airline demand. Governments will need effective policies, producers will need major investment, and the industry will need new technologies and sustainable feedstocks.

CORSIA will also continue to evolve as its Second Phase begins in 2027. ICAO’s current framework already includes rules for eligible carbon units and fuels, giving the aviation industry a common system for managing international emissions.

The long-term outcome will depend on how quickly these systems can scale. For now, one point is clear: aviation’s path to net zero will depend heavily on making cleaner fuels available at much greater scale while strengthening the global rules that support emissions reductions.

The post CORSIA and SAF: The Complete Guide to Aviation’s Net-Zero Future appeared first on Carbon Credits.
Senken Signs 50,000-Tonne Biomass Carbon Removal Deal with Carbonsate in Namibia

Carbon removal buyer Senken and project developer Carbonsate have signed a 50,000-tonne carbon removal agreement tied to a biomass storage project in Namibia. The multi-year deal covers removals from 2026 through 2028, with deliveries starting this year.

Senken claims it’s the largest biomass storage deal in Europe so far. This agreement is also the second-largest buyer commitment worldwide in biomass geological storage and the biggest for a project in Africa.

The deal comes as companies look for more durable ways to remove carbon from the atmosphere. The project buries waste biomass underground. This prevents it from burning or decaying. It keeps carbon locked away for at least 100 years under the current certification.

A 50,000-Tonne Commitment Through 2028

The agreement covers 50,000 tonnes of certified carbon removal across the 2026, 2027 and 2028 vintages. Senken will procure the volumes for corporate buyers that need permanent carbon removal for their climate plans.

Senken says the deal is its third multi-year carbon removal supply commitment of 2026. Its other 2026 deal covered direct air capture, industrial biochar and regenerative agriculture for the aviation sector.

The companies also see room to expand the deal.

Carbonsate’s Namibia project could scale to more than 100,000 tonnes of carbon removal per year within the next few years, according to Senken. The two companies plan to expand their agreement as new capacity becomes available.

This matters because today’s carbon removal market still has limited supply. Senken says the wider permanent removal market has delivered about 1.5 million tonnes so far. The new 50,000-tonne agreement would equal roughly 4% of that amount.

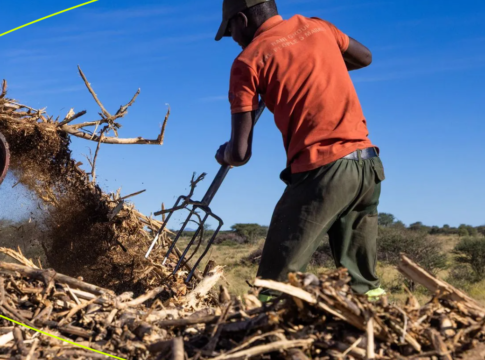
Carbonsate carbon removal project namibia
Source: Carbonsate

How Namibia’s Waste Biomass Becomes Carbon Storage

Biomass storage is a form of carbon dioxide removal that uses plants as the first step. Plants absorb CO2 from the atmosphere as they grow. Normally, that carbon returns to the atmosphere when the plant material burns or decomposes.

Carbonsate takes a different approach.

The company removes excess woody biomass from Namibia’s savanna and places it in specially designed underground storage chambers. The chambers limit oxygen and moisture, which slows decomposition and keeps the carbon stored.

The method does not use an energy-intensive carbon capture process. It also does not turn the biomass into biochar. Instead, the wood remains largely intact while the storage system prevents it from breaking down.

Senken says this can reduce the cost and energy needs of the removal process compared with some other engineered carbon removal methods.

The IPCC defines carbon dioxide removal as human activities that remove CO2 from the atmosphere and store it for a long period. It also stresses that carbon removal should support, rather than replace, deep emissions cuts.

Namibia Turns Bush Encroachment Into a Carbon Opportunity

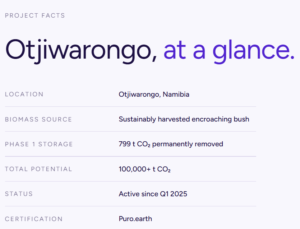
Carbonsate’s project is located in the savanna around Otjiwarongo, Namibia. It focuses on encroaching bush, where woody plants have spread across grassland. Carbonsate says this can reduce biodiversity, limit grass growth, lower groundwater recharge, and reduce the productivity of grazing land.

The company selectively removes this excess bush as part of land management. Instead of burning the harvested wood or allowing it to decay, it stores the biomass underground. This creates a link between carbon removal and land restoration.

Carbonsate says the work can help restore grasslands, improve biodiversity and support healthier range lands. It also works with local landowners, farmers and service providers on harvesting, transport, site preparation and monitoring.

The approach therefore aims to deliver both carbon removal and local environmental benefits.

Project Uses Puro.earth Certification

The Carbonsate Namibia project has passed a third-party facility audit under Puro.earth‘s certification system and has received carbon removal certificates, or CORCs.

Puro.earth lists the project under its Terrestrial Storage of Biomass methodology. The standard requires projects to measure the amount of carbon removed and verify the results. Puro.earth says certified projects must pass facility and output audits before receiving CORCs.

The Carbonsate project has a minimum durability period of 100 years. The company uses engineered storage systems, along with a monitoring, reporting, and verification system, to track storage conditions.

Puro.earth‘s project listing shows that Carbonsate issued 799 CORCs in 2025. Senken says the project is scheduled to deliver about 10,000 credits in 2026.

That difference is important. The 50,000 tonnes covered by the deal are contracted future removals, not 50,000 carbon credits already issued.

Monitoring Is Key to Long-Term Storage

Biomass storage depends on keeping the stored material stable over time. Carbonsate uses sensors to monitor its storage sites. It also uses on-site measurements to track gas emissions and check storage performance.

Puro.earth says the project stores the biomass in engineered pits and covers it to limit oxygen and moisture. Namibia’s dry climate also supports the storage approach because of its low rainfall and high evaporation rates.

The need for monitoring is important because carbon removal is only useful if the stored carbon stays out of the atmosphere.

The Intergovernmental Panel on Climate Change (IPCC) notes that carbon removal methods differ in their storage periods, risks, and environmental effects. It also says strong governance is needed to manage these risks and maintain durable storage.

  • For biomass storage, this makes the choice of feedstock, storage design, and monitoring system especially important.

Carbon Removal Market Moves Toward Longer Deals

The Senken-Carbonsate agreement also shows how buyers are helping new carbon removal methods to scale. Removal projects often need investment before they can produce large volumes. Multi-year offtake agreements give developers a clearer source of future demand.

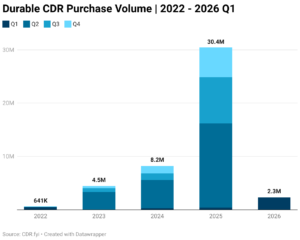
durable-cdr-purchase-volume-2022-2026-q1

The broader durable carbon removal market is growing, but supply remains limited. CDR.fyi reported 2.3 million tonnes of durable carbon removal contracted in the first quarter of 2026, a record first quarter. It also recorded 145,000 tonnes delivered during the quarter.

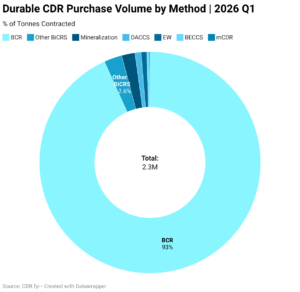
Biomass-based methods were a major part of that market. Biochar alone accounted for 93% of durable carbon removal contracted in Q1 2026, according to CDR.fyi.

durable-cdr-purchase-volume-by-method-2026-q1

Biomass storage remains a much smaller market. Senken describes it as being at an early commercial stage, with supply concentrated among a small number of projects. That makes large multi-year commitments important for developers trying to move from early projects to larger operations.

A New Test for Biomass Carbon Removal

The 50,000-tonne Senken-Carbonsate agreement gives Namibia’s biomass storage sector a major new commercial commitment. The project combines excess bush removal, underground biomass storage, and long-term monitoring. Its Puro.earth certification also gives buyers a defined framework for measuring and verifying carbon removal.

However, scaling the method will depend on more than buyer demand.

Carbonsate must expand its storage capacity while maintaining the quality and monitoring standards behind its credits. The project must prove that the stored biomass stays stable. It should also show that carbon removal is significant, even after considering emissions from harvesting, transport, storage, and monitoring.

For Senken, the deal secures future removal volumes for corporate buyers. For Carbonsate, it provides demand that can help expand its Namibia operations.

If the project delivers the contracted volumes and maintains its removal standards, the agreement could help show how biomass storage can move from an emerging carbon removal method to a larger commercial-scale supply.

The post Senken Signs 50,000-Tonne Biomass Carbon Removal Deal with Carbonsate in Namibia appeared first on Carbon Credits.
Walmart (WMT Stock) Sales Rise as Emissions Fall, Putting Sustainability to the Test

Walmart (WMT Stock) Sales Rise as Emissions Fall, Putting Sustainability to the Test

Walmart delivered another quarter of sales growth on August 20, 2026, while its latest sustainability data shows a sharp drop in operational emissions. The world’s largest retailer is now balancing business growth with its goal of reaching zero Scope 1 and 2 emissions across global operations by 2040.

Walmart reported $187.9 billion in second-quarter fiscal 2027 revenue, up 5.9% from a year earlier. Global e-commerce sales jumped 23%, while Walmart U.S. comparable sales increased 2.6%. The company also raised its full-year sales outlook to 4% to 5% growth.

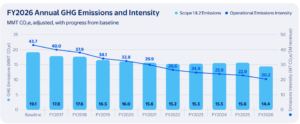
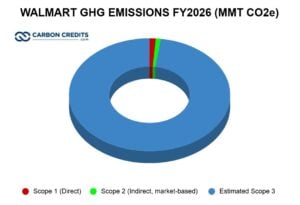
The results came as Walmart’s FY2026 ESG data showed Scope 1 and 2 emissions fell 7.5% year-over-year. Renewable sources supplied 53.3% of its global electricity needs, while its wider supply chain emissions remain far larger than its direct operational footprint.

Walmart Delivers Strong Revenue Growth, But U.S. Sales Lose Some Momentum

Walmart’s latest earnings show that the retailer continues to expand even as consumers face higher fuel costs and other economic pressures. Revenue reached $187.9 billion in the three months ended July 31, 2026. Global e-commerce sales rose 23%, with growth across Walmart’s major markets.

Walmart key financial metrics FY2027
Source: Walmart

However, Walmart U.S. comparable sales grew just 2.6%. Reuters reported that this was the company’s slowest quarterly comparable-sales growth in six years and below the 3.8% analyst expectation.

Despite the slower U.S. sales growth, Walmart raised its full-year outlook. The company now expects fiscal 2027 net sales to grow 4% to 5%.

Walmart (WMT Stock) Shares Slide After Earnings

Walmart shares fell about 9.1% on August 20, despite the retailer beating earnings and revenue expectations. Investors focused on slower U.S. comparable-sales growth and weaker-than-expected third-quarter guidance, sending Walmart’s stock to its lowest level of 2026.

Walmart WMT stock price

The results show the scale of Walmart’s business. That scale also makes its climate strategy important. Changes in energy use, transport, refrigeration, packaging and products can affect emissions across a very large global supply chain.

Direct Emissions Drop 7.5% as Walmart Pushes Toward 2040

Walmart’s latest ESG report gives a more positive picture on direct emissions. In FY2026, Walmart cut its absolute Scope 1 and 2 emissions by 7.5% year-over-year.

The company said this brought its reduction to 24.6% from its FY2016 baseline. Operational emissions intensity also fell 11.6% year-over-year and 53.7% from FY2016.

Walmart annual GHG emissions 2026
Source: Walmart ESG Report

Scope 1 covers emissions from sources Walmart owns or controls, such as fuel use. Scope 2 covers emissions linked to the electricity it buys.

The retailer’s progress comes as it works toward zero Scope 1 and 2 emissions across its global operations by 2040. The company says it plans to reach that goal without relying on carbon offsets. Its plan includes more:

  • Renewable energy,
  • Cleaner vehicles,
  • Lower-impact refrigerants, and
  • Electrified equipment.

Renewables Now Power More Than Half of Walmart’s Electricity

Clean electricity is one of Walmart’s main tools for cutting emissions. Renewable sources supplied 53.3% of the company’s global electricity needs in FY2026, according to its ESG report. This puts Walmart above its earlier goal of powering 50% of its global operations with renewable energy by 2025.

  • The retail giant’s longer-term goal is to reach 100% renewable energy for its operations by 2035.

The retailer operates stores, clubs, distribution centers and other facilities across 19 countries. That means moving a large share of its electricity use to renewable sources can have a significant effect on its operational emissions.

Walmart is also expanding customer-facing clean energy services. Its U.S. stores and clubs had more than 1,300 electric vehicle charging stations in FY2025, per its ESG reporting.

Supply Chain Remains Walmart’s Bigger Carbon Challenge

Walmart’s estimated Scope 3 emissions reached 635 million metric tons of CO2e in FY2026, far above its direct operational emissions. Although Scope 3 emissions intensity improved 8.29% from FY2022, total emissions increased as Walmart grew and its product mix changed.

The retailer is addressing this through Project Gigaton, which works with suppliers on energy, packaging, waste, products and nature. More than 4,300 suppliers reported progress in FY2026, with 187 million metric tons of CO2e in expected emissions avoided, reduced or sequestered.

Since 2017, cumulative reported results have topped 1.37 billion metric tons, exceeding Walmart’s original 1 billion-tonne goal for 2030. However, these figures are supplier-reported results and should not be treated as direct reductions in Walmart’s own Scope 3 inventory.

Walmart GHG emissions 2026

Looking Beyond Emissions to Protect Nature

Walmart’s sustainability work extends beyond emissions. In FY2026, Walmart said its suppliers and grantees reported sustainably managing, protecting or restoring 76.2 million acres of land and 3.68 million square miles of ocean.

The Walmart Foundation has invested more than $120 million since FY2021 in projects, research and other efforts linked to natural-resource protection. That included $30.5 million in FY2026. These programs matter to Walmart because forests, grasslands and oceans support the supply chains behind many products it sells.

The company says healthy natural systems can help protect water supplies, support climate resilience and reduce risks to long-term product availability.

Net-Zero Goal Has No Offset Shortcut

Walmart’s climate target stands out because the company does not plan to use carbon credit offsets to meet its operational zero-emissions goal. Its stated target is to achieve zero Scope 1 and 2 emissions across global operations by 2040 without relying on carbon offsets.

That means Walmart must continue cutting emissions from its own operations rather than simply balancing them with purchased credits.
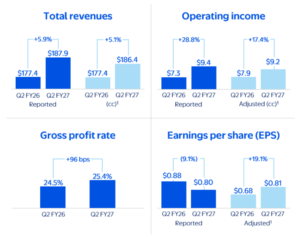
The bigger challenge remains Scope 3. Walmart’s estimated 635 million tonnes of CO2e in FY2026 shows how much of its climate footprint sits outside its direct operations.

Can Walmart Grow Without Growing Its Footprint?

Walmart’s Q2 FY2027 earnings show a company that continues to grow at enormous scale. Its latest ESG data also shows that it is making progress in cutting direct emissions.

The 7.5% year-over-year drop in Scope 1 and 2 emissions and 53.3% renewable electricity share are important steps toward its 2040 goal. Yet, the bigger test is the supply chain.

Project Gigaton has helped suppliers report more than 1.37 billion tonnes of cumulative expected emissions reductions, removals and avoided emissions, but Walmart’s growing business will continue to affect its overall value chain footprint.

As Walmart raises its sales outlook and expands e-commerce, the company will need to keep reducing emissions while growing. For one of the world’s largest retailers, that balance could have a major effect on the carbon footprint of global consumer goods.

The post Walmart (WMT Stock) Sales Rise as Emissions Fall, Putting Sustainability to the Test appeared first on Carbon Credits.