Morgan Stanley Finds Sustainable Funds Beat Traditional Peers With 4.9% Returns in H1 2026

Sustainable funds have become a growing part of the global asset-management market. These funds combine financial investments with environmental, social, and governance (ESG) factors. Their performance can vary widely based on the assets they hold, where they invest, and how fund managers define sustainability.

On September 10, Morgan Stanley said sustainable investment funds delivered higher median returns than traditional funds in the first half of 2026. Their assets under management also reached a record $4.24 trillion.

Sustainable Funds Outperformed Traditional Peers in H1 2026, But Investor Flows Remain Weak

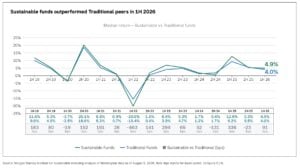
Morgan Stanley Institute for Sustainable Investing’s latest “Sustainable Reality” report, based on Morningstar data covering about 99,000 global funds, found that sustainable funds returned a median of 4.9% in the first six months of 2026. Traditional funds returned 4.0% over the same period.

Sustainable fund assets also grew during the period, reaching a new record. However, the data show that the market still faces challenges. Investor inflows recovered after a difficult 2025, but traditional funds attracted new money at a faster pace.

This means sustainable funds are growing in dollar terms, but their share of the overall fund market has continued to decline.
sustainable funds

AUM Hits Record $4.24 Trillion

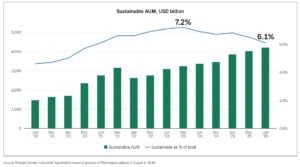
Global sustainable fund AUM increased 4.8% from the end of 2025 to $4.24 trillion at June 30, 2026. Most of that increase came from investment performance rather than new money flowing into the funds.

Sustainable funds now represent 6.1% of total fund assets, down from a peak of 7.2% in December 2023. Morgan Stanley said sustainable AUM has continued to grow steadily since 2022, but traditional funds have consistently recorded stronger net inflows in recent periods.

Some of the key figures from the report include:

  • $4.24 trillion: Sustainable fund AUM at the end of June 2026.
  • 4.8%: Increase in sustainable AUM from December 2025.
  • 6.1%: Sustainable funds’ share of total fund AUM.
  • 4.9%: Median sustainable fund return in H1 2026.
  • 4.0%: Median return for traditional funds.
  • $37.7 billion: Net inflows into sustainable funds during H1.
  • 2.5% vs. 0.9%: Traditional and sustainable fund inflows, respectively, as a percentage of prior year-end AUM.
sustainable funds morgan stanley

Equity Exposure Drove the Performance Gap

The performance advantage was closely linked to asset allocation.

Sustainable funds have a significantly higher allocation to equities, which were the strongest-performing major asset class during the first half. Equities accounted for 56% of sustainable funds, compared with 41% of traditional funds.

  • Sustainable equity funds generated a median return of 9.0%, slightly ahead of the 8.6% return for traditional equity funds. But the picture was very different in fixed income.
  • Sustainable fixed-income funds posted a median return of -1.3%, compared with +1.3% for traditional fixed-income funds.

Morgan Stanley said geography also played a role. About 80% of sustainable fixed-income funds invest globally or in Europe, where both sustainable and traditional fixed-income funds posted negative median returns.

Other asset classes also lagged traditional funds, with sustainable funds delivering a median return of 2.5% compared with 3.0%.

So, the overall outperformance does not necessarily mean that sustainability factors alone drove the higher returns. Morgan Stanley pointed to the mix of assets in sustainable funds, especially their higher exposure to equities, as an important factor.

EARLIER: Morgan Stanley, Citi and Bank of America Exit Net-Zero Alliance: What’s Next for Sustainable Finance?

Americas and APAC Lead Sustainable Fund Outperformance

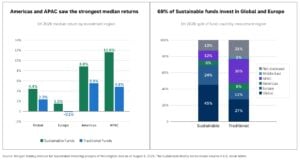
Sustainable funds also recorded higher median returns than traditional peers across all four major investment regions in H1 2026.

The strongest relative performance came from the Americas and Asia-Pacific, helping offset weaker results from funds focused on Europe and global markets. They nevertheless outperformed their traditional counterparts in those areas as well.

Geographic exposure remains important because sustainable funds are more concentrated in global and European investment mandates. About 69% of sustainable funds invest in global or European markets, compared with roughly 39% of traditional funds.

Europe-domiciled sustainable funds were particularly notable. They generated a median return of 3.9% in H1 2026, compared with 1.8% for traditional funds domiciled in Europe.
Inflows Rebounded, But Momentum Faded in Q2

Investor demand improved substantially from 2025, when sustainable funds experienced $75 billion of net outflows.

Sustainable funds attracted $37.7 billion in net inflows during H1 2026. But almost all of the recovery came during the first quarter.

Inflows reached $33.5 billion in Q1, before slowing sharply to only $4.2 billion in Q2. Traditional funds, meanwhile, attracted inflows equal to 2.5% of their prior year-end AUM, compared with 0.9% for sustainable funds.

The regional data show an uneven recovery:

  • Europe-domiciled sustainable funds attracted $43.9 billion in H1 inflows, equal to 1.2% of prior year-end AUM.
  • North American sustainable funds attracted $3.1 billion in Q2, ending more than three years of outflows.
  • Asia-domiciled sustainable funds recorded $7.5 billion of outflows, equivalent to 5.5% of prior year-end AUM.

Article 9 Funds Stabilize After Years of Outflows

The report also provides a look at Europe’s SFDR fund classifications.

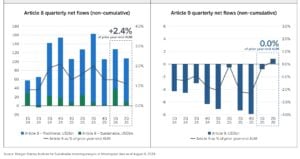
Article 8 funds recorded $242.2 billion in inflows during H1 2026. However, funds classified as sustainable by Morningstar accounted for only $45.8 billion, or 19%, of those flows.

  • Article 9 funds, meanwhile, recorded a small $0.8 billion inflow in Q2. That followed 10 quarters of outflows dating back to Q4 2023, leaving Article 9 flows roughly flat for the first half of 2026.
article 6

The data suggests that sustainable investing is not disappearing from global markets, but the growth story is becoming more nuanced. Assets continue to rise, performance has been competitive, and flows have returned to positive territory. At the same time, traditional funds are attracting capital at a faster rate, reducing sustainable funds’ share of the overall market.

The first half of 2026 therefore points to a sustainable investment market that is growing in dollar terms while facing a tougher test on investor demand and relative market share.

The post Morgan Stanley Finds Sustainable Funds Beat Traditional Peers With 4.9% Returns in H1 2026 appeared first on Carbon Credits.
U.S. CFTC Probes Voluntary Carbon Market as Scrutiny of Credit Quality Intensifies

U.S. CFTC Probes Voluntary Carbon Market as Scrutiny of Credit Quality Intensifies

The U.S. Commodity Futures Trading Commission (CFTC) is investigating parts of the voluntary carbon market, according to a Bloomberg report on September 15, 2026. The reported probe is looking at potentially problematic carbon projects and has reached beyond individual developers.

Investigators are seeking information from major U.S.-based carbon registries, validation and certification bodies, and third-party carbon rating firms, according to a person familiar with the matter cited by Bloomberg. The review is also expected to seek information through international channels.

The reported investigation comes as the voluntary carbon market faces continued questions over credit quality, project claims and weak demand.

BloombergNEF data cited in recent Bloomberg reporting shows annual voluntary carbon credit issuance fell 12% in 2025 from its 2021 peak. At the same time, the market is becoming more selective, with buyers increasingly focused on newer and higher-quality credits.

The CFTC has not publicly announced this new investigation. Its previous actions, however, show that the agency already has an enforcement role in voluntary carbon markets.

Probe Covers Projects and Market Gatekeepers

According to Bloomberg, the CFTC’s current review includes credits linked to orphan-well cleanup and projects designed to reduce emissions from deforestation and forest degradation. The focus on registries, validators, certifiers, and ratings firms is also significant.

These organizations play a key role in the voluntary carbon market. Registries record and issue credits. Validation and verification bodies check whether projects follow approved rules and whether claimed emissions reductions have been properly measured. Rating firms then assess the expected quality or risk of credits.

A problem at any point in this chain can affect the credibility of the resulting credit.

The investigation therefore appears broader than checking whether a single project made a false claim. It could look at how project information flows in the market. It can also check if the systems for creating, verifying, and assessing credits are functioning well.

Bloomberg reported that investigators are also considering information obtained under previous administrations, suggesting that the review may draw on earlier regulatory concerns.

CFTC Already Has a Carbon Market Enforcement Record

The CFTC is not new to voluntary carbon markets. In October 2024, it brought its first fraud cases involving voluntary carbon credits. The agency charged former carbon credit developer CEO Kenneth Newcombe with fraud and false or misleading reporting.

The CFTC also settled charges against CQC Impact Investors and its former chief operating officer. The agency found that CQC submitted false and misleading information. This led to the issuance of millions more credits than it should have received. CQC agreed to pay a $1 million civil monetary penalty and cancel or retire credits linked to the misconduct.

The case showed why regulators might step in. Most voluntary carbon credits are traded outside regular exchanges.

The CFTC has anti-fraud authority over the spot voluntary carbon market and broader oversight of derivatives based on carbon credits. CFTC officials have said that fraud in the underlying market can hurt the integrity of carbon credit futures and other derivatives.

Carbon Credit Derivatives Put Regulators on Guard

The CFTC’s role became clearer in 2024 when it issued guidance for exchanges listing voluntary carbon credit derivative contracts.

The guidance covered issues such as whether contracts could be manipulated and whether the underlying credits were sufficiently transparent and verifiable. The agency said high-integrity derivatives depend on credible underlying carbon credits.

However, the CFTC withdrew that guidance in September 2025.

The agency stated that current Commodity Exchange Act rules already cover voluntary carbon credit derivatives. They believe the separate guidance focuses too much on these products. The withdrawal did not remove the CFTC’s underlying regulatory authority over carbon derivatives.

The latest reported probe, therefore, comes after a significant change in how the CFTC approached its carbon market guidance.

The Voluntary Market Has Been Under Pressure

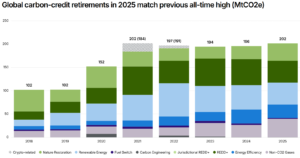
The investigation arrives during a difficult period for the VCM. MSCI estimates that 202 million tonnes of carbon credits were retired in 2025, roughly matching the record level reached in 2021. But demand has been relatively flat for several years, even as the market has shifted toward higher-quality credits.

Global carbon credit retirements
Source: MSCI

The primary carbon credit market was worth about $1.4 billion in 2025, according to MSCI. That value has stayed around the same level for four consecutive years. Yet, investment in future carbon supply is growing.

MSCI estimates that global capital in the carbon credit market hit a record $22 billion in 2025. This is a 72% increase from 2024 and over five times the amount in 2021. Much of that money is being directed toward future credit supply rather than immediate spot market demand.

This split is important. Investors may be willing to finance future projects, but buyers are increasingly selective about which existing credits they retire. That makes confidence in project quality even more important.

The market is also changing in terms of what buyers want.

MSCI found that about 10% of credits retired in 2025 were associated with carbon removals, while around 90% came from emissions reduction projects. Nature-based removals accounted for most removal retirements. Meanwhile, demand for renewable energy credits continued to weaken.

BloombergNEF also expects the market to shift toward higher-quality projects. Its 2025 long-term outlook predicts that global carbon credit supply might increase 20 to 35 times by 2050 from today’s levels.

future carbon credit supply

This growth depends on a market reset toward higher integrity. Its high-quality scenario projects theoretical supply of 2.6 billion tonnes in 2030 and 4.8 billion tonnes in 2050. 

That potential growth depends on trust. A broader regulatory review could affect which project types, methods, and market players can attract capital.

Registries Could Face Deeper Regulatory Scrutiny

Registries are central to the voluntary market because they track project records, credit issuance, ownership, and retirement. If regulators identify weaknesses in the information submitted to registries, the impact could extend beyond individual credits.

Projects may face additional scrutiny, while buyers could demand stronger evidence before purchasing credits. Validation and verification bodies could also face more pressure to show that their processes are consistent and reliable.

That could raise costs for some developers in the short term. But stronger checks could also make it easier for buyers to distinguish credible credits from projects with weak claims.

This matters a lot since the market is still split. It has different standards, methods, registries, and rating systems. CFTC officials have pointed out that fragmentation and missing information hurt price discovery and market trust.

Stronger Oversight Could Reshape Market Trust

A broader regulatory review could raise costs for developers, registries, validators, and ratings firms as they face stronger documentation and verification requirements.

Smaller projects may struggle with the added costs. But tighter oversight could also reduce low-quality credits and increase the value of projects with strong additionality, accurate measurement, and durable climate benefits.

The investigation comes as the voluntary carbon market faces flat demand and growing scrutiny. It does not suggest that all projects or credits in the categories being examined are problematic.

Ultimately, the impact may depend on whether stronger oversight improves data, verification, and transparency. For developers and buyers, the direction is clear: carbon credits will need stronger evidence behind the climate benefits they claim.

The post U.S. CFTC Probes Voluntary Carbon Market as Scrutiny of Credit Quality Intensifies appeared first on Carbon Credits.
Google Signs Record Carbon Removal Deal With Terradot for Brazil Rice Project

Google Signs Record Carbon Removal Deal With Terradot for Brazil Rice Project

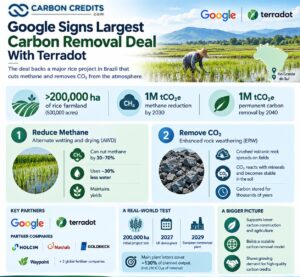
Google has signed its largest carbon removal purchase to date with climate company Terradot, backing a major project in southern Brazil that combines methane reduction from rice farming with permanent carbon removal.

The project will cover more than 200,000 hectares or 500,000 acres of rice farmland in Rio Grande do Sul. It will use two different climate solutions:

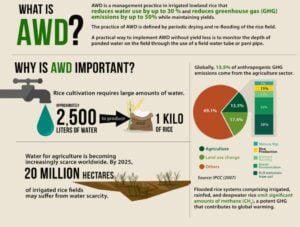
  • Alternate wetting and drying (AWD) to reduce methane from rice fields and
  • Enhanced rock weathering (ERW) to remove CO2 from the atmosphere.

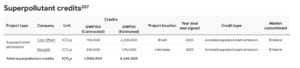
Google will purchase 1 million tonnes of CO2e of methane elimination by 2030 and another 1 million tonnes of permanent carbon removal by 2040. The two volumes should not be treated as 2 million tonnes of permanent carbon removal. Methane reduction and carbon dioxide removal have different climate effects and time scales.

Still, the agreement is significant. It is the largest ERW project publicly announced so far and the first project at this scale to combine near-term methane cuts with long-term carbon removal. 

Randy Spock, Head of Carbon Removal, noted:

“We hope this agreement will serve as a template to other buyers, suppliers, and governments aiming to maximize their climate impact. We look forward to continuing to help scale superpollutant elimination and carbon removal in tandem — so we can put an immediate and lasting dent in warming with the urgency the planet demands.”

One Rice Project, Two Climate Solutions

Rice farming is a major source of methane because fields are often kept flooded. Waterlogged soils create conditions that allow methane-producing microbes to thrive.

The first part of the Terradot project uses alternate wetting and drying, which periodically drains rice fields before they are flooded again.

The approach can cut methane emissions by about 30% to 70% without reducing yields, according to the International Rice Research Institute. It can also reduce water use by about 30%. That makes AWD attractive for farmers as well as carbon buyers.

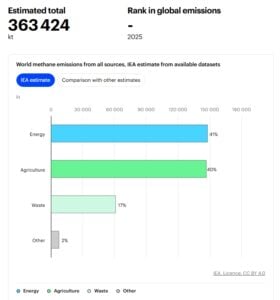
The approach also targets an important source of global methane. The Food and Agriculture Organization estimates that rice cultivation makes up about 8% of methane emissions from humans. In total, agriculture contributes around 40%.

Methane remains in the atmosphere for much less time than CO2, but it has a much stronger warming effect over shorter periods. Google is therefore treating methane reduction as a way to slow near-term warming while the second part of the project builds more permanent climate benefits.

Turning Volcanic Rock Into Carbon Removal

Terradot will also spread crushed volcanic rock across the same rice fields.

Over time, rainwater and soil moisture react with the rock’s minerals. This speeds up a natural process known as enhanced rock weathering, which removes CO2 from the atmosphere and stores the carbon in stable forms. This carbon removal is designed to last for thousands of years.

The approach is attractive because it does not require underground CO2 storage or large industrial capture equipment. Instead, it uses agricultural land as the setting for a natural mineral reaction.

However, ERW still faces challenges. Developers must measure the CO2 removed. They also need to consider emissions from mining and transporting rock. Finally, they must ensure that the carbon stays stored for the required time.

That makes measurement, reporting, and verification especially important as ERW projects become larger.

Brazil Offers ERW a Massive Testing Ground

Southern Brazil is well suited to Terradot’s model. Google says the region has warm and wet conditions that can help speed up rock weathering. Basalt quarries are also located relatively close to the rice-growing areas.

The scale of the project is significant. Brazil has about 1.5 million hectares of rice under cultivation, according to Google. That means the project’s more than 200,000 hectares could eventually cover about 13% of the country’s rice area if the approach is expanded.

Rio Grande do Sul is Brazil’s main rice-producing state. IBGE estimated about 932,870 hectares of rice area for the 2025 crop. The project’s 200,000-plus hectares would, therefore, equal roughly 21% of the state’s rice area, highlighting its potential scale.

The model could eventually be tested in other major rice-producing countries. Google says it is supporting research into how AWD could work across different rice systems worldwide, while Terradot sees Brazil as the first step toward wider expansion.

Google Is Increasing Its Carbon Removal Buying

The Terradot agreement builds on Google’s earlier support for ERW. In December 2024, Google agreed to purchase 200,000 tonnes of carbon removal credits from Terradot, to be delivered by the early 2030s. At the time, Google called it the largest ERW deal announced.

The new agreement is five times larger on the permanent carbon removal side, at 1 million tonnes.

Google has also expanded its focus beyond CO2 removal. In March 2026, the company pledged to spend at least $50 million through 2030 on projects targeting methane and other short-lived superpollutants.

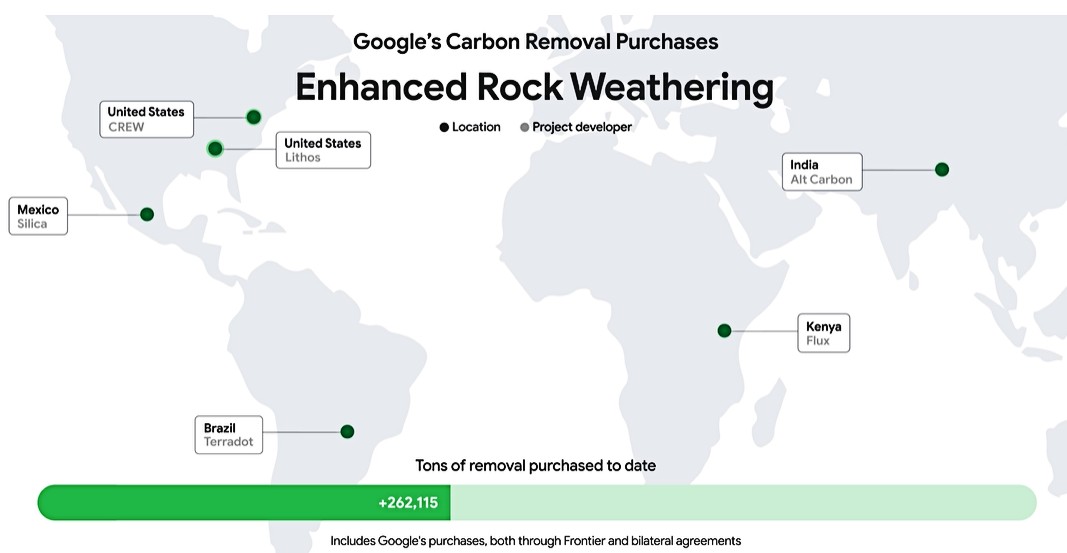
Google carbon removal purchases ERW
Source: Google

The Terradot deal brings those two strategies together.

AI Emissions Raise the Stakes for Google

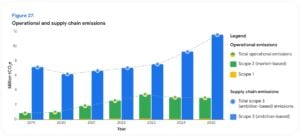
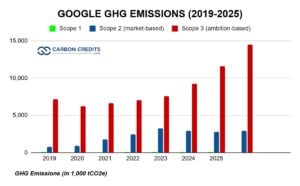
The purchase also comes as Google’s environmental footprint is changing quickly because of AI. Google’s 2026 Environmental Report says its electricity demand rose 37% in 2025, the largest annual increase in the company’s history. At the same time, its supply chain increased 25%, while operational emissions fell 2%.

Google ghg emissions 2019 to 2025

The company also signed agreements for more than 12 GW of new clean energy in 2025, bringing its cumulative clean energy procurement since 2010 to nearly 35 GW.

Google has a goal of reaching net-zero emissions across its operations and value chain by 2030. The company says carbon removal is one part of that strategy, alongside direct emissions reductions, clean energy procurement, and efficiency improvements.

This distinction matters. The Terradot purchase does not remove the need for Google to reduce its own emissions. Instead, durable carbon removal is intended to address residual emissions that remain difficult to eliminate.

Carbon Removal Demand Is Growing, But Delivery Matters

The Google deal arrives as the durable carbon removal market becomes more mature and more selective.

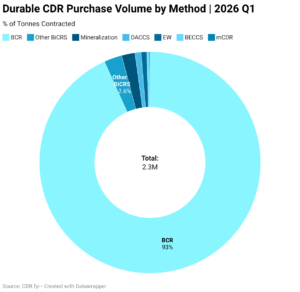
CDR.fyi says durable CDR purchases grew at a 151% compound annual rate between 2021 and 2025, excluding purchases from Microsoft and Frontier. Deliveries have also grown rapidly, but the market remains far smaller than the scale needed for global climate goals.

durable-cdr-purchase-volume-by-method-2026-q1
Source: CDR.fyi

The gap is substantial. The IPCC says climate pathways consistent with limiting warming to 1.5°C or 2°C require large-scale carbon removal later this century. Its assessed pathways include several gigatonnes of annual removal by 2050.

That is far above today’s market. This creates a major opportunity for technologies such as ERW, but also raises the bar for proving that each tonne is real and measurable.

The Cost Challenge Remains

One of the biggest hurdles for ERW is cost. The technology requires mining or sourcing rock, crushing it, and transporting it to farms. Those activities consume energy and can create emissions that must be included in the project’s carbon accounting.

Reuters reported that the cost of Terradot’s removal remains above the $100-per-tonne level often viewed as important for wider market adoption, although the company expects costs to fall as operations scale.

Large purchase agreements can help solve part of this problem. Long-term commitments provide developers with demand visibility, which can support investment in equipment, project development and measurement systems.

Google Terradot carbon removal deal

Can Rice Fields Become the Next Carbon Removal Platform?

The Terradot agreement stands out because it combines short-term methane reduction with long-term carbon removal in the same farming system. AWD can reduce methane emissions quickly. ERW takes longer to remove CO2 but can store carbon for a much longer period.

Google says the model is designed to become a blueprint for other rice-growing regions. For the carbon removal market, however, the deal sends a strong signal.

Large corporate buyers are moving beyond small pilot purchases and backing larger projects designed to deliver millions of tonnes over time.

If Terradot can deliver at the planned scale, the project could help show how agricultural land can become a platform for both methane reduction and durable carbon removal—and provide a model that could be replicated across major rice markets worldwide.

The post Google Signs Record Carbon Removal Deal With Terradot for Brazil Rice Project appeared first on Carbon Credits.
Oracle (ORCL) Bets on AI While its Project Jupiter Redefines the Data Center Sustainability Playbook

Oracle (NYSE: ORCL)) latest earnings show how fast AI is changing its cloud business. They also point to a growing challenge. The company needs to build more data centers to meet AI demand. At the same time, it must manage the emissions, electricity, and water that come with that growth. The growth creates a major opportunity for Oracle.

But it also raises a key question: how much power and water will the company need to support the next phase of AI growth?

Oracle’s AI Cloud Surge Powers a Record Quarter

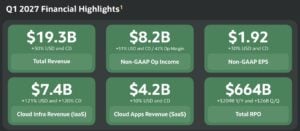
Oracle reported fiscal first-quarter 2027 revenue of $19.3 billion, up 30% from a year earlier. Cloud revenue rose 62% to $11.6 billion. Cloud infrastructure revenue more than doubled, rising 121% to $7.4 billion.

GAAP earnings per share increased 55% to $1.56. Adjusted EPS rose 30% to $1.92. Net income reached $4.76 billion, up 63%.

The company also added more than $30 billion in AI cloud contracts during the quarter. Its remaining performance obligations reached $664 billion.

Additionally, it delivered 850 megawatts of additional data center capacity during the quarter. It said demand for AI training and inference services still exceeds available supply.

oracle Q1 2027
Source: Oracle

ORCL Stock Faces the Cost of AI Expansion

The strong earnings came as Oracle continued to spend heavily on infrastructure. The company invested $28.5 billion in capital expenditures during the first quarter.

Oracle expects fiscal 2027 capital spending to reach about $90 billion to $95 billion. Free cash flow was negative $5 billion in the first quarter as the company continued to expand its cloud infrastructure.

This spending also has a sustainability impact.

Every new data center requires power, cooling systems, construction materials, and water. The efficiency of those systems will affect both Oracle’s environmental footprint and the cost of expanding its cloud business.

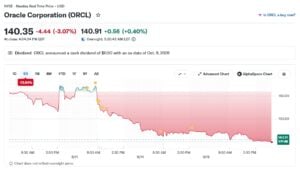
On September 15, ORCL closed at about $140.35, down 3.07% for the session. Oracle shares have gone down 16.5% over five sessions.

oracle stock
Source: Yahoo Finance

Oracle’s Net-Zero Plan Covers Its Supply Chain

Oracle has set a net-zero emissions target for 2050. It also plans to cut Scope 1, Scope 2, and Scope 3 emissions by 50% from a 2020 baseline by 2030.

The company says it will focus first on direct emissions cuts. It plans to use high-quality carbon offsets for no more than 10% of its base-year emissions that it cannot eliminate directly.

And the Exponential Roadmap Initiative has approved Oracle’s targets.

oracle net zero
Source: Oracle

Scope 1, 2, and 3 Data

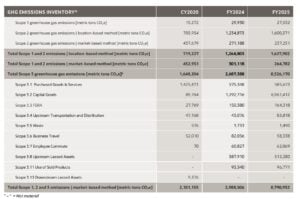
Oracle’s latest emissions data also shows the impact of its rapid infrastructure growth. It reported 27,532 metric tons of Scope 1 emissions in FY2025. That was down from 29,930 tons in FY2024.

Market-based Scope 2 emissions also fell. They declined to 237,251 tons from 271,188 tons.

However, Scope 3 emissions moved in the opposite direction. They were 8.53 million metric tons in FY2025. That compares with 2.69 million tons in FY2024.

Capital goods made up about 6.96 million tons of the FY2025 Scope 3 total. This category includes emissions linked to infrastructure and equipment purchases.

oracle emissions
Source: Oracle
  • Overall, Oracle reported 8.79 million metric tons of combined Scope 1, 2 and 3 emissions on a market-based basis in FY2025. The figure was 2.99 million tons in FY2024.

The increase shows how infrastructure spending can affect a cloud company’s wider carbon footprint.

Renewable Power Is Expanding

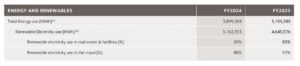
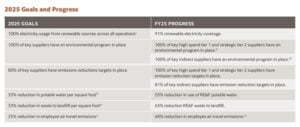
In the sustainability report, renewable electricity covered 92% of electricity used in its cloud operations in FY2025. That was up from 88% in FY2024.

Across its real estate and facilities, renewable electricity coverage reached 85%.

More importantly, Oracle has also set a target to reduce carbon emissions per megawatt of IT capacity by 20% by 2030. As AI workloads require more computing power, improving the emissions intensity of each megawatt will become more important.

oracle renewable
Source: Oracle

Water Is Becoming a Bigger Data Center Issue

Energy gets much of the attention surrounding AI data centers, but water is becoming another important constraint.

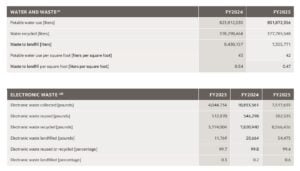
  • It used about 802 million liters of potable water in FY2025, down from approximately 824 million liters in FY2024. The company also recycled about 378 million liters of water during the same year.
  • Potable water use per square foot declined slightly to 42 liters from 43 liters.

Oracle’s sustainability strategy now includes a goal of reducing water use by 50% in water-stressed regions by 2035, relative to a 2025 baseline. The company also aims to reduce carbon emissions per megawatt of IT capacity by 20% by 2030.

The targets are becoming particularly relevant as Oracle develops larger AI-focused facilities.

oracle water
Source: Oracle

Project Jupiter Takes a Different Approach to Water

Oracle’s Project Jupiter in New Mexico provides a closer look at how the company is trying to address the environmental footprint of hyperscale computing.

The 1,400-acre campus in Doña Ana County is being developed as a large-scale AI and cloud data center. Oracle has shifted the project’s power strategy toward Bloom Energy fuel-cell technology, replacing an earlier design based on gas turbines and diesel generators.

It says the fuel-cell system will significantly reduce emissions and water use compared with conventional combustion-based generation.

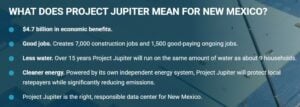
Water is especially important to the project because of conditions in southern New Mexico. Oracle says Project Jupiter will use non-potable water and that, averaged over 15 years including the initial fill, its water use will be equivalent to less than nine single-family homes.

The company is also trying to offset more water than the project itself consumes through local conservation.

oracle project jupiter
Source: Project Jupiter

Oracle Wants to Save More Water Than Jupiter Uses

In August, Oracle also announced a partnership with agricultural technology company Arable to improve irrigation efficiency in the Rio Grande-Bravo watershed.

  • The initiative is expected to conserve approximately 21 million gallons of water annually.
  • This amount is more than 20 times the water required to operate Project Jupiter’s cooling and power systems.

Arable will use field sensors, weather information, and crop data to help farmers make more precise irrigation decisions. Oracle says an independent third party will validate the water savings using a recognized methodology, with validation reports made public.

Oracle has also committed $50 million toward local water and wastewater infrastructure in Doña Ana County.

The approach moves beyond simply reducing data center water consumption. It combines operational efficiency with investment in watershed-level conservation, which could become increasingly relevant as data center construction expands into water-stressed regions.

Expanding a Cleaner Power Mix for Jupiter

Oracle’s sustainability strategy around Project Jupiter also extends to electricity.

Recently, the company issued a request for proposals for 2 gigawatts of new renewable energy capacity in New Mexico, including solar, wind, and geothermal projects. Oracle said the initiative is intended to support Project Jupiter’s goal of achieving 100% carbon-free energy matching by 2031.

As per reports, Oracle is also planning a public environmental dashboard for Project Jupiter. The dashboard is expected to provide information on water use, emissions, heat, air, noise and light once the facility is operational.

It also plans twice-yearly assessments by an independent third party comparing performance against baseline conditions and relevant standards.

For a company expanding its cloud infrastructure at triple-digit rates, greater transparency could become increasingly important.

The Bottom Line: AI Growth Is Raising the Sustainability Stakes

Oracle’s Q1 results demonstrate the scale of the AI infrastructure opportunity. Cloud infrastructure revenue more than doubled, the company’s backlog reached $664 billion, and hundreds of megawatts of additional data center capacity were brought online.

Yet the same expansion is increasing Oracle’s exposure to energy consumption, construction-related emissions, water availability and infrastructure costs.

The company’s sustainability targets therefore sit alongside a much larger business transformation. Oracle is attempting to grow its AI and cloud infrastructure while reducing the emissions intensity of its operations, expanding renewable power and addressing water use at the local watershed level.

For investors watching ORCL, the story is no longer simply about how fast Oracle can build data centers. It is also about how efficiently and sustainably the company can power them.

As AI demand continues to drive Oracle’s cloud growth, energy and water management could become increasingly important measures of how the company’s infrastructure expansion develops over the next decade.

The post Oracle (ORCL) Bets on AI While its Project Jupiter Redefines the Data Center Sustainability Playbook appeared first on Carbon Credits.
Can UK-US Fusion Partnership Turn AI-Powered Research Into Clean Energy?

Can UK-US Fusion Partnership Turn AI-Powered Research Into Clean Energy?

The UK and US are expanding their partnership on fusion energy, with a focus on artificial intelligence (AI), advanced computing and simpler rules for developing fusion plants. The agreements were announced at the Global Fusion Policy Summit in London on September 14, 2026.

The partnership links the UK Atomic Energy Authority (UKAEA) with the US Department of Energy’s Princeton Plasma Physics Laboratory (PPPL). The two countries will also work together on fusion safety and regulation.

The move comes as both countries step up spending on fusion and try to turn decades of research into working power plants.

The UK has committed more than £2.5 billion to fusion over five years. The US has set out a plan aimed at supporting pilot plants and commercial fusion power in the mid-2030s. 

AI Could Speed Up Fusion Research

One part of the partnership will link two advanced computers: the UKAEA’s SUNRISE supercomputer and PPPL’s STELLAR-AI system.

The planned SUNRISE–STELLAR-AI Federation will allow researchers in both countries to train AI models using data from fusion experiments. The goal is to improve reactor designs, better understand plasma, and speed up research.

The UK has committed £45 million to SUNRISE. The system is expected to use about 1.4 megawatts of power and become one of the world’s most powerful computers focused on fusion research. 

UKAEA supercomputing facility
Source: United Kingdom Atomic Energy Authority

Researchers could also use these systems to create digital twins of fusion plants. These virtual models allow engineers to test designs and changes before trying them on real equipment. This could save time and reduce the cost of testing.

The partnership also creates an interesting link between AI and fusion. AI needs large amounts of electricity, while fusion could eventually provide steady, low-carbon power for data centers and other energy-intensive industries.

Both Countries Want Clearer Fusion Rules

The UK and US also want closer cooperation on fusion regulation and safety standards. The two countries said they will work toward rules that reflect the different risks of fusion compared with traditional nuclear fission.

Clear rules matter because fusion plants will require billions of dollars in investment. Developers need to know how projects will be licensed and operated before they can commit large amounts of money.

The UK has already created a dedicated regulatory framework for fusion. It is also developing a Fusion National Policy Statement and a new market framework for future fusion plants.

Minister for Energy, Michael Shanks, stated:

“By strengthening our partnership with the US, we’re accelerating the race to commercial fusion, turning cutting-edge research into economic growth and cementing Britain’s position as a world leader in fusion energy.”

The US is also working to speed up its approval process as private fusion companies move closer to commercial projects. FCDO Minister for the Americas, Chris Elmore, said:

“By bringing together world-leading expertise in fusion, artificial intelligence and advanced computing, we’re helping British businesses and researchers access the investment, knowledge and international partnerships needed to succeed in the industries of the future.”

Britain Bets £1.3 Billion on Its 2040 Fusion Plant

The UK’s main project is STEP Fusion, a prototype power plant planned for West Burton in Nottinghamshire. The plant is expected to begin operating in 2040. It is designed to show that a fusion plant can produce net electricity for the grid and make its own tritium fuel. 

The UK has allocated £1.3 billion for the next stage of STEP. The wider five-year fusion programme also includes £180 million for the LIBRTI programme, which is working on tritium fuel, and £110 million for industry support and commercialization. 

fusion industry global
Source: Fusion Industry Association Report 2025

The UK government estimates the global fusion market could be worth between £3 trillion and £12 trillion by the end of the century.

US Targets Commercial Fusion in the 2030s

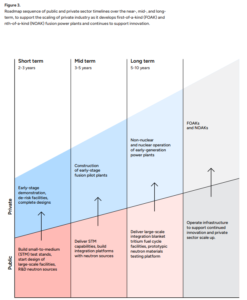
The US has set a faster target. The Department of Energy’s Fusion Science and Technology Roadmap, finalized in June 2026, aims to support pilot plants and commercial fusion power in the mid-2030s. It covers research, technology, infrastructure, skills, and commercial development.

The US plan is also designed to support the growing private fusion industry.

Private companies are developing several different fusion technologies, including magnetic and inertial fusion. The UK-US partnership could help these companies access more research, computing power, and technical expertise.

Department of Energy's Fusion Science and Technology Roadmap
Source: Department of Energy

Tritium Could Be Fusion’s Biggest Fuel Challenge

Fusion works by joining light atoms at extremely high temperatures. This releases energy without burning coal, oil, or gas.

That means fusion does not create CO2 from fuel combustion during operation. It also has a potential advantage over wind and solar: fusion plants could produce power continuously instead of depending on weather.

That makes fusion a possible source of firm, low-carbon electricity for future power grids. But commercial fusion power does not yet exist at scale.

Scientists and engineers still need to solve major challenges. These include keeping the plasma stable, protecting reactor parts from intense radiation, producing enough fuel, and operating reactors reliably for long periods.

  • One of the key problems is tritium, a radioactive form of hydrogen.

Many planned fusion systems will use a mixture of deuterium and tritium as fuel. Future plants therefore need a reliable way to produce and recover tritium during operation.

The UK’s LIBRTI programme is working on this challenge. Its goal is to develop systems that can produce enough tritium to support future fusion reactors. Solving this problem will be important before fusion can become a large commercial energy source.

A New Fusion Industry Is Taking Shape in Britain

The partnership comes as electricity demand is rising from data centers, manufacturing, electric vehicles and other technologies. Renewable energy could provide much of the new clean electricity, but power systems also need reliable generation, storage and stronger grids.

Fusion could eventually work alongside wind and solar by providing steady low-carbon power. It is not a replacement for renewable energy today.

The technology still needs to prove that it can produce electricity reliably and at a competitive cost. For now, the focus is on research, testing, and demonstration projects.

The UK is also working with companies and research groups on materials and other parts needed for future reactors. A separate £2.63 million project involving the University of Birmingham, the Electric Power Research Institute and industry partners will study fusion reactor shielding materials.

Japan’s Kyoto Fusioneering has also committed up to £3 million to Project ALBION, which supports materials development for STEP. These projects can help build a supply chain before commercial fusion plants are ready.

The Race Now Moves From the Lab to the Grid

Fusion has spent decades in the research stage. That is now starting to change. Fusion is moving from basic research toward commercial development.

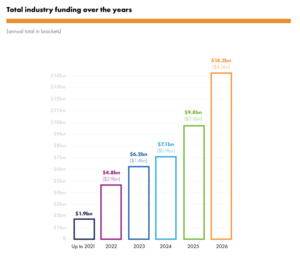
Total industry funding over the years
Source: Fusion Industry Association.

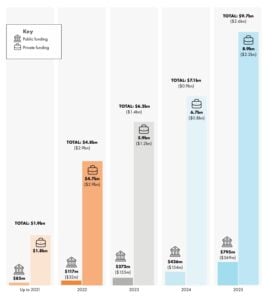
Private fusion companies have raised a cumulative total of $14.24 billion globally as of July 2026, according to the Fusion Industry Association. Private funding has grown sevenfold since 2021, showing how quickly investor interest is increasing.

Governments are also putting more money into pilot plants, while private companies are raising capital to develop commercial systems. 

The UK-US partnership tackles several of the main barriers at once. AI and supercomputers could speed up research. Shared rules could make future projects easier to approve. Cooperation could also help companies develop common technologies and standards.

For the energy transition, the potential is large: a reliable, low-carbon power source that could eventually help meet rising electricity demand from AI, industry, and electrification.

The next milestone will be turning these partnerships and research programmes into working pilot plants—and proving that fusion can move from the laboratory to the power grid. 

The post Can UK-US Fusion Partnership Turn AI-Powered Research Into Clean Energy? appeared first on Carbon Credits.
Vateris Secures €50M in Offtake Deals for Carbon-Negative Minerals

Vateris Secures €50M in Offtake Deals for Carbon-Negative Minerals

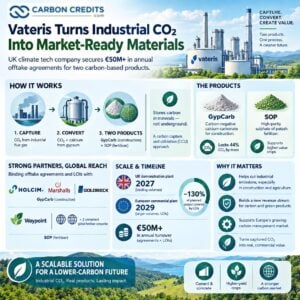
UK climate technology company Vateris has secured binding offtake agreements and letters of intent worth more than €50 million in annual turnover with six international construction and fertilizer companies. The deals include two products that turn industrial carbon dioxide (CO2) into minerals.

The first is GypCarb, a carbon-negative calcium carbonate used in construction. The second is sulphate of potash (SOP), a high-purity fertilizer. The partners include Holcim, Marshalls and Goldbeck for GypCarb, while Waypoint and two unnamed global fertilizer companies have committed to SOP.

The agreements connect binding volumes from a UK demonstration plant planned for 2027. They also include letters of intent for larger volumes from a European commercial plant planned for 2029.

The main plant letters cover about 130% of its planned output, according to Vateris. This deal is important because it gives a carbon utilization technology a potential customer base before full commercial-scale production begins.

Turning Industrial CO₂ Into Commercial Materials

Vateris, formerly known as Concrete4Change, uses a process designed to capture CO2 from industrial flue gas and convert it into useful mineral products. Its first product, GypCarb, is an engineered form of vaterite-based calcium carbonate.

The company says the product permanently locks 44% of CO2 by mass into the mineral and is designed as a drop-in additive for cement and concrete.

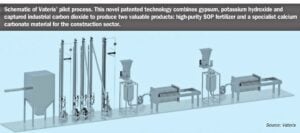
The process uses calcium from gypsum and converts it, along with captured CO2, into calcium carbonate. The remaining sulphate is used to make high-purity SOP fertilizer. This creates two products from the same process while storing captured carbon in minerals.

That is different from conventional carbon capture and storage, where CO2 is captured and then transported to an underground storage site. Vateris instead uses carbon capture and utilization (CCU) to turn the carbon into materials that can be used commercially.

Vateris carbon capture

GypCarb Targets One of Industry’s Biggest Emitters

The construction industry is a major target because cement and concrete have large carbon footprints. The International Energy Agency reports that CO2 emissions from cement production are still higher than in 2015. The sector must cut emissions faster to meet net-zero goals.

The IEA points to greater use of alternative materials, improved efficiency, and carbon capture among the solutions. GypCarb is designed to address two parts of this problem.

First, the product stores captured CO2 permanently in mineral form. Second, Vateris says its reactive calcium carbonate can improve concrete performance and reduce the amount of cement needed. 

The company reported strong results from testing with Heidelberg Materials. One trial showed a 40% increase in one-day compressive strength using a small amount of GypCarb. Further testing is aimed at reducing cement content while maintaining performance.

With cement production responsible for significant industrial emissions, materials that can reduce cement use while storing CO2 could offer a second source of emissions savings.

Construction Companies Are Already Signing Up

The new agreements provide early commercial validation for the technology. Holcim, Marshalls and Goldbeck have committed to GypCarb for cement, concrete and other construction applications.

Vateris partners
Source: Vateris

Goldbeck has been working with Vateris on integrating the product into its precast concrete operations. The companies say the technology has shown potential to reduce cement use while maintaining early strength.

First GypCarb deliveries to Goldbeck are targeted for late 2027. This matters because industrial climate technologies often struggle to move from pilot testing to commercial markets.

An offtake agreement can give a technology developer a clearer route to revenue while giving customers early access to a new material. However, the €50 million figure should be read carefully.

It represents annual turnover associated with the agreements and letters of intent, not cash already received by Vateris. The binding agreements cover demonstration-plant volumes, while the larger main-plant commitments are currently non-binding letters of intent.

Fertilizer Gives Captured CO₂ a Second Market

Vateris is also targeting agriculture through SOP. Sulfate of potash is a potassium and sulphur fertilizer used in higher-value crops. The company plans to produce a high-purity version using the sulphate left over from its carbon mineralization process.

This gives the company a second commercial market and reduces its reliance on construction materials. The timing could also be favorable for fertilizer supply chains.

The European Commission says the EU remains dependent on imports for mineral fertilizers and key raw materials. It estimates that the bloc imports about 40% of its potassium fertilizers.

That dependence has become more important as geopolitical disruptions have affected global fertilizer and energy markets. A European source of SOP made from industrial waste streams could thus offer both carbon benefits and greater supply resilience.

Europe’s Carbon Management Market Is Expanding

Vateris is also entering a wider European push to build carbon management infrastructure.

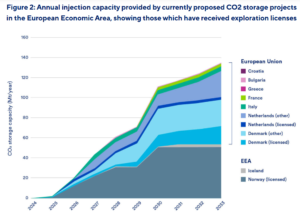
The EU has set a target of at least 50 million tonnes of annual CO2 injection capacity by 2030 for permanent geological storage. The European Commission expects around 280 million tonnes of CO2 to need capture by 2040 and around 450 million tonnes by 2050 to support climate neutrality.

EU Annual injection capacity
Source: Clean Air Task Force

Those targets focus mainly on carbon capture and storage, but they also support a broader market for carbon management, including technologies that use captured CO2.

The EU is funding carbon capture, utilization, and storage through its Innovation Fund, including projects in cement, chemicals, and other hard-to-abate industries. Vateris could benefit from that growing market if it can show that its process works at much larger industrial scale.

From Pilot Plant to Commercial Scale

Vateris raised its total funding to $10 million after a financing round involving Holcim Maqer Ventures and Kiilto Ventures in April 2026. The company has since shifted its focus from pilot validation toward industrial scale-up.

Its planned UK demonstration plant is expected to begin production in 2027. A larger European first-of-a-kind commercial plant is targeted for 2029. The current offtake agreements are designed to support this transition.

Vateris says the demo plant will show the technology works at a commercial scale. The main plant will supply larger volumes for construction and agricultural customers.

  • The new agreements show a strong signal: potential customer demand is already higher than the planned output for Vateris’ first full-scale European plant.

The letters of intent cover about 130% of the plant’s expected production, according to the company. That is encouraging, but it is not yet guaranteed revenue.

Letters of intent aren’t binding purchase agreements. The commercial plant still needs financing, construction, and a successful technical scale-up. The demonstration plant will, therefore, be a critical milestone.

Vateris Carbon Negative Minerals

If Vateris proves it can turn industrial CO2 into cost-effective construction and fertilizer products, it could build a new business model around carbon use.

The Next Test Is Turning CO₂ Into Revenue

The broader significance of Vateris is its attempt to change the role of captured CO2. The company isn’t just viewing industrial CO2 as waste to bury. Instead, it aims to convert it into a raw material for products that already have established markets.

The new agreements show that large industrial companies are willing to explore this model. The next test is scale.

A successful demonstration plant in 2027 could help turn the more than €50 million annual commercial pipeline into actual sales and support the larger European plant planned for 2029.

For the carbon market, the story is also a reminder that decarbonization will not rely on one solution. Permanent storage, carbon removals, carbon capture, and carbon utilization can each play different roles.

Vateris is betting that one of those roles will be to turn industrial emissions into materials that Europe already needs.

The post Vateris Secures €50M in Offtake Deals for Carbon-Negative Minerals appeared first on Carbon Credits.
FedEx (FDX) Locks In 20 Million Gallons of SAF Across U.S. Air Network

FedEx is expanding its sustainable aviation fuel (SAF) procurement as the air-cargo company works to reduce emissions from the part of its business that produces the largest share of its direct carbon footprint.

The company announced on September 15 that new agreements are projected to secure more than 20 million gallons of neat SAF through 2027. The agreements cover five U.S. airports:

  • Newark Liberty International Airport
  • Oakland International Airport
  • Miami International Airport
  • John F. Kennedy International Airport
  • Dallas-Fort Worth International Airport

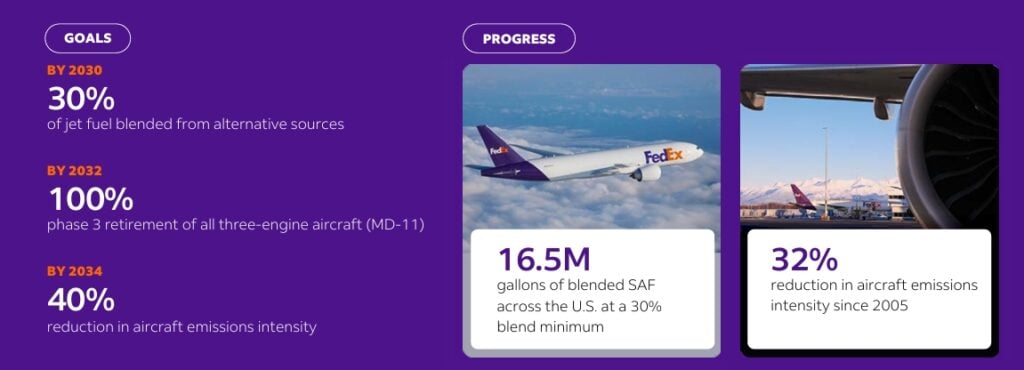
Depending on the airport, the fuel will be supplied at blend ratios ranging from 30% to 50%. FedEx said the agreements build on about 5 million gallons of neat SAF secured in 2025, which supported the deployment of 16.5 million gallons of blended SAF across five U.S. airports.

FedEx’s 2040 Climate Target

The expansion comes as FedEx works toward its goal of carbon-neutral operations by 2040. The target covers Scope 1 and Scope 2 emissions from its operations as well as Scope 3 emissions associated with contracted transportation.

It also includes SAF, aircraft modernization, and operational efficiency as part of its wider climate strategy.

Karen Blanks Ellis, chief sustainability officer and vice president of Environmental Affairs at FedEx, said:

“SAF is one of the most impactful decarbonization solutions available to aviation today and an important part of our approach to reducing emissions. For the market to grow, supply needs to be reliable, affordable, and sustainable. Expanding our procurement allows us to employ more SAF in our network while bolstering the demand for greater production and scale.”

Aviation Drives FedEx’s Emissions

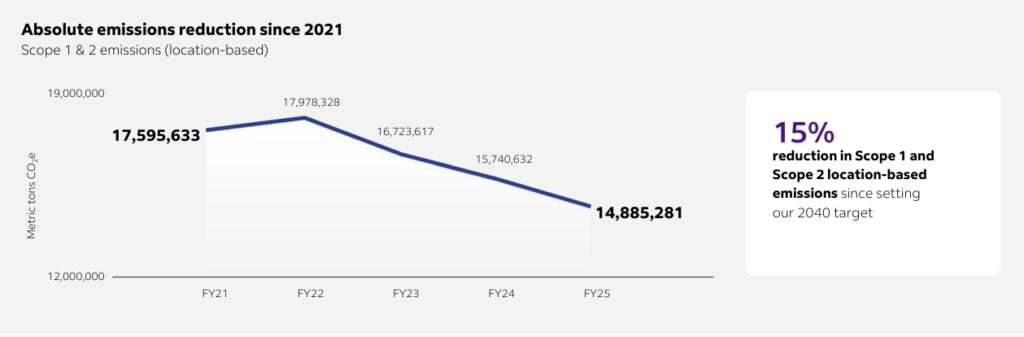
FedEx reported 13.93 million metric tons of CO2e in Scope 1 emissions for FY2025. These direct emissions come mainly from aircraft, vehicles, and facilities.

The company reported another 952,744 metric tons of Scope 2 emissions, primarily from purchased electricity. Its reported Scope 3 emissions totaled 14.88 million metric tons of CO2e.

  • Together, the three categories totaled 29.76 million metric tons of reported emissions in FY2025. FedEx notes that its Scope 3 inventory continues to expand, so the figure does not represent every possible Scope 3 category.
fedex emissions
Source: FedEx

Aviation remains the biggest contributor to direct emissions. Owned aircraft accounted for about 79% of FedEx’s Scope 1 footprint, while aviation fuel use generated roughly 11 million metric tons of CO2e during the year.

emissions
Source: FedEx

The company also reports emissions from conventional air pollutants. In 2025, its operations produced about 71,432 metric tons of nitrogen oxides (NOx), 10,773 metric tons of sulfur oxides (SOx), and 640 metric tons of particulate matter (PM10). These pollutants are separate from FedEx’s greenhouse-gas emissions inventory.

Fleet Modernization Cuts Fuel Use

FedEx is not relying on SAF alone to reduce aviation emissions. The company is replacing older aircraft with newer, more fuel-efficient models and optimizing fleet operations. It operates nearly 700 aircraft and is retiring less-efficient three-engine aircraft. The company plans to complete that retirement by 2032.

Aircraft modernization avoided approximately 1.15 million metric tons of CO2e in FY2025, according to FedEx’s 2026 Corporate Responsibility Report. The company also saved more than 120 million gallons of jet fuel through aircraft modernization and related efficiency measures.

Those savings have also reduced operating costs. FedEx estimates that its aircraft modernization program saved about $284 million in fuel costs during FY2025.

Its Fuel Sense program provides another source of efficiency. The program uses operational improvements, flight planning, and technology to reduce fuel consumption across the air network.

To sum up, FedEx has reduced aircraft emissions intensity by 32% from its 2005 baseline and now targets a 40% reduction by 2034.

SAF Takes a Larger Role

The latest agreements increase the scale of SAF in FedEx’s U.S. network while addressing one of the industry’s biggest challenges: supply.

As mentioned before, the new contracts will secure more than 20 million gallons of neat SAF through 2027. Because the fuel will be blended before use, more finished blended fuel will enter the network.

FedEx has set a target of sourcing 30% of its jet fuel as blended fuel from alternative sources by 2030.

SAF FedEX

The company has already expanded SAF use at several major hubs. Its 2025 agreements supported SAF deployment at airports including Los Angeles, Chicago O’Hare, Miami, Dallas Fort Worth, and New York-JFK. FedEx also secured more than 3 million gallons of blended SAF from Neste for Los Angeles.

The company says SAF supply needs to become more reliable, affordable, and sustainable for the market to scale. Its latest agreements increase demand while allowing FedEx to build SAF into regular network operations rather than treating it only as a pilot project.

For FedEx, the latest SAF agreements add another piece to a broader effort to decarbonize a logistics network that depends heavily on aviation. New aircraft can reduce fuel consumption, operational improvements can lower fuel demand, and SAF can replace part of the fossil jet fuel used across the network.

The challenge is scaling all three at the same time. FedEx’s latest agreements show that SAF is moving from limited deployments toward a more significant role in the company’s long-term aviation emissions strategy.

Now let’s look inside the SAF market in the content below:

In the U.S. SAF Market Is Growing, But Supply Still Trails Demand

FedEx’s latest agreements come as the sustainable aviation fuel market expands in the U.S. and globally, although production remains a small fraction of aviation fuel demand.

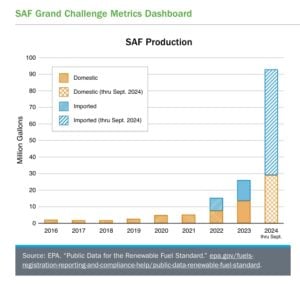
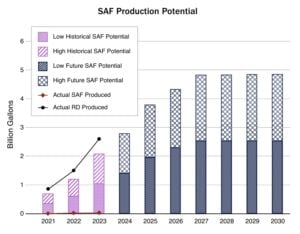
DOE data revealed that U.S. production has increased sharply, but actual output remains well below that target. Federal agencies reported that domestic SAF production reached 30 million gallons in the first three quarters of 2024, up from 5 million gallons in 2021.

US SAF production

The government is targeting 3 billion gallons of domestic SAF production a year by 2030 and 35 billion gallons by 2050. The 2030 target would equal about 10% of projected U.S. jet-fuel demand.

saf
Source: Source data for the future potential volumes will be available in a forthcoming ASCENT 01 publication. Brandt, K; Wolcott, M. (2024). RD data source: U.S. Energy Information Administration. SAF data source: EPA. “Public Data for the Renewable Fuel Standard.”

More recent EIA data also shows the U.S. is becoming an important supplier to international markets. In the second half of 2025, the U.S. exported nearly 50,000 barrels per day of renewable diesel and other biofuels, a category that includes SAF. Those exports represented about 20% of combined production in the category, with Canada and Europe taking most of the volumes.

Global SAF Supply Remains Small

Globally, SAF production is growing but has not kept pace with the industry’s ambitions.

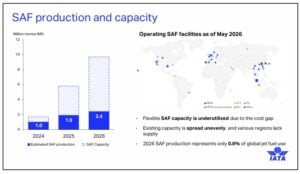
The International Air Transport Association (IATA) estimates that global SAF production reached about 1.9 million metric tons in 2025, roughly double 2024 production. That still represented only about 0.6% of total jet-fuel consumption. IATA expects production to rise to approximately 2.4 million metric tons in 2026, but that would cover only about 0.8% of aviation fuel demand.

  • The gap between production and potential demand remains significant. IATA estimates that airlines will spend about $4.3 billion on SAF in 2026, even though the fuel will supply less than 1% of global aviation fuel needs.

IATA SAF

For FedEx, the latest commitment to secure more than 20 million gallons of neat SAF through 2027 fits into this broader market expansion. The company is effectively locking in a portion of future supply while SAF production capacity continues to scale.

The U.S. has the production targets and project pipeline to become a major SAF market, but the gap between announced capacity and actual production remains important. Globally, the same issue is even more pronounced: SAF output is growing rapidly from a small base, while aviation fuel demand remains measured in hundreds of millions of tonnes.

The post FedEx (FDX) Locks In 20 Million Gallons of SAF Across U.S. Air Network appeared first on Carbon Credits.
BlackRock-Backed Skyborn Secures $2.4B for Major German Offshore Wind Farm

BlackRock-Backed Skyborn Secures $2.4B for Major German Offshore Wind Farm

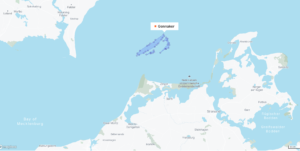
Skyborn Renewables has reached financial close on the Gennaker offshore wind farm, securing a €2.1 billion financing package, or roughly $2.4 billion, for one of Germany’s largest new renewable energy projects. The project, located in the German Baltic Sea, will have up to 976.5 megawatts (MW) of capacity. More than €3 billion in total investment is expected to be mobilized.

Gennaker will start commercial operations by the end of 2028. It aims to generate enough electricity for about 1 million German households.

The financing comes from 16 commercial lenders and the European Investment Bank (EIB). The EIB previously approved up to €700 million for the project, whose total cost was estimated at about €3.1 billion.

Nicola Beer, Vice-President of the European Investment Bank (EIB), noted:

“Gennaker shows Europe turning its clean‑energy goals into real benefits for people. Built off the coast of Mecklenburg‑Western Pomerania, where winds are strong and reliable, this wind farm will help Germany produce more of its own power and lower dependence on imported energy. Once running, it will supply clean electricity to around one million homes and businesses across the country, helping to bring down energy bills from Schwerin to Munich.”

The deal is also significant for BlackRock. Skyborn is a portfolio company of Global Infrastructure Partners (GIP), which has been part of BlackRock since it completed its acquisition of GIP in October 2024.

Gennaker Secures €2.1B to Move Into Construction

Financial close means the major financing, supply, power sales, and ownership agreements are now in place. Skyborn developed Gennaker from the ground up and will lead construction management and long-term asset management.

The project is located about 15 kilometers north of the Fischland-Darß-Zingst peninsula in Mecklenburg-Western Pomerania. Once complete, its nearly 1 GW capacity will make it the largest offshore wind farm in Germany’s Baltic Sea.

The wind project secured its construction and operations permit in December 2025. Major supply and installation contracts were also signed for foundations, cables, and wind turbines.

Siemens Gamesa is supplying the turbines, while other contractors include EEW, Seaway 7, Boskalis, and Fred. Olsen Windcarrier. Stadtwerke München, or SWM, is also now a 25% equity partner in the project, leaving Skyborn with a 75% stake.

Amazon and Uniper Lock In 700 MW of Power

Gennaker has also secured major buyers for its electricity. In June, Amazon signed a 600 MW power purchase agreement (PPA) covering about 61% of the project’s total capacity. Skyborn and Amazon described it as the largest single PPA ever signed in Germany.

The long-term contract was an important step because it gives the project predictable revenue from electricity sales.

Uniper also signed a 100 MW PPA with Skyborn. The agreement runs for an initial 10 years after commercial operation, with an option to extend. Together, the two contracts cover 700 MW, or roughly 72% of Gennaker’s maximum capacity.

These agreements illustrate how PPAs are becoming an important financing tool for large renewable projects. Long-term electricity contracts can provide revenue visibility that helps banks assess the project’s ability to repay debt.

Germany Needs Gennaker and Many More Like It

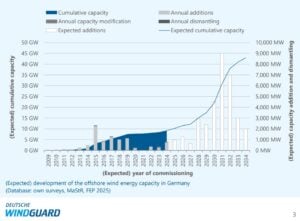
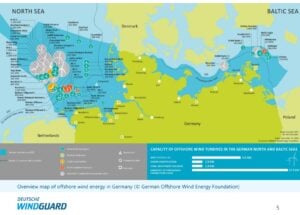
Gennaker arrives as Germany tries to expand offshore wind rapidly. The country has set a target of at least 30 GW of offshore wind capacity by 2030, 40 GW by 2035 and 70 GW by 2045.

Germany offshore wind capacity additions 2034

The country is also targeting 80% renewable electricity by 2030. Gennaker’s 976.5 MW would equal about 3.3% of Germany’s 2030 offshore wind target once fully operational.

The project will, therefore, make a meaningful contribution, but Germany will need many more large projects to reach its targets.

Moreover, offshore development remains challenging. Germany postponed offshore wind auctions originally planned for 2026 until 2027 as part of changes to its offshore wind development plan. The government said the delay would not affect the long-term 70 GW target for 2045.

offshore wind energy Germany map

A Large Bet on Energy Security

Offshore wind is also becoming part of Germany’s energy security strategy. The country is trying to reduce its dependence on imported fossil fuels while increasing domestic electricity production.

Gennaker will add nearly 1 GW of renewable capacity in the Baltic Sea and provide power to the German grid. That can help reduce the need for fossil fuel generation when wind conditions allow.

The project will also support Germany’s industrial base. It will involve European manufacturers, marine contractors, and others in the offshore wind supply chain. The EIB expects the project to create economic value in Mecklenburg-Western Pomerania, where Gennaker is being developed.

Gennaker location
Source: Skyborn

Europe’s Offshore Wind Investment Is Accelerating

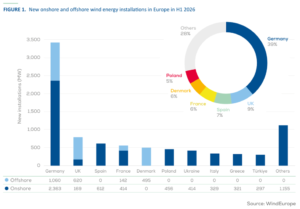
Gennaker is part of a broader recovery in European offshore wind investment. Europe had 40.9 GW of offshore wind capacity by the end of June 2026, after adding 2.3 GW in the first half of the year.

Governments also awarded 8.4 GW of offshore wind capacity through auctions during the period. Germany led additions with 3.4 GW.

Investment is picking up as well. Europe raised €9 billion for new wind projects in H1 2026, including about €0.6 billion for offshore wind. In 2025, six large offshore projects reached final investment decisions, representing 5.6 GW and €22 billion of investment.

European offshore wind installations H1 2026
Source: WindEurope

The longer-term opportunity is much larger. Nine North Sea countries signed a 2026 Investment Pact targeting 15 GW of new offshore wind each year from 2031 to 2040, with industry estimating up to €1 trillion in related economic activity.

However, investment still faces challenges. Grid capacity, permitting, supply chain constraints, and higher project costs remain major barriers. That makes successful financings such as Gennaker important signals that Europe’s offshore wind market can still attract large-scale capital.

Offshore Wind Has a Direct Climate Benefit

Wind power produces electricity without the direct CO2 emissions associated with coal and natural gas generation. Replacing fossil fuel generation with renewable electricity can therefore lower power sector emissions, depending on the generation it displaces.

However, Gennaker should not be described as a carbon credit project. The wind farm will generate renewable electricity rather than voluntary carbon credits. Its climate value comes from replacing carbon-heavy electricity. It also supplies low-carbon power to the grid and contracted customers.

This distinction is important as demand for renewable energy grows alongside carbon markets.

Companies such as Amazon are increasingly using long-term PPAs to secure renewable electricity for their operations and support their emissions goals. However, a renewable energy PPA is not the same as a carbon credit purchase.

BlackRock Expands Its Renewable Infrastructure Footprint

The project also fits into a larger trend in infrastructure investment. BlackRock completed its acquisition of GIP in October 2024, creating a much larger infrastructure investment platform. At completion, the combined platform had about $170 billion in assets under management and more than 300 active investments.

GIP invests across energy, transport, digital infrastructure, and other sectors. Offshore wind matches that strategy. Projects need a lot of upfront money, but they can bring in steady income from power sales over time.

Gennaker’s financing structure shows how public and private capital can work together. Commercial banks provide most of the debt, while the EIB supports the project as a major European climate and infrastructure investment.

A Nearly 1 GW Bet on Germany’s Clean Power Future

Gennaker is moving from development to construction. For Germany, the project adds a significant amount of new offshore wind capacity as the country works toward its 30 GW target for 2030.

Skyborn, backed by BlackRock, shows how to finance big renewable projects. They combine institutional capital, bank debt, equity, and long-term power contracts.

Gennaker points out an important fact for the energy transition: to decarbonize electricity, we need billions of dollars for infrastructure first. Only then will the emissions benefits reach the grid. Projects like Gennaker will become increasingly important to Germany’s effort to expand clean power while reducing its reliance on fossil fuels.

The post BlackRock-Backed Skyborn Secures $2.4B for Major German Offshore Wind Farm appeared first on Carbon Credits.
Google Targets Rice Methane Emissions in India with 1 Million Carbon Credits

Google is expanding its focus on methane emissions with a new agreement to purchase 1 million carbon credits from Mitti Labs, a climate technology startup working with smallholder rice farmers in India.

The four-year agreement will support the rollout of water-saving irrigation practices across more than 100,000 hectares of rice farms by 2030. The program is expected to involve more than 70,000 farmers and reduce methane emissions from rice cultivation while cutting water use.

The deal is Google’s largest superpollutant elimination agreement to date. It also adds to the technology giant’s growing carbon removal strategy, which includes investments in durable carbon removal, nature-based projects and solutions targeting gases other than CO₂.

Why Methane Matters for Climate Action

Methane is particularly important because it has a much stronger warming effect than CO₂ over shorter time periods.

The gas remains in the atmosphere for roughly a decade before breaking down. As a result, reducing methane emissions can slow near-term warming more quickly than cutting emissions of longer-lived greenhouse gases alone.

Agriculture is one of the largest sources of human-caused methane, with livestock and rice cultivation among the key contributors.

methane emissions

Rice Farming Adds to Water Stress

Rice cultivation is a major source of agricultural methane.

Much of the crop is grown in regions where water resources are already under pressure. Continuous flooding can require significant amounts of irrigation water, adding another challenge for farmers and local water systems.

methane emissions AWD RICE Emissions
Source: International Rice Research Institute

How Mitti Labs Is Reducing Rice Methane Emissions

Rice cultivation is a major source of human-caused methane emissions. Traditional rice farming often keeps fields continuously flooded. Under these oxygen-poor conditions, microbes in the soil produce methane, which then escapes into the atmosphere.

Mitti Labs is addressing this problem through a technique known as Alternate Wetting and Drying, or AWD.

Instead of keeping rice fields flooded throughout the growing season, farmers periodically drain the fields before reflooding them. This changes the conditions in the soil and limits methane production.

According to Mitti Labs, AWD can:

  • Cut methane emissions from rice fields by up to 50%.
  • Reduce irrigation water use by close to 40%.
  • Maintain rice yields when properly implemented.

The approach therefore offers two benefits at the same time. Farmers can reduce the amount of water needed to grow rice while also lowering emissions from their fields.

For Google, the project provides a way to address a potent greenhouse gas while supporting agricultural communities.

3 Million Tonnes of CO₂ Savings

Mitti Labs says its program could save about 1.5 trillion liters of water as AWD expands across the targeted farmland. The company compares the volume with roughly three years of Bengaluru’s annual water supply.

The climate impact is also significant. The company estimates that the program could eliminate the equivalent of 3 million tonnes of CO₂ over 20 years. Using the conventional 100-year global warming potential approach, the impact is equivalent to about 1 million tonnes of CO₂e.

The different figures reflect the way methane is measured over different time horizons rather than a change in the underlying emissions reduction.

Mitti Labs’ Satellite Technology Helps Verify Results

Scaling AWD across thousands of small farms presents a measurement challenge. Farmers operate individual plots, and field conditions can change throughout the growing season.

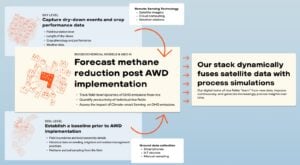
Mitti Labs uses satellite technology and field data to monitor these changes.

  • Its GeoAI platform combines satellite radar imagery with information collected directly from farms. The system can track factors such as flooding, soil moisture, and crop conditions at the individual field level.

The company developed the technology with support from NASA and uses remote sensing to monitor large agricultural areas without relying entirely on physical inspections.

This is important for carbon markets because buyers need evidence that projects are actually delivering the claimed emissions reductions.

Mitti Labs combines its satellite-based monitoring with on-the-ground data and farmer engagement. The approach is designed to verify whether farmers are adopting AWD and whether the changes are producing the expected environmental benefits.
                                             Mitti Labs next-gen dMRV

mitti labs dmrv
Source: Mitti Labs

Methane Credits Get Sylvera A Rating

The company says its methane credits have received an A rating from carbon ratings agency Sylvera, reflecting the strength of its implementation and measurement approach.

Google Builds a Broader Superpollutant Strategy

The Mitti Labs agreement is part of a wider shift in Google’s climate strategy.

  • The company has increasingly looked beyond conventional CO₂ removal to gases that can produce significant near-term warming. In 2025, Google contracted for 1 million tonnes of superpollutant credits
  • It also announced plans to spend at least $50 million through 2030 on projects targeting methane, fluorinated gases and other non-CO₂ greenhouse gases.

google carbon removal

Google has also worked on methane monitoring for more than a decade.

Its efforts have included partnerships focused on identifying methane leaks, supporting satellite-based monitoring and backing the development of artificial intelligence tools that can detect methane emissions.

The strategy reflects a broader recognition that climate action does not have to rely on one type of solution.

Reducing methane can deliver relatively rapid climate benefits, while removing CO₂ from the atmosphere can address the longer-term accumulation of carbon dioxide.

Carbon Removal Portfolio Tops 1.3 Million Tonnes

In 2025, the company signed 16 carbon removal agreements worth more than $100 million. Those contracts covered around 600,000 tonnes of CO₂ removal.

  • Combined with earlier commitments, Google’s contracted carbon removal portfolio exceeded 1.3 million tonnes of CO₂ by the end of 2025.
  • And its carbon reduction initiatives avoided over 58 million tCO2e in 2025.

The portfolio spans different approaches, including long-duration carbon removal and nature-based solutions. As explained before, targeting methane and other superpollutants is also a significant part of Google’s net zero plan.

google emissions carbon removal
Source: Google

This creates a broader climate strategy built around different timescales. Methane reductions can help limit near-term warming, while durable carbon removal aims to keep CO₂ out of the atmosphere for much longer periods.

Agriculture Could Become a Larger Climate Solution

The Google-Mitti Labs agreement also highlights agriculture’s growing role in carbon markets.
Rice farmers do not need to completely change how they grow the crop. Instead, AWD modifies how they manage water during cultivation.

It could make the approach easier to scale, particularly in regions where farmers already face water shortages and rising climate risks.
For carbon markets, however, scale will need to be matched with strong measurement. Projects involving thousands of smallholder farms must demonstrate that emission reductions are real, measurable, and sustained.
Mitti Labs is betting that satellite monitoring and field-level data can help solve that challenge.

If the program reaches its target of more than 100,000 hectares, it could become a major example of how digital technology can connect smallholder agriculture with climate finance.

For Google, the agreement adds another piece to a carbon strategy that is moving beyond traditional CO₂ removal. And for the carbon market, it shows how methane reduction, water conservation, and agricultural finance can increasingly overlap in a single project.

The post Google Targets Rice Methane Emissions in India with 1 Million Carbon Credits appeared first on Carbon Credits.