Textile Emissions Are Rising. Can Carbon Credits Help the Industry Cut Its Footprint?

The textile industry is facing a difficult climate equation. Global demand for clothing and other textile products continues to grow, while the industry is under increasing pressure to reduce emissions across energy use, raw materials, manufacturing and transportation.

The scale of the challenge is becoming clearer. The United Nations Environment Programme estimates that the fashion and textile sector accounts for 2% to 8% of global greenhouse gas emissions. The sector also consumes about 215 trillion liters of water annually, highlighting how closely its climate footprint is tied to broader resource use.

More recent data suggests that emissions are not falling fast enough.

The Apparel Impact Institute calculated that global apparel emissions reached 944 million metric tons of CO₂e in 2023, up 7.5% from the previous year. The increase represented the first year-over-year rise in the institute’s series and was driven largely by higher apparel production and growing dependence on virgin polyester.

At the same time, the industry’s raw-material base continues to expand.

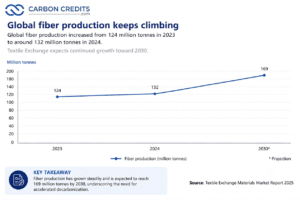
Global Fiber Production Hits Another Record

Textile Exchange reported that global fiber production climbed to approximately 132 million tonnes in 2024, up from 125 million tonnes in 2023. That means production has increased by roughly 34 million tonnes since the Paris Agreement was adopted in 2015. Textile Exchange expects continued growth toward 2030, and polyester sits at the center of this problem..

The trend matters because additional production can offset efficiency improvements. Even if individual factories become cleaner, total emissions can continue rising when the industry produces more material.

global fiber production
Source: Textile Exchange Materials Market Report 2025.
  • Textile Exchange said polyester production reached approximately 78 million tonnes in 2024, accounting for about 59% of global fiber production. Synthetic fibers as a whole represented around 69% of the market.

The problem is that most polyester remains fossil-fuel-based. The industry therefore faces a double challenge: reducing the emissions associated with manufacturing textiles while also limiting the growth of virgin fossil-based materials.

Recycling is growing, but not quickly enough.

The share of recycled fibers was about 7.6% of the global fiber market in 2024, according to Textile Exchange. Yet less than 1% of global fiber production came from recycled pre- and post-consumer textiles. Most recycled polyester still comes from plastic bottles rather than old clothing.

That leaves manufacturers with a large decarbonization opportunity.

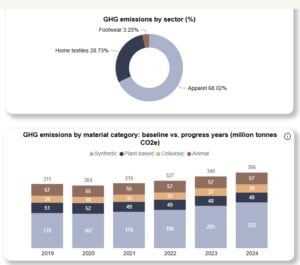
Where Textile Emissions Come From?

Textile emissions do not come from a single stage of production.

The footprint starts with raw materials. Producing polyester requires fossil feedstocks, while cotton can carry emissions from fertilizer, irrigation, farm machinery and land use.

The next major source is manufacturing.

Spinning, weaving, knitting, dyeing, finishing and drying can require substantial amounts of electricity and heat. In countries where factories rely heavily on coal and natural gas, the carbon intensity of textile production can be particularly high.

Transportation further boosts the emissions.

Recent corporate disclosures show how quickly logistics emissions can rise when brands depend on air freight. Shein reported 8.52 million tonnes of CO₂e from transportation in 2024, up 13.7% from 2023. Inditex reported 2.61 million tonnes of transport-related emissions in its 2024 financial year, up 10%.

The figures demonstrate why textile decarbonization cannot focus solely on fabric.

It needs to address the entire value chain.

TEXTILE EMISSIONS
Source: Textile Exchange

Textile Carbon Credits Could Create a New Financial Incentive

This is where carbon markets become increasingly relevant.

A textile carbon credit can represent a verified reduction or removal of greenhouse gas emissions. In practical terms, a factory could reduce its emissions through measures such as renewable electricity, energy-efficiency improvements, fuel switching or cleaner industrial heat.

If the reduction qualifies under an approved carbon-crediting system, the resulting environmental benefit could potentially become a tradable asset.

India’s Textile Carbon Market Takes Shape, Sets an Example 

That creates a direct economic incentive to reduce the amount of emissions generated per unit of textile production.

And the system is moving closer to implementation.

In August 2026, the Bureau of Energy Efficiency opened a tender to engage agencies for baseline energy and greenhouse-gas emissions data collection for the textile sector under CCTS.

This is an important development because reliable baselines are essential before factories can accurately determine how much they have reduced emissions.

What Textile Factories Can Do to Generate Reductions?

The biggest opportunities are likely to come from technologies that reduce fossil-fuel consumption.

Factories can replace coal- or gas-fired thermal systems with electric equipment where technically feasible. Renewable electricity can also reduce emissions from spinning, weaving and other electricity-intensive processes.

Energy efficiency offers another relatively immediate opportunity.

Efficient boilers, motors, compressors, heat recovery systems and process controls can reduce energy consumption without necessarily requiring a complete redesign of a factory.

Fuel switching could become particularly important for dyeing and finishing, where industrial heat represents a significant energy requirement.

Carbon-credit revenues could help improve the economics of these investments.

But there is an important caveat.

A company should not treat carbon credits as a substitute for cutting its own emissions. High-quality climate strategies prioritize direct reductions first. Credits can then provide an additional financial mechanism for verified reductions that meet strict accounting and verification requirements.

The Bigger Opportunity is Supply-Chain Finance

The textile industry’s carbon problem extends far beyond major fashion brands.

Thousands of manufacturers produce yarn, fabric, dyes, garments and finished products for global brands. Many smaller suppliers lack the capital to install renewable energy, modern boilers or advanced efficiency systems.

Carbon finance could potentially help bridge that gap.

This is particularly relevant to Scope 3 emissions. Verra’s emerging Scope 3 Standard program is designed to certify value-chain interventions and issue units associated with verified greenhouse-gas benefits. Its development work specifically includes textiles as a potential value-chain application.

That could eventually allow brands to help finance emissions reductions at supplier facilities while establishing a clearer link between the investment and the resulting climate benefit.

The model could look something like this:

  • Brand financing → Factory investment → Verified emissions reduction → Carbon unit → Revenue/Scope 3 accounting

The key will be credible measurement.

Without accurate production data, energy data, and emissions baselines, it becomes difficult to determine whether a claimed reduction is real and additional.

Europe is Adding Another Layer of Pressure

The economics of textile emissions are also changing because governments are targeting waste and overproduction.

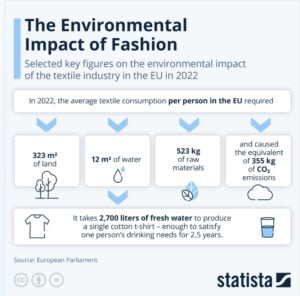
  • EU textile consumption reached 19 kg per person in 2022, up from 17 kg in 2019. EU households’ textile consumption generated an estimated 159 million tonnes of CO₂e in 2022, equal to about 355 kg per person.
  • Europe also generated approximately 6.94 million tonnes of textile waste in 2022, or 16 kg per person.

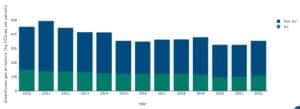
Greenhouse gas emissions from the EU’s textile consumption

eu textlie emission
Source: European Environment Agency (eea.europa.eu)

The EU is moving toward stronger producer-responsibility and circularity requirements, while France has already introduced environmental fees targeting ultra-fast-fashion businesses such as Shein and Temu. And this could make low-carbon production increasingly important for exporters.

EU textile emission

But Carbon Credits Are Not the Whole Solution

The textile industry’s climate challenge is ultimately a production problem.

Textile Exchange’s Climate+ strategy calls for a 45% reduction in greenhouse-gas emissions from fiber and raw-material production by 2030. Yet the organization says the industry remains off track to meet that target. This gap explains why carbon finance is attracting attention.

The opportunity is not simply to create another market for offsets. It is to direct capital toward factories and supply chains that can produce measurable, permanent and additional emissions reductions.

For investors, the most interesting opportunities may therefore sit behind the clothing brands—in renewable industrial heat, energy efficiency, low-carbon dyes, recycled fibers, textile-to-textile recycling and cleaner manufacturing.

For textile manufacturers, the message is even more direct.

Carbon is becoming a cost. But with credible measurement and the right market structure, it can also become a source of financing for the transition.

The companies that reduce emissions most efficiently could eventually gain an advantage not only in compliance but also in access to global customers demanding lower-carbon supply chains.

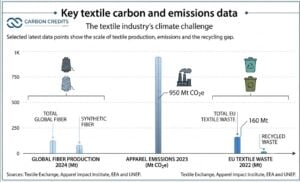
A summary of key textile carbon and emissions data

Sources: Textile Exchange, Apparel Impact Institute, EEA and UNEP.

Bottom Line

Textile carbon credits are still an emerging market, but India’s inclusion of textiles in its compliance carbon market could be a major turning point. The combination of emissions-intensity targets, factory-level baselines and tradable certificates could turn decarbonization from a sustainability expense into a measurable financial incentive.

The post Textile Emissions Are Rising. Can Carbon Credits Help the Industry Cut Its Footprint? appeared first on Carbon Credits.

Singapore-based CIX, Carbonplace Merger Targets More Connected Global Carbon Market

Singapore-based CIX, Carbonplace Merger Targets More Connected Global Carbon Market

Climate Impact X (CIX) and Carbonplace plan to merge in a deal that could reshape the infrastructure behind global carbon markets. The Singapore-based environmental markets exchange and London-based carbon portfolio management platform announced their intent to combine on August 26, 2026.

The deal would bring together CIX’s exchange, trading, and price-discovery tools with Carbonplace’s multi-registry access and bank-grade settlement system. The companies say the goal is to create a more connected system for buying, trading, settling, holding, and retiring carbon credits.

The deal still needs regulatory approval. The companies expect to finish the integration by Q1 2027. Both businesses will keep their current brands during this time.

Two Carbon Market Powerhouses Move to Join Forces

CIX and Carbonplace operate at different points in the carbon credit transaction process.

CIX provides procurement, trading, and price discovery. Its platforms include an exchange for standardized carbon contracts and tools for project sourcing and transactions. CIX also provides price benchmarks and data products.

Carbonplace focuses on what happens after a trade. Its platform provides multi-registry access, settlement, custody, reporting, and retirement. It currently connects users to 14 carbon and renewable energy certificate registries through a single system.

The merger would combine these functions. Buyers and sellers could have one clear path. They can find and price credits easily, and they can complete the transaction and track ownership smoothly.

The companies say this could ease some of the friction in the carbon market. Right now, it’s divided across various exchanges, registries, countries, and standards.

CEO Oi-Yee Choo remarked:

“Scaling access and liquidity to meet the growing needs of global carbon markets requires robust, trusted infrastructure. This infrastructure must work across voluntary and compliance schemes, and across geographies and standards.”

12 Financial Giants Back the Deal

The proposed company will have backing from 12 major financial institutions, investors, and market operators.

  • They are BBVA, BNP Paribas, CIBC, DBS, GenZero, Mizuho Financial Group, National Australia Bank, NatWest Group, Singapore Exchange (SGX), Standard Chartered, Sumitomo Mitsui Banking Corporation (SMBC), and UBS.

The shareholder base gives the deal a strong link to traditional financial markets.

CIX itself was established in 2021 and is backed by DBS, GenZero, Mizuho, SGX, and Standard Chartered. GenZero is a decarbonization investment platform founded by Temasek. In 2020, major banks like BBVA, BNP Paribas, CIBC, National Australia Bank, NatWest, SMBC, Standard Chartered, and UBS supported Carbonplace.

The combined ownership, therefore, gives the new platform access to financial institutions across Asia, Europe, and other major markets.

Can One Platform Fix Carbon Market Fragmentation?

The merger comes as carbon markets try to become larger and more credible. A major challenge is fragmentation.

Different carbon standards and registries use different systems for issuing, tracking, and retiring credits. Buyers may also need separate relationships with different platforms to source credits, assess prices, and complete transactions. That can make carbon trading more complex than trading many traditional financial assets.

CIX and Carbonplace argue that stronger infrastructure can help solve this problem. Their proposed platform would connect price discovery, trading, registry access, settlement, custody, and retirement across the transaction lifecycle.

That could become more important as carbon markets expand beyond voluntary corporate purchases.

Article 6 Could Increase Demand for Infrastructure

The growth of Article 6 of the Paris Agreement is one reason companies see a need for better infrastructure.

Article 6.2 allows countries to transfer emissions reductions internationally, provided they follow agreed accounting rules. This creates a potential bridge between national climate policies and international carbon markets.

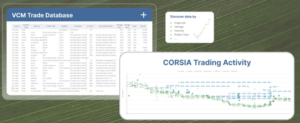
The CIX-Carbonplace announcement also points to the Carbon Offsetting and Reduction Scheme for International Aviation (CORSIA). CORSIA requires participating airlines to use eligible emissions units to address certain growth in international aviation emissions.

CIX CORSIA database

As these systems expand, carbon transactions may involve more than just voluntary corporate buyers. Governments, financial institutions, and regulated companies could play a bigger role.

That could increase demand for systems that can track ownership and retirement with clear records.

CIX Brings Trading and Price Discovery to the Table

Price transparency is another major part of the proposed merger. Carbon markets often have different prices for credits based on project type, location, vintage, and quality. This can make it difficult for buyers to compare credits.

CIX database and price benchmark
Source: CIX

CIX operates an exchange and develops price benchmarks designed to provide more visibility into market-driven prices. Its exchange offers standardized contracts. This lets buyers purchase larger volumes of credits that meet specific requirements. They don’t have to pick individual credits from each project one at a time.

Carbonplace adds a different layer. Its system tracks ownership and provides settlement and reporting tools across multiple registries.

Carbonplace database
Source: Carbonplace

Combining the two could address both market sides: finding and pricing credit, then securely completing and recording the transaction.

Singapore and London Build a Carbon Market Bridge

The proposed merger also connects two important financial centers. CIX is headquartered in Singapore, while Carbonplace is based in London. The companies say the combined business could connect participants across different time zones, regulatory systems and trading communities.

That Asia-Europe link could be important for carbon markets.

Southeast Asia offers great potential for nature-based carbon projects. Meanwhile, Europe holds vast amounts of corporate and institutional capital eager for climate investments.

A more connected platform could make it easier to link project developers and suppliers in emerging markets with international buyers.

The companies highlight cooperation among Singapore, the UK, and Kenya. They’re working together through the Coalition to Grow Carbon Markets. This group aims to boost carbon market development.

CIX and Carbonplace merger

Better Infrastructure Won’t Fix Credit Quality

Despite its potential, the deal does not automatically solve the carbon market’s biggest challenges. A better trading and settlement system cannot by itself guarantee that carbon credits deliver real emissions reductions or removals.

Credit quality remains critical.

CIX says it maintains standards around quality, impact, and credibility for the products offered through its platforms. Carbonplace focuses on secure ownership, tracking, and reporting. The broader market still needs strict rules for additionality, permanence, monitoring, reporting, and verification.

Liquidity is another challenge.

A platform can make trading easier, but buyers and sellers still need to participate at a sufficient scale. Without enough market activity, price discovery and trading volumes can remain limited.

The merger, therefore, provides infrastructure. It does not guarantee the growth of the underlying market.

The Bigger Goal: Unlock Institutional Carbon Trading

The CIX-Carbonplace deal reflects a broader shift in carbon markets.

Early voluntary carbon markets relied heavily on project developers, brokers, and individual registries. As the market becomes more connected to Article 6, CORSIA, and sovereign climate policies, participants need systems that can handle more complex transactions.

The proposed merger aims to provide that foundation. If completed, the merger would mark a major consolidation in carbon market infrastructure.

The bigger question is whether a more connected trading and settlement system can help carbon markets attract the liquidity, transparency and institutional capital needed to scale.

The post Singapore-based CIX, Carbonplace Merger Targets More Connected Global Carbon Market appeared first on Carbon Credits.

US Biochar Firm and Singapore Asphalt Producer Test Carbon-Sequestering Roads

US Biochar Firm and Singapore Asphalt Producer Test Carbon-Sequestering Roads

U.S. biochar company Verde Resources and Singapore asphalt producer Highway International have signed a memorandum of understanding (MoU) to test a biochar-based system for roads and other infrastructure.

The companies plan to start a pilot in Singapore to test road performance, asphalt mixes, production, and carbon accounting. The project will also test how the system could work on a larger scale.

The partnership could create a new market for biochar carbon removal by storing stable carbon inside roads, airfield pavements, and other long-lasting infrastructure. Yet, the project remains in the testing stage. The companies must first prove that the material works and that they can measure and verify the carbon stored in finished roads.

Singapore Roads Become a Carbon Removal Test Bed

Verde and Highway plan to work on an initial pilot with Singapore’s Land Transport Authority (LTA). The pilot will test technical performance, pavement mixes, production readiness and the system for measuring stored carbon. It will also test the project’s monitoring, reporting and verification (MRV) process.

If the pilot succeeds and LTA approves the approach, the companies plan to discuss a wider licensing deal. Highway could become Verde’s Singapore licensee for its Net Zero Blueprint. The planned use could cover roads, airport runways and other infrastructure.

However, the MoU does not guarantee commercial rollout. The companies still need successful testing, LTA approval, regulatory approvals, due diligence and final commercial agreements.

How Biochar Could Store Carbon in Roads

Biochar is made by heating biomass with little oxygen. The process creates a stable form of carbon that can remain stored for a long time.

Verde plans to use biomass waste, including palm-oil residues, to make engineered biochar for asphalt. Instead of allowing the carbon in the biomass to return to the atmosphere through decay, the company wants to lock it into road materials.

The idea turns infrastructure into a potential carbon storage site.

Verde’s system combines engineered biochar with asphalt technology and carbon accounting. It also includes lifecycle assessment (LCA), environmental product declarations (EPDs), and digital project-data tracking.

verde biochar asphalt technology
Source: Verde Resources

The actual amount of carbon stored will vary by project. Developers must also count emissions from making, transporting, and processing the biochar when calculating the net removal.

Verde Has Early Carbon Removal Results

The Singapore pilot builds on earlier testing in the United States. In December 2024, Verde and C-Twelve tested cold-mix biochar asphalt at the National Center for Asphalt Technology (NCAT) test track in Auburn, Alabama.

Verde’s latest SEC filing says the test sequestered about 8 tons of carbon. Puro.earth verified and certified the related carbon removal credits, which Verde says it issued and sold in April 2025. Verde describes the project as the world’s first to generate carbon removal credits from asphalt production and installation.

The volume was small, however. The Singapore pilot will test whether the method can move from a demonstration to larger commercial projects.

Isometric Adds Another Verification Route

Verde is also working with Isometric to develop a carbon credit pathway for its engineered biochar. The companies announced their collaboration in April 2026. Isometric says its biochar protocol includes lifecycle accounting, feedstock rules, and durability measurements, including uses such as asphalt.

Verde is therefore working with more than one carbon market platform. Its SEC filing says Puro.earth has registered Verde as a carbon removal credit supplier. The company is also working with Isometric on certification and verification.

Strong carbon accounting will remain important. A road can generate credible removal credits only if developers can prove how much carbon the biochar stores and how long that carbon stays locked away.

Biochar Supply Will Matter at Scale

Commercial growth will require a steady supply of qualifying biochar. In March 2026, Verde signed a supply agreement with Biochar Solutions LLC for up to 38,500 U.S. tons of engineered biochar per year.

At least 50% of that supply must qualify for carbon removal credit generation. The agreement also covers revenue sharing from credits generated when the biochar goes into Verde’s products.

The deal shows that Verde is preparing for larger production. But the Singapore pilot will still need to prove that biochar can meet road performance standards while keeping its carbon storage benefits.

Global Biochar Market Gains Momentum

The global biochar market is growing as demand for durable carbon removal increases. The American Biochar Institute found that the U.S. biochar industry reached about $157 million in 2025, nearly three times its 2023 value of $52 million. U.S. production topped 97,000 metric tonnes, while installed capacity exceeded 400,000 tonnes a year.

Globally, biochar supplied more than 90% of durable carbon removal credits delivered in 2025, according to CDR.fyi. Strong corporate demand and new production projects are helping the sector expand, while buyers increasingly seek credits backed by clear carbon accounting and durable storage.

biochar carbon credit market 2025

SEE MORE: U.S. Biochar Industry Triples to $157 Million as Carbon Removal Market Sparks Record Growth

Why Singapore Is a Strategic Test Market

Singapore provides a useful test market because it has a large infrastructure system but limited land for renewable energy projects. The country aims to reach net-zero emissions by 2050. It also targets emissions of 45 million to 50 million tonnes of CO2e by 2035, compared with about 60 million tonnes in 2030.

Singapore is using several tools to cut emissions, including a carbon tax and international carbon markets. Its carbon tax rose to S$45 per tonne in 2026 and 2027, with a target of S$50 to S$80 per tonne by 2030. Covered facilities can use eligible international carbon credits to offset up to 5% of taxable emissions.

That does not mean Verde’s road credits automatically qualify for Singapore’s compliance market. They would need to meet the country’s rules on Article 6, additionality, and double counting.

For now, the project should be viewed as a carbon removal development rather than an approved Singapore compliance credit program.

verde biochar asphalt

Credit Quality Must Keep Pace With the Technology

The carbon market side is just as important as road performance. Verde’s earlier NCAT test produced about 8 tons of verified carbon removal, but that result does not prove every future road project will achieve the same level of storage.

The Singapore pilot will help answer those questions. Developers will need to measure the amount of biochar used, its carbon content, emissions from production and transport, and the carbon that remains stored in the finished road.

That makes the LCA and MRV systems especially important. A road product can create a new carbon-removal market only if independent systems can confirm the actual net removal.

Could Roads Become the Next Carbon Sink?

The Verde-Highway MoU brings biochar and road construction into the same carbon removal strategy. The pilot will test whether engineered biochar can meet road standards while storing carbon in long-lived infrastructure. It will also test how developers can measure and verify those removals.

The project remains at an early stage. The MoU does not guarantee a final licensing deal or a specific volume of carbon removals from Singapore.

Still, Verde already has an early U.S. demonstration, a 38,500-ton annual biochar supply agreement, an Isometric partnership and a Singapore subsidiary focused on regional growth.

If the Singapore pilot succeeds, roads could become a new application for durable biochar carbon removal. For the biochar market, the key question is whether carbon stored in everyday infrastructure can become measurable, verifiable, and scalable enough to support a new class of carbon removal credits.

The post US Biochar Firm and Singapore Asphalt Producer Test Carbon-Sequestering Roads appeared first on Carbon Credits.

What Types of Projects Generate Carbon Credits?

What Types of Projects Generate Carbon Credits?

Carbon credits can come from many different types of projects, but they all have one basic purpose: to reduce greenhouse gas emissions or remove carbon dioxide (CO₂) from the atmosphere.

A single carbon credit generally represents one metric ton of CO₂ equivalent (tCO₂e) reduced or removed by a project. For example, a project that captures methane from a landfill may generate credits by preventing that methane from entering the atmosphere. A reforestation project can generate credits by storing additional carbon in growing trees.

The voluntary carbon market (VCM) supports projects across energy, waste, agriculture, forestry, and carbon-removal technologies. Verra’s Verified Carbon Standard (VCS), one of the major carbon crediting programs, currently recognizes project activities across 18 sectoral scopes, ranging from energy and waste to agriculture, forestry, geological carbon storage, engineered removals, and marine resources.

But not all carbon projects work in the same way. The most important distinction is between emissions reduction projects and carbon removal projects.

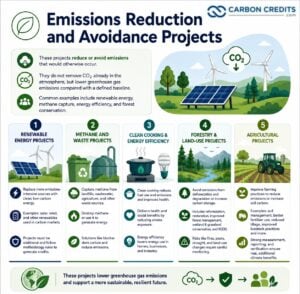
Emissions Reduction and Avoidance Projects

Many carbon credits come from projects that reduce or avoid emissions that would otherwise occur.

These projects do not necessarily remove CO₂ that is already in the atmosphere. Instead, they reduce the amount of greenhouse gases released compared with a defined baseline.

Common examples include renewable energy, methane capture, energy efficiency, and forest conservation.

Renewable Energy Projects

Renewable energy projects can generate carbon credits when they replace more emissions-intensive sources of electricity or energy.

Solar, wind, and some other renewable energy projects have historically been used in carbon markets. The basic idea is that generating electricity from a low-carbon source can reduce emissions compared with a higher-emitting alternative.

However, whether a renewable energy project can generate credits depends on the applicable methodology and whether the emissions reduction is considered additional. In other words, the project must meet the relevant rules for demonstrating that the carbon market incentive contributes to the claimed climate benefit.

Methane and Waste Projects

Waste projects are another important source of carbon credits. Landfills, wastewater treatment facilities, agriculture, and other waste-related activities can release methane, a powerful greenhouse gas. Projects can capture methane and either destroy it or use it to generate energy.

Other waste projects can also generate credits by changing how organic waste is treated. Biochar, for example, can be produced from biomass and used in ways that store carbon while also potentially reducing emissions from conventional waste management.

Carbon crediting programs such as Verra include waste handling and disposal among their recognized project categories.

Clean Cooking and Energy Efficiency

Carbon credits can also support technologies that reduce energy use or replace more polluting fuels. Clean cooking projects are one example. Improved cooking technologies can reduce the amount of fuel needed and, depending on the technology and methodology, reduce greenhouse gas emissions.

These projects can also produce health and social benefits by reducing household exposure to harmful cooking smoke.

Clean cooking remains an important carbon market project type. In 2025, the Integrity Council for the Voluntary Carbon Market (ICVCM) confirmed that several Gold Standard clean cooking methodologies were eligible under its Core Carbon Principles (CCP), reflecting the continued role of the sector in the voluntary market.

Other energy efficiency projects can include more efficient lighting, heating, appliances, and industrial processes. The Gold Standard, for example, recognizes renewable energy and end-use energy efficiency projects among its eligible activities.

Forestry and Land-Use Projects

Forestry and land-use projects are among the best-known categories in the carbon market. These projects can either avoid emissions or remove and store carbon.

Forest conservation projects, including REDD-related activities, aim to reduce emissions associated with deforestation and forest degradation. Other projects focus on planting trees, restoring forests, improving forest management, or protecting wetlands.

Verra’s Agriculture, Forestry and Other Land Use (AFOLU) category includes afforestation, reforestation and revegetation, agricultural land management, improved forest management, REDD, grassland conservation, and wetland restoration.

The climate benefit comes from either preventing carbon that is already stored in ecosystems from being released or increasing the amount of carbon stored in vegetation, soils, or other natural systems.

However, these projects also face risks that can affect the durability of their carbon benefits. Forests can be damaged by wildfire, pests, drought, storms, or future changes in land use. This makes careful monitoring and appropriate accounting especially important.

Agricultural Projects

Agriculture can generate carbon credits through changes in farming practices that reduce emissions or increase carbon storage.

Examples include improved soil management, changes in fertilizer use, better water management, reduced tillage, improved livestock practices, and other techniques that can lower greenhouse gas emissions or increase soil carbon.

Agricultural projects can be more complex to measure because carbon levels can vary across fields and over time. As a result, strong measurement, reporting, and verification systems are important for determining how much additional climate benefit a project actually creates.

Agriculture is a recognized carbon project category under major standards, including Verra’s VCS.

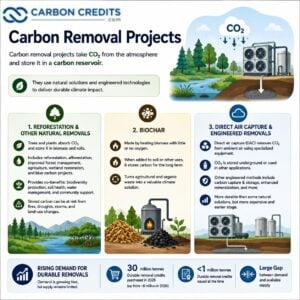
emissions reductions and avoidance projects

Carbon Removal Projects

The second major category is carbon removal. Unlike an emissions-reduction project, a carbon removal project takes CO₂ from the atmosphere and stores it in a carbon reservoir.

There are several ways to achieve this, ranging from natural approaches such as reforestation to engineered technologies such as direct air capture.

Reforestation and Other Natural Removals

Trees and plants naturally absorb CO₂ as they grow. Reforestation, afforestation, improved forest management, and some agricultural practices can therefore remove carbon from the atmosphere and store it in biomass and soils.

Other natural carbon removal projects include wetland restoration and blue carbon projects, which protect or restore carbon-rich coastal and marine ecosystems.

These approaches can provide additional benefits such as biodiversity protection, improved soil health, water management, and support for local communities. However, the stored carbon can be vulnerable to fires, droughts, storms, land-use changes, and other risks.

Biochar

Biochar is another carbon removal approach. It is produced by heating biomass under controlled conditions with little or no oxygen. The resulting material can then be used in soil or other applications.

When biomass absorbs CO₂ as it grows and is subsequently converted into stable biochar, some of that carbon can remain stored for a long period.

Biochar has attracted growing attention because it combines carbon removal with the potential to put agricultural and organic waste to productive use.

carbon removal project types

Direct Air Capture and Engineered Removals

Some carbon removal projects use technology to capture CO₂ directly from the atmosphere. Direct air capture (DAC) uses specialized equipment to extract CO₂ from ambient air. The captured carbon can then be stored underground or used in other applications, depending on the project.

Other engineered approaches include carbon capture and storage, enhanced mineralization, and other technologies designed to permanently or durably store atmospheric CO₂.

These technologies can offer more durable storage than some nature-based approaches, but they are generally more expensive and remain at an earlier stage of deployment.

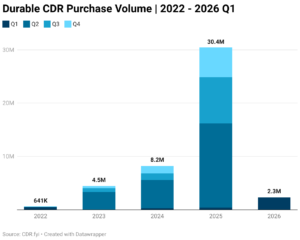
Demand for durable carbon removals has increased sharply in recent years. In 2025, buyers purchased an estimated 30 million tonnes of durable carbon removal credits, up from about 8 million tonnes in 2024, according to CDR.fyi data. Yet, fewer than 1 million tonnes of durable removal credits had been issued at the time, highlighting the gap between demand and available supply.

durable-cdr-purchase-volume-2022-2026-q1

Why Does the Project Type Matter?

The type of project matters because each approach has different costs, risks, climate benefits, and measurement challenges.

A methane capture project may prevent a powerful greenhouse gas from reaching the atmosphere. A forest project may protect existing carbon stocks or increase biological carbon storage. A DAC facility physically removes CO₂ from the atmosphere and can store it for very long periods.

These differences also affect carbon credit prices. Lower-cost emissions-reduction projects can generate relatively inexpensive credits, while newer carbon-removal technologies can cost substantially more. But a higher price does not automatically mean a better credit.

Buyers should examine whether the claimed emissions reduction or removal is real, measurable, additional, durable, and independently verified. They should also consider risks such as leakage, reversal, and double counting.

The Bottom Line

Carbon credits can be generated by a wide range of projects, from renewable energy and methane capture to forest conservation, clean cooking, agriculture, biochar, and direct air capture.

The key distinction is whether a project reduces or avoids emissions or removes CO₂ from the atmosphere. Both can play a role in climate action, but they have different costs, risks, and methods for measuring their impact.

As the carbon market develops, demand is increasingly shifting toward projects that can demonstrate strong and durable climate benefits. Understanding where a carbon credit comes from is therefore just as important as knowing its price.

The post What Types of Projects Generate Carbon Credits? appeared first on Carbon Credits.
Amazon’s $2.8 Billion Clean Energy Push in Australia: Why Battery Storage Matters

Amazon (AMZN stock) is expanding its clean-energy strategy in Australia with a move that could become increasingly important as renewable power takes a larger role in the country’s electricity system. It has signed its first standalone battery storage agreement globally for the 50-megawatt Bairnsdale battery energy storage system (BESS) in Victoria. It is also the first standalone battery agreement signed by a non-energy company in Australia.

The project marks a shift in how Amazon approaches renewable energy. Rather than focusing only on adding wind and solar generation, the company is investing in infrastructure that can help manage when electricity is produced and when it is needed.

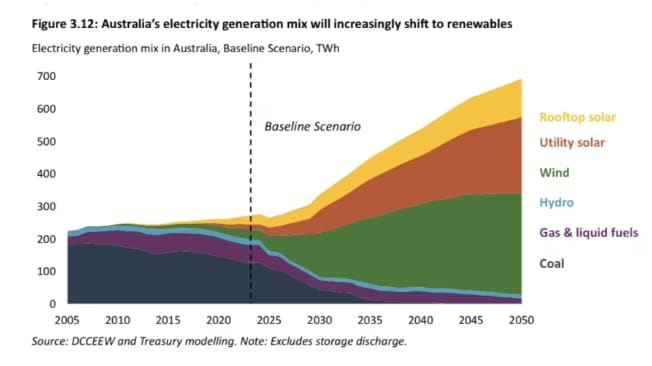
That distinction matters because Australia’s renewable energy system is producing more electricity at certain times than the grid can immediately use.

Australia clean energy
Chart from The Energy.com

Why Amazon Is Investing in Battery Storage

The Bairnsdale battery is not directly connected to a solar or wind farm. Instead, it connects to the national electricity grid. This allows the battery to operate independently of a specific renewable project. When electricity supply is high and demand is relatively low, the system can store power. Later, when demand increases, it can send electricity back into the grid.

The timing is particularly important for solar power. Solar farms can produce large amounts of electricity around midday, when sunlight is strongest. However, electricity demand often rises later in the day as households return home, businesses remain active and solar generation begins to decline.

Battery storage helps bridge this gap.

Instead of curtailing surplus renewable electricity, the grid can store some of it and use it during periods of higher demand. In turn, this can reduce pressure on the electricity system, improve grid flexibility and make renewable generation more valuable.

  • Australia produced an estimated 7.2 terawatt-hours of surplus wind and solar electricity in 2025. Much of this electricity was generated at times when the grid did not need all of the available supply.

Consequently, batteries are becoming a critical part of Australia’s energy transition.

Amazon’s Growing Energy Portfolio in Australia

Bairnsdale is only one part of Amazon’s expanding energy investments in Australia. The company has invested in seven battery projects in Victoria and 10 battery projects across Australia. Once completed, the projects are expected to provide a combined 368 MW of battery capacity.

At the same time, the retail giant continues to develop a broader portfolio of renewable energy projects.

  • Since 2020, the company estimates that it has invested about A$2.8 billion in carbon-free energy projects across Australia. Its portfolio includes solar, wind and battery storage.
  • It expects its 20 Australian carbon-free energy projects to eventually provide almost 1 GW of new renewable capacity. The company estimates the electricity generated will be equivalent to the annual consumption of more than half a million Australian households.

The scale of this investment highlights an important change in corporate renewable energy procurement. Large companies are no longer simply looking for enough renewable electricity to match their consumption. Increasingly, they are looking at how their investments can support the wider electricity system.

Carbon Footprint Adds to this Context

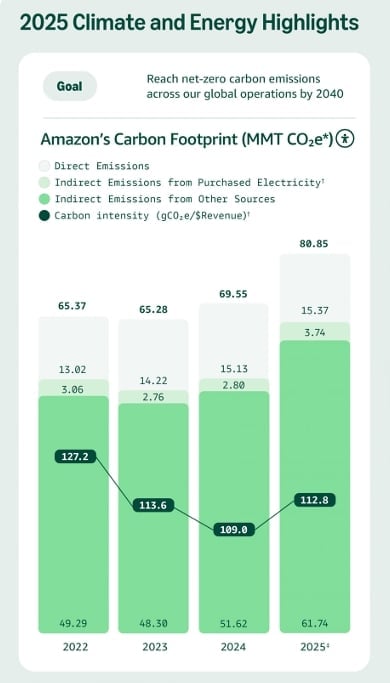
Amazon’s renewable energy investments also need to be viewed against the scale of its overall carbon footprint.

The company’s emissions come from a broad global operation that includes data centers, transportation, warehouses, buildings, purchased electricity, and its supply chain. As its logistics network and cloud computing business continue to expand, reducing emissions across these activities remains a significant challenge.

Amazon has committed to reaching net-zero carbon emissions across its operations by 2040 through The Climate Pledge. The company says its approach starts with reducing emissions across its operations and supply chain. It also plans to address remaining emissions through measures such as carbon removal, nature-based solutions and other forms of carbon neutralization.

emissions Amazon
Source: Amazon

Closing the Emission Gap 

Renewable energy is therefore only one part of the strategy. Battery storage is becoming relevant because it can help Amazon address electricity-related emissions while also supporting a more flexible grid.

Amazon reached its goal of matching 100% of the electricity consumed by its global operations with renewable energy in 2025, five years earlier than its original 2030 target. However, matching electricity consumption with renewable energy does not eliminate all of the company’s emissions.

“According to BloombergNEF, Amazon was the largest corporate purchaser of carbon-free energy in Australia in 2025.”

Its wider carbon footprint means Amazon still needs to reduce emissions from transportation, buildings, manufacturing, suppliers and other parts of its value chain.

Data Center Demand Makes Grid Investment More Important

The battery investment comes as electricity demand is expected to rise. Amazon Web Services operates data centers in Australia, while demand for cloud computing and artificial intelligence continues to grow globally. Data centers require large and reliable supplies of electricity, making access to clean and dependable power increasingly important.

This creates a complicated challenge.

Adding more solar and wind capacity can reduce the carbon intensity of electricity, but these resources do not produce power continuously. At the same time, data centers require electricity around the clock. Battery storage can help manage short-term fluctuations by shifting electricity from periods of abundant supply to periods of stronger demand.

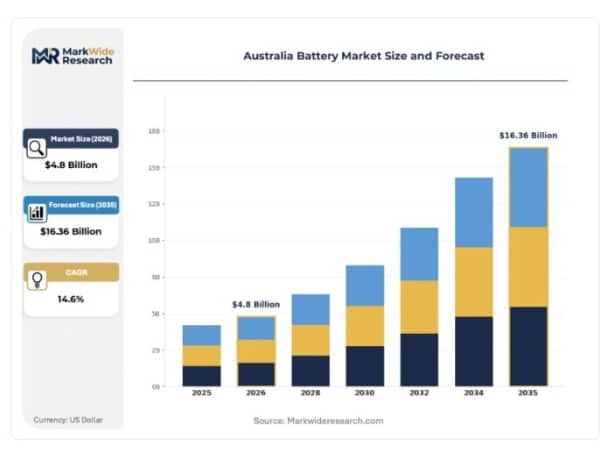
  • Thus, industry forecasts predict the Australian battery market will grow from $4.8 billion in 2026 to $16.36 billion by 2035, with a CAGR of 14.6%.

Australia battery market

For Amazon, this creates a potential double benefit. The company can increase its access to carbon-free electricity while supporting infrastructure that makes the broader grid more capable of absorbing renewable generation.

A Bigger Global Energy Strategy

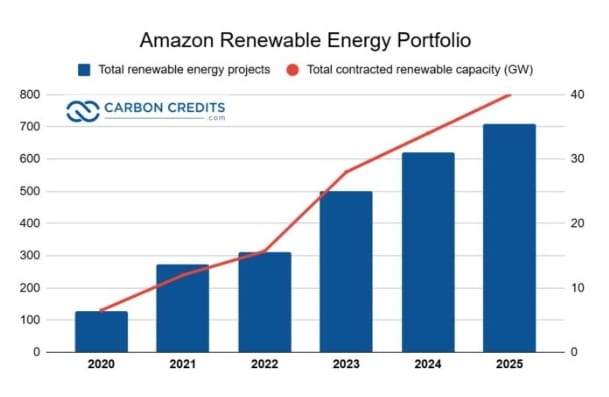
Amazon’s global clean-energy portfolio has grown rapidly. As of January 2026, the company had supported more than 712 carbon-free energy projects across 30 countries. Together, the projects represented about 42 GW of carbon-free energy capacity.

The portfolio includes wind, solar, hydroelectric, geothermal, nuclear power and battery storage.

Amazon says these investments are designed not only to support its own operations but also to bring new energy capacity to the grids where its employees, customers and communities operate.

For investors, the broader trend is worth watching.

The next stage of the energy transition will require more than building wind and solar farms. It will also require batteries, transmission infrastructure, grid connections and other technologies capable of balancing supply and demand.

And the Bairnsdale agreement clearly illustrates this shift.

Extending to Europe

The approach to clean energy also extends well beyond Australia. In Germany, the company has signed an agreement to purchase 600 MW of carbon-free electricity from the Gennaker offshore wind farm in the Baltic Sea. The long-term power purchase agreement gives developer Skyborn Renewables greater certainty over future revenues.

For large renewable projects, such commitments can help developers secure financing and move from planning to construction.

Gennaker is expected to generate enough electricity to power the equivalent of more than one million German households annually once operational.

Amazon has also signed four new power purchase agreements in Sweden. The deals bring its carbon-free energy capacity in the country to nearly 1 GW and increase its portfolio to nine utility-scale wind projects.

These agreements show how corporate buyers can influence renewable energy development beyond their own electricity consumption.

The company is moving from simply purchasing renewable electricity toward investing in the infrastructure needed to make carbon-free power more reliable and useful. As electricity demand from data centers, artificial intelligence and broader electrification grows, that flexibility could become increasingly valuable.

Ultimately, Amazon’s battery investment is not just a clean-energy procurement decision. It reflects a wider shift in the corporate energy market, where companies are increasingly looking beyond renewable generation and toward the infrastructure required to build a more reliable, flexible and lower-carbon electricity system.

The post Amazon’s $2.8 Billion Clean Energy Push in Australia: Why Battery Storage Matters appeared first on Carbon Credits.

Google, Fervo (FRVO Stock) Sign Record Geothermal Deal to Power AI

Google, Fervo (FRVO Stock) Sign Record Geothermal Deal to Power AI

Google is turning to next-generation geothermal power as it expands its artificial intelligence infrastructure. The tech giant and geothermal developer Fervo Energy have signed a 396-megawatt (MW) power purchase agreement (PPA) for Fervo’s Cape Station project in Utah. The deal has a 15-year term and marks the largest enhanced geothermal power purchase agreement to date, according to Fervo.

Power delivery will start in the third quarter of 2028 through four 99 MW blocks. Google also has an option for about 600 MW of additional capacity, which could bring total contracted capacity to roughly 950 MW by June 2030.

The deal comes as AI data centers drive electricity demand higher. It also shows why companies are looking for clean power that can operate around the clock, rather than relying only on variable sources such as solar and wind. Lucia Tian, at Google, remarked:

“The next chapter of advanced power generation technology is being written in Utah. This project will drive meaningful economic benefit to the local community and help catalyze long-term energy cost reductions by making enhanced geothermal more affordable and accessible.”

Google Locks In 396 MW of Next-Gen Geothermal

The agreement covers 396 MW from Fervo’s Cape Station enhanced geothermal system in Beaver County, Utah. Fervo will provide power through four 99-MW blocks, with deliveries starting in Q3 2028. The agreement will run for 15 years.

CEO and Co-Founder of Fervo, Tim Latimer, noted:

“As demand for reliable electricity grows, customers like Google need energy resources that can be deployed at scale, operate around the clock, and deliver where power is needed. This new PPA is part of our repeatable commercial model that enables us to meet customer needs and directly deliver clean, firm power to large electricity users.”

Google has not finalized the location of the Utah data center that could use the power. The company says the geothermal supply would support a potential Utah data center presence, subject to engineering, regulatory, and commercial approvals.

The deal therefore secures power before Google has announced a final data center site.

The tech giant can also choose to buy about 600 MW of additional Cape Station capacity. If it exercises the option and the companies reach final terms, total contracted capacity could reach about 950 MW, with the added capacity guaranteed to operate by June 2030.

The financial terms were not disclosed.

AI Is Creating Demand for Firm Clean Power

The deal comes as data centers become a much larger source of electricity demand. The International Energy Agency expects global data center electricity use to rise from about 415 TWh in 2024 to around 945 TWh by 2030. AI is the main driver of the increase.

Google is already moving quickly to secure more clean energy. The company says it signed contracts for more than 12 GW of new clean energy in 2025, its largest annual total. It also aims to run its data centers and offices on 24/7 carbon-free energy by 2030.

Google carbon-free energy goal 2030
Source: Google

That goal is harder than simply matching yearly electricity use with renewable energy purchases. A data center needs power at night and during periods when solar or wind output is low.

Geothermal can help fill that gap because it can generate electricity continuously.

Fervo’s Enhanced Geothermal Could Unlock New Resources

Traditional geothermal power depends on natural underground conditions. That limits where developers can build projects. Fervo uses enhanced geothermal systems (EGS) to reach heat in hot rock that lacks the natural conditions needed for conventional geothermal plants.

The company uses drilling techniques adapted from the oil and gas industry to create engineered geothermal reservoirs. The approach could allow geothermal development in more places.

The U.S. Energy Information Administration says geothermal plants generated about 16 billion kWh of electricity in 2025, equal to roughly 0.4% of U.S. utility-scale generation. That small share shows how much room geothermal has to grow. If EGS can lower costs and work in more locations, it could become a larger source of firm clean power.

geothermal resources in USA.jpg
Source: US EIA

For AI companies, that could be especially valuable because data centers need reliable electricity around the clock.

Cape Station Is Built to Scale

The Google deal helps move Cape Station from an early project into a much larger commercial development. Fervo’s first phase is about 100 MW.

The company expects its first GeoBlock to begin producing test power in Q4 2026, with full production expected by the end of the year. Its second phase represents about 400 MW and is expected to come online in 2028.

Fervo expects Phase II to reach an installed cost of about $5,500 per kilowatt. Its long-term goal is to reduce that cost to $3,000 per kilowatt.

Lower costs will be critical if enhanced geothermal is to compete with other large-scale clean energy technologies. Fervo says it is using a repeatable GeoBlock design to make future projects easier and cheaper to build.

The company also reported a commercial development pipeline of more than 50 GW at the end of June 2026. It went public last May 2026 on Nasdaq under the FRVO stock ticker. 

Google and Fervo Take Their Partnership to the Next Level

The new agreement builds on a partnership that started in 2021. Google and Fervo developed an enhanced geothermal project in Nevada known as Project Red. Fervo began producing power from the pilot in 2023, supplying electricity to the local grid, including the system serving Google’s Nevada data centers.

In June 2024, Google, Fervo and NV Energy signed a separate 115 MW agreement in Nevada. That deal supported NV Energy’s Clean Transition Tariff, which lets Google help fund new geothermal power while limiting the cost impact on other utility customers.

The Utah agreement now moves the relationship to a much larger commercial scale. It also shows how large technology companies can help emerging clean-energy technologies reach the market by committing to long-term power purchases.

Geothermal Could Fill the Gaps Left by Solar and Wind

The value of geothermal goes beyond supplying one data center. Unlike solar and wind, geothermal plants can operate regardless of weather and time of day. That makes them useful as a steady power source alongside variable renewables.

Google’s clean energy strategy includes solar, wind, hydro, nuclear and geothermal. The company says a mix of clean energy technologies can help supply power when variable renewable sources are not producing enough electricity.

Fervo’s systems could therefore complement growing solar and wind capacity rather than replace it. This could become increasingly important as electricity demand rises from AI, electric vehicles and industrial electrification.

More firm clean power can also reduce the need for fossil-fuel generation during periods of high demand. For carbon markets, the benefit is indirect. The geothermal deal is not a carbon credit purchase. Still, replacing fossil-based electricity with new clean generation can lower the emissions intensity of the power system.

Fervo (FRVO) Stock Jumps on Google Deal

Investors reacted strongly to the announcement. Fervo shares jumped 28.41% to $19.75 on September 1, according to market data, with trading volume reaching about 35.1 million shares. The company went public on Nasdaq in May 2026. 

The rise came after Fervo announced the 396 MW Google agreement.

The market reaction shows how important long-term customer contracts are for an emerging power company. A major buyer such as Google can provide more visibility into future demand and help support financing for large projects.

However, FRVO stock remains highly volatile. Fervo’s projects still face construction, financing, permitting, and operating risks.

Fervo FRVO stock

AI Could Give Enhanced Geothermal Its Breakthrough Moment

The Google-Fervo agreement is a power purchase deal, not a carbon offset transaction. Google is paying for electricity from a new geothermal project. The company is not using the deal as a substitute for direct emissions cuts.

That distinction matters as companies face growing pressure to show that climate claims reflect real changes in energy use, especially AI.

The tech giant says it is working toward 24/7 carbon-free energy by 2030 and continues to invest in new clean generation. Fervo’s deal could help support that goal by adding firm power that can operate when solar and wind output is low.

The geothermal developer also has a major opportunity ahead. Its pipeline exceeds 50 GW, while its long-term cost target is $3,000 per kW.

The next challenge is execution. The company must build projects at scale, control costs, and show that enhanced geothermal can provide reliable power at competitive prices. The Google agreement gives it a major customer and a clearer path to growth.

The bigger story is that AI is creating demand not only for more electricity, but for new forms of reliable, low-carbon power. If Fervo can scale enhanced geothermal as planned, the technology could become an important part of the clean-energy system supporting the next generation of AI infrastructure.

The post Google, Fervo (FRVO Stock) Sign Record Geothermal Deal to Power AI appeared first on Carbon Credits.
Japan Opens New Carbon Credit Channel for India as JCM Enters Article 6 Market Era

Japan Opens New Carbon Credit Channel for India as JCM Enters Article 6 Market Era

Japan and India are moving closer to a working carbon credit market after adopting rules for their Joint Crediting Mechanism (JCM) under Article 6.2 of the Paris Agreement.

The two countries adopted the Rules of Implementation (RoI) on June 8, 2026. The rules create the basic system for approving projects, checking emissions cuts, and issuing and transferring credits. Japan’s Environment Ministry said both sides are still working on some detailed procedures. 

The JCM could bring Japanese finance and low-carbon technology to Indian projects. In return, both countries can share the carbon credits created by those projects.

The move comes as India expands its clean energy sector and Japan builds a wider network of international carbon market partnerships.

Japan and India Turn Carbon Deal Into Action

Japan and India first signed their JCM cooperation agreement on August 7, 2025. The deal created a framework for Japanese and Indian entities to work together on projects that reduce greenhouse gas emissions. 

The 2026 implementation rules now give that framework a clearer structure. India’s Environment Ministry says the rules cover project approval, third-party validation and verification, sustainable development safeguards and national registries for issuing and transferring credits.

A Joint Committee made up of both governments will oversee the mechanism. This is an important step because Article 6.2 requires clear accounting when countries transfer emissions reductions across borders.

Carbon Credit generation article 6
Source: UNFCCC

For Indian developers, the JCM now offers a more defined route to international carbon finance.

India’s Green Projects Get a New Credit Route

The JCM can support projects across several parts of India’s energy and industrial sectors. India and Japan have highlighted areas such as compressed biogas, renewable hydrogen and ammonia, high-emission industries, and carbon capture and storage (CCS). 

Other clean energy and efficiency projects could also qualify if they meet the JCM’s rules. The JCM is not simply a market for existing Indian voluntary carbon credits.

Companies must develop eligible projects under the JCM system. Projects then go through approval, monitoring, validation, and verification before the two countries can issue and share credits. This process is designed to improve the quality and credibility of the resulting credits.

Article 6 Builds a Guardrail Against Double Counting

The JCM operates under Article 6.2, which lets countries transfer mitigation outcomes across borders. A key rule is that both countries cannot count the same emissions reduction toward their climate goals. The India-Japan rules cover these aspects:

  • Credit allocation,
  • Credit issuance, and
  • Corresponding adjustments.

They also require third-party checks of project results. A corresponding adjustment changes a country’s emissions accounting when it transfers a mitigation outcome. This helps prevent double counting.

For buyers and investors, these safeguards can provide more confidence that a credit represents a real and measurable emissions reduction. For India, the system can connect local climate projects with international carbon market demand.

Japan Brings the Capital and Clean-Tech Push

The JCM aims to do more than create carbon credits. Japan’s Foreign Ministry says the mechanism supports the spread of decarbonization technologies and infrastructure through investment by Japanese entities.

The resulting emissions reductions can then be measured and shared between Japan and its partner country. It will also be significant for the country’s decarbonization or net-zero pathway. 

Japan carbon neutrality 2050 McKinsey
Source: McKinsey & Company

This could help Indian projects gain access to Japanese technology, equipment and finance. Japanese companies, in turn, can support emissions cuts outside Japan while receiving a share of the resulting JCM credits.

The model therefore links investment, technology transfer, and carbon markets.

India’s Climate Goals Create Strong Demand

The JCM also fits India’s wider climate plans. The country‘s updated climate target calls for a 47% reduction below 2005 levels by 2035. It also aims to have about 60% of installed electricity capacity from non-fossil sources by 2035.

India separately targets net-zero emissions by 2070. It has already moved past its power-sector target.

Mission 2070 for India net zero goal
Source: SRIRAM’s IAS

The government said non-fossil sources accounted for 54.18% of installed electricity capacity as of June 30, 2026.  India also cut its emissions intensity by 37.38% in 2022 from the 2005 level.

The JCM could help fund further progress in clean energy and hard-to-abate industries.

Japan’s Carbon Network Keeps Expanding

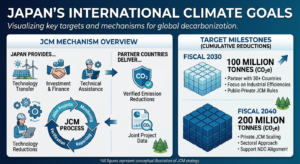
India is part of a much larger Japanese carbon market strategy. As of April 2026, Japan had 32 JCM partner countries. The program had also selected more than 290 projects through its financing program.

India became Japan’s 31st JCM partner in 2025. Oman later became the 32nd partner in April 2026. 

Japan has set an even larger long-term target. It aims to secure about 100 million tonnes of international greenhouse gas reductions or removals by fiscal 2030 and around 200 million tonnes by fiscal 2040 through public-private JCM cooperation. 

Japan climate goals carbon reductions

India could become an important source of projects within that network. The next major step will come in New Delhi.

  • Japan and India plan to hold the India Forum: Advancing International Carbon Markets for Climate Ambition, Sustainable Development and Shared Prosperity on September 28, 2026.

The event will focus on India’s international carbon markets and Article 6 implementation.

One session will focus on the India-Japan JCM under Article 6.2. The two governments plan to explain the new rules and encourage Indian and Japanese companies to develop projects. The timing is important because the basic JCM rules are now in place.

India’s Homegrown Carbon Market Adds Another Route

The JCM is also arriving as India develops its own domestic carbon market. The country has been building its Carbon Credit Trading Scheme (CCTS) to encourage companies to cut emissions and create a national carbon market.

The JCM and CCTS are separate systems. But they could give Indian companies different routes to finance emissions reduction projects.

Developers will need to understand which projects qualify for each market and how international transfers affect emissions accounting. This will become more important as India expands its links with global carbon markets.

The new system creates an opportunity, but it does not guarantee valuable credits. Projects must prove that they deliver real emissions reductions or removals. They must also meet the JCM’s rules for monitoring, reporting, validation, and verification.

The 2026 RoI includes third-party validation and verification and sustainable development safeguards. Strong project data will therefore be important from the start.

For buyers, the value of the JCM will depend on whether it can produce credits that meet Article 6 rules and maintain environmental integrity.

A New Carbon Bridge Between Japan and India

The India-Japan JCM has now moved beyond a basic cooperation agreement and into implementation. The adoption of the Rules of Implementation gives both countries the core procedures needed to operate their Article 6.2 carbon credit system.

For India, the mechanism could bring more Japanese investment and technology into renewable energy, clean fuels, industrial decarbonization and CCS. For Japan, it creates another source of international mitigation outcomes while supporting its wider JCM network.

The market is still at an early stage. Both countries are working on further details, and actual credit supply will depend on how quickly companies develop and verify projects.

The September 28 India JCM Forum could help turn the new rules into a stronger project pipeline. If India and Japan can build a steady flow of high-quality projects, the JCM could become an important Article 6 channel for bringing Japanese climate finance into India’s energy transition.

The post Japan Opens New Carbon Credit Channel for India as JCM Enters Article 6 Market Era appeared first on Carbon Credits.
Shein Goes Public at $26.5B, a 73% Drop in Valuation as Fashion Giant Faces a Net-Zero Test

Shein Goes Public at $26.5B, a 73% Drop in Valuation as Fashion Giant Faces a Net-Zero Test

Chinese fast fashion company Shein has finally debuted on the Hong Kong stock market, giving investors insight into one of the largest online fashion retailers. However, the fashion giant is facing slower growth, stricter trade rules, and a significant emissions footprint.

Shein began trading on September 1, 2026, under stock code 0625 on the Hong Kong Stock Exchange. The company priced its IPO at HK$48.56 per share, raising about HK$13.6 billion (US$1.7 billion) and valuing the business at roughly US$26.5 billion.

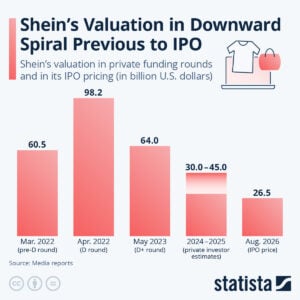
That valuation is far below Shein’s US$98.2 billion private valuation in 2022, a drop of about 73%.

The weaker valuation reflects slower growth and growing pressure on Shein’s business model. At the same time, the company faces another challenge: cutting emissions across a global supply chain that produces most of its carbon footprint.

Shein’s $98 Billion Valuation Comes Crashing Down

Shein’s public debut marks a major reset in how investors value the company.

Private investors valued Shein at US$98.2 billion in April 2022. That fell to about US$64 billion in 2023 and later to roughly US$45 billion to US$55 billion in 2024 and 2025 private transactions.

The Hong Kong IPO values the company at about US$26.5 billion. Shein offered about 280 million Class B shares at HK$48.56 each.

The lower valuation comes as Shein faces weaker growth, rising costs, and changes to low-value import rules in key markets. These factors have put pressure on the fast-fashion model that helped drive its rapid expansion.

Shein IPO valuation

Growth Slows as Profits Take a Hit

Shein generated US$41.85 billion in revenue in 2025, up about 8% from 2024. That was much slower than the 20.7% growth recorded in 2024.

Profit also weakened. Net income fell 38.7% to US$2.06 billion in 2025, from US$3.37 billion in 2024.

The slowdown continued in early 2026. First-quarter revenue rose just 1.1% to US$9.05 billion, while Shein reported a US$99 million net loss. A US$328 million fair-value loss linked to convertible preferred shares was a major factor in that loss.

The U.S. market became a particular challenge. Shein’s U.S. revenue fell 14.3% to US$2.04 billion in the first quarter of 2026. The U.S. accounted for 22.5% of quarterly revenue, down from 29.4% of annual revenue in 2023.

However, slower growth does not automatically mean a smaller environmental footprint. Shein still operates at a very large scale, also increasing its carbon footprint. 

Shein Sets a 2050 Net-Zero Goal

Shein has set climate targets approved by the Science Based Targets initiative (SBTi). The company aims to reach net-zero greenhouse gas emissions across its value chain by 2050, using 2023 as its base year.

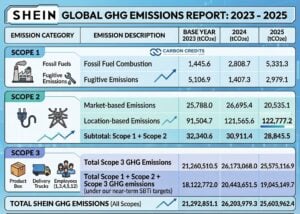
Shein GHG carbon emissions 2025

By 2030, Shein plans to:

  • Cut absolute Scope 1 and 2 emissions by 42%
  • Cut absolute Scope 3 emissions by 25%
  • Source 100% of electricity used in directly managed operations from renewable sources

By 2050, Shein aims to cut absolute Scope 1 and 2 emissions by 90% and Scope 3 emissions by 90%, before addressing remaining emissions in line with the SBTi framework.

The targets cover emissions from Shein’s operations as well as its supply chain, including purchased goods, transport, waste and sold products.

The Supply Chain Drives Shein’s Carbon Footprint

Shein’s biggest climate challenge sits outside its own facilities. The company says purchased goods and services and upstream transportation and distribution accounted for about 96% of emissions covered by its near-term Scope 3 targets in 2025. That includes emissions from producing fabrics and garments and moving products through the supply chain.

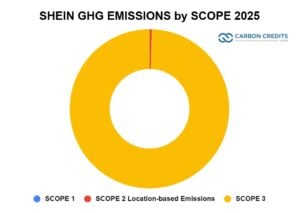
Across all years, from 2023 to 2025, Scope 3 emissions comprise nearly 99.9% of Shein’s entire corporate carbon footprint. This means the vast majority of their climate impact occurs outside their direct operations.

Shein ghg emissions 2025 by scope
Data from Shein

The fashion retailer reported progress in 2025:

  • Its measures in purchased goods and services were estimated to avoid 316,842.8 tonnes of CO2e, up 59.2% from 2024.
  • Transport-related measures produced estimated avoided emissions of 604,868.0 tonnes of CO2e in 2025, down from 668,800 tonnes in 2024.

These are estimated emissions avoided through specific projects, not a reduction in Shein’s total Scope 3 emissions.

Renewable Electricity Reaches 85%

Shein is also cutting emissions from its own facilities. The company used 275,723.2 MWh of electricity across its globally managed operations in 2025, up 13.3% from 2024.

The share of electricity purchased from renewable sources rose to 85.1%, from 76% in 2024. Shein also expanded its solar capacity to 93.9 MW across 16 facilities by the end of 2025, a 66.8% increase from 2024.

The company consumed 36,909.5 MWh of solar electricity in 2025 and estimated that it avoided 19,576.4 tonnes of CO2e.

Shein also introduced 78 energy-efficiency measures across 22 facilities in China. It estimates those measures saved 33,581 MWh of electricity and cut emissions by 19,934.1 tonnes of CO2e in 2025.

Shein Targets Materials, Packaging and Freight

The company is also targeting emissions tied to its products and logistics. In 2025, 9.2% of polyester directly sourced for Shein-branded products was recycled, up from 6.7% in 2024. Shein estimates this reduced emissions by 48,664.2 tonnes of CO2e.

For packaging, 19.7% of plastic packaging purchased for Shein-branded products contained at least 50% recycled polyethylene, up from 17.0% in 2024. Shein estimates this work avoided 5,647 tonnes of virgin plastic.

The company also shifted some deliveries from air freight to sea freight and trucking and used 125 electric or lower-fuel-consumption vehicles in warehousing and distribution in 2025.

Shein also tested 187.3 tonnes of sustainable aviation fuel across 14 Atlas Air charter flights, which it estimates avoided 579.1 tonnes of CO2e.

Carbon Removals Wait Until the Endgame

Shein’s net-zero strategy does not rely on carbon credits as its main way to meet near-term targets. The company says it plans to reduce emissions deeply across its operations and value chain first. It expects to address remaining emissions through carbon removals as it approaches its 2050 goal.

That approach fits the SBTi net-zero framework, which places deep emissions reductions ahead of neutralizing residual emissions.

For carbon markets, Shein could eventually become a buyer of high-quality carbon removal credits. But its future demand will depend on how much residual emissions remain after it meets its reduction targets.

Public Investors Will Watch Climate Progress

Shein’s IPO brings greater public attention to its environmental performance. The company says its 2025 Scope 1, 2 and 3 inventory received independent verification from Bureau Veritas under ISO 14064-1:2018 and the GHG Protocol.

The fashion giant also says it is working with suppliers on energy efficiency and renewable power and developing a wider decarbonization roadmap. Its scale makes that work significant. Shein served about 273 million active customers across roughly 160 markets in 2025.

The company therefore faces a difficult balance. It must maintain growth while reducing emissions across a supply chain that it does not fully control.

Shein’s IPO Is Also a Climate Test

Shein’s Hong Kong debut has put a public market value on a company whose valuation has fallen sharply from its US$98.2 billion peak in 2022 to about US$26.5 billion.

At the same time, Shein has committed to cut Scope 1 and 2 emissions by 42% and Scope 3 emissions by 25% by 2030, followed by 90% reductions across both categories by 2050.

The biggest challenge will be its supply chain, where most of its emissions occur.

As Shein enters public markets, investors will have more data to assess whether its sustainability efforts keep pace with the scale of its business. The key test will be whether Shein can deliver continued growth while making real, measurable cuts across the supply chain behind its global fast-fashion business.

The post Shein Goes Public at $26.5B, a 73% Drop in Valuation as Fashion Giant Faces a Net-Zero Test appeared first on Carbon Credits.
CF Industries, JERA and Mitsui Break Ground on $3.7 Billion Low-Carbon Ammonia Plant in Louisiana

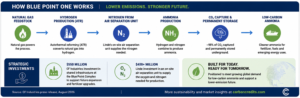
CF Industries, JERA and Mitsui are moving ahead with one of the world’s largest low-carbon ammonia projects, as demand grows for cleaner fertilizer and lower-emission energy products. The three companies have broken ground on the Blue Point One ammonia plant in Modeste, Louisiana. The project represents a $3.7 billion investment and is expected to produce 1.4 million metric tons of ammonia annually when it begins operations in 2029.

The scale is significant. Blue Point One is expected to become the world’s largest ammonia plant once operational, while creating more than 100 permanent manufacturing jobs and an estimated 3,900 construction jobs over four years.

U.S. Secretary of Agriculture Brooke Rollins joined federal, state and local officials at the groundbreaking, highlighting the project’s importance to both domestic agriculture and America’s industrial base. For investors, however, the bigger story is the project’s position at the intersection of fertilizer security, carbon capture and the emerging global market for low-carbon ammonia.

us ammonia

A Major Bet on U.S. Ammonia Production

CF Industries owns 40% of Blue Point One, while Japan’s JERA owns 35% and Mitsui holds the remaining 25%.

The companies are targeting 2029 for the start of production. The plant will use autothermal reforming, or ATR, to produce hydrogen, which is then combined with nitrogen to make ammonia.

  • The key difference is what happens to the carbon dioxide generated during production.

Blue Point One Targets 98% CO₂ Capture

Blue Point One is designed to capture and permanently store about 98% of the CO₂ produced by the facility. A joint venture between Occidental subsidiary 1PointFive and Enbridge will handle the transportation and permanent sequestration of the captured carbon.

That could give the project one of the lowest carbon footprints among large-scale ammonia facilities.

The project is also designed to serve two markets. Traditional customers will use the ammonia for fertilizer, while emerging applications could include low-carbon fuels and energy-related uses.

That flexibility matters because ammonia is moving beyond its traditional role in agriculture.

Around 70% of global ammonia production is currently used for fertilizer, but the molecule is increasingly being considered as an energy carrier and fuel for sectors that are difficult to electrify.

CF Industries and Linde Create Expansion Potential

CF Industries is making another $550 million investment at the Blue Point Complex over the next four years. The spending will support shared infrastructure that can accommodate future ammonia production and fertilizer upgrades.

This creates an important option for expansion. Rather than building every piece of infrastructure from scratch for future projects, the companies can use the shared facilities already being developed around Blue Point One.

Linde is also investing more than $400 million in an on-site air separation unit. The facility will supply the oxygen and nitrogen needed for ammonia production.

Together, these investments create a broader industrial platform rather than a standalone ammonia plant. This could become increasingly valuable if demand for low-carbon ammonia accelerates through the end of the decade.

CF Industries President and Chief Executive Officer Chris Bohn said,

“We are proud to break ground on the Blue Point One joint venture, a transformative project that brings together American energy resources, world-class engineering and partnerships, and trusted global allies. Most importantly, this facility will serve people, growing access to the reliable, domestic nitrogen supply American farmers need to feed the world, expanding our nation’s export capacity through shipping American-made energy to global markets and creating jobs in Louisiana.”

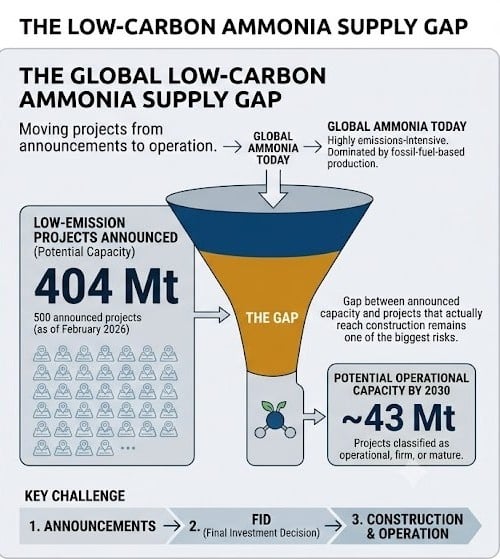
Global Low-Carbon Ammonia Demand Is Growing, but Supply Is Still Limited

The timing of Blue Point One reflects a broader shift in the ammonia industry.

Global ammonia production is highly emissions-intensive. The International Energy Agency estimates that direct emissions from ammonia production are around 450 million metric tons of CO₂ annually. More than 70% of production currently relies on natural-gas-based steam reforming, with much of the remainder produced using coal.

At the same time, demand for ammonia is not disappearing. Population growth and rising food demand are expected to support continued fertilizer consumption, while new markets could emerge in shipping, power generation and other energy applications.

The supply side, however, remains at an early stage.

  • The IEA says announced and existing near-zero-emission ammonia projects have been expanding, but low-emission production remains a small share of the global market.
  • A 2025 assessment found that low-emissions ammonia projects for fertilizer accounted for about 19 million tonnes of production capacity, including operational projects that had reached final investment decision or completed feasibility studies.

The project pipeline is much larger than current operating capacity. The Ammonia Energy Association identified 500 announced low-emission and transitional ammonia projects as of February 2026, representing 404 million tonnes of potential capacity. However, only about 43 million tonnes of that capacity could be operational by 2030 based on projects classified as operational, firm, or mature.

This gap between announced capacity and projects that actually reach construction remains one of the biggest risks for the sector.

ammonia supply gap
Source: IEA

JERA Connects Blue Point One to Global Markets

JERA’s involvement also gives Blue Point One an international dimension. It is Japan’s largest power generation company and a major player in the global energy market. Founded in 2015, it supplies about one-third of Japan’s electricity and ranks among the world’s largest buyers of liquefied natural gas (LNG).

The company operates across the energy supply chain, from gas exploration and LNG projects to fuel procurement, transportation and power generation. JERA is also expanding its focus on lower-carbon energy as part of its transition strategy. It aims to reach net-zero CO₂ emissions across its domestic and international operations by 2050.

JERA Global Energy Solutions Chief Executive Officer, JERA Senior Managing Executive Officer, Chief Operating Officer of Low Carbon Fuels Business Irtiza Sayyed:

“Today’s groundbreaking marks an important milestone for Blue Point One and brings us one step closer to establishing a reliable low-carbon ammonia value chain. At JERA, we believe that energy transition must be supported by practical projects and strong partnerships across the value chain. Blue Point One reflects this belief, bringing together partners with a shared commitment to build the foundation needed to scale lower-carbon ammonia for the future.”

Japan is one of the countries exploring ammonia as part of its strategy to reduce emissions from power generation and diversify energy supplies. Ammonia can be transported using established shipping infrastructure, making it easier to move between production hubs and overseas markets than hydrogen in some applications.

The IEA expects long-term bilateral contracts to play an important role in emerging hydrogen and ammonia trade, particularly because buyers need confidence that low-carbon fuel supplies will actually be delivered.

That creates an opportunity for U.S. producers with access to natural gas, carbon-storage infrastructure and export terminals.

Blue Point One brings those elements together.

Cost Remains the Critical Question

Low-carbon ammonia still has to compete with conventional production on price.

The IEA estimates that natural gas-based ammonia with carbon capture could reach production costs of roughly $230 to $440 per tonne by 2030 in regions with low-cost gas and suitable CO₂ storage. Electrolysis-based production could cost roughly $400 to $620 per tonne in regions with excellent renewable resources.

That makes carbon capture an important route for scaling lower-carbon ammonia, particularly in regions such as the U.S. Gulf Coast where natural gas, industrial infrastructure and potential CO₂ storage resources are available.

The economics could improve further as carbon prices, clean-fuel standards and corporate demand create premiums for lower-emission ammonia.

Blue Point Could Become a Platform for Future Growth

The biggest investment takeaway may not be the 1.4 million tonnes of annual production alone.

The additional infrastructure spending gives CF Industries and its partners room to expand the site as demand develops. That optionality could become valuable if fertilizer customers increasingly seek lower-carbon products or if shipping and power markets begin adopting ammonia at a larger scale.

All in all, the project therefore sits at the center of several major investment themes: U.S. manufacturing, fertilizer security, carbon capture, energy exports and the development of low-carbon fuels. The real test will come after groundbreaking. Blue Point One must move from construction to reliable production while proving that large-scale ammonia can be made with significantly lower emissions at a competitive cost.

If it succeeds, Louisiana could become an important hub in the next generation of global ammonia supply.

The post CF Industries, JERA and Mitsui Break Ground on $3.7 Billion Low-Carbon Ammonia Plant in Louisiana appeared first on Carbon Credits.