UK’s $541 Million Forest Bet: Can Brazil’s TFFF Turn Tropical Forests into Climate Assets?

The United Kingdom will provide a £400 million ($541 million) loan to Brazil’s Tropical Forests Forever Facility (TFFF). This funding aims to help make tropical forest conservation a long-term financial asset.

This commitment arises as governments look for new ways to fund climate action while managing public spending. Unlike a traditional grant, the UK’s support will be a loan. This shows a shift toward using repayable financing for some international climate investments. However, this assurance depends on final due diligence, governance, and operational arrangements.

The announcement could also help the Brazil-led fund reach its first major financing milestone. The TFFF is targeting $10 billion in public funding during its first year and has already secured almost three-quarters of that amount, according to Reuters. The $10 billion target is to be reached by the end of 2026.

The wider ambition is considerably larger. The facility ultimately aims to mobilize $125 billion, including $25 billion from governments and public institutions.

Why the UK’s TFFF Loan Matters

The UK supported the TFFF concept when it was launched at the COP30 climate summit in Belém, Brazil, but initially stopped short of committing taxpayer funding. But this position has now changed.

The UK government said it intends to invest £400 million through a loan, although

The structure allows Britain to participate without providing the money as a traditional grant. It also reflects a broader debate around international climate finance, as developed economies face pressure to increase funding for climate and nature protection while demonstrating that public money is being used efficiently.

For the TFFF, the UK commitment is important because the facility depends on large pools of long-term capital rather than one-off conservation grants.

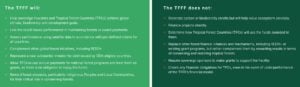
Notably, the TFFF is designed to operate as a long-term financing mechanism that provides predictable, performance-based payments to countries that maintain their tropical forests. The facility says it could support more than 70 tropical forest countries covering more than 1 billion hectares of moist tropical and subtropical broadleaf forests.

TFF tropical forest fund
Source: TFF

Turning Standing Forests Into a Financial Asset

The central idea behind the TFFF is relatively simple: countries should receive more financial value from keeping forests standing than from clearing them.

Traditional development finance has often struggled to compete with the economic incentives of agriculture, mining, timber, and other land uses.

The TFFF attempts to change that equation by creating a long-term financial reward for forest conservation.

Countries that meet forest-protection requirements can receive annual payments based on their conservation performance. The facility says these payments are intended to be predictable and long-term rather than dependent on short-term project grants.

That makes the model particularly relevant to the carbon market, although the TFFF is not simply another carbon-credit scheme.

Instead, it can complement existing mechanisms such as REDD+ and forest carbon markets. TFFF official overview

This distinction matters. Carbon markets generally place a financial value on quantified emissions reductions or removals. The TFFF takes a broader approach by creating financial incentives for countries to maintain standing forests and the ecosystem services they provide.

Forests Are a Major Carbon Removal Engine

The climate case for the initiative is strong.

Forests absorb carbon dioxide through photosynthesis and store carbon in trees, vegetation, roots, and soils. The World Resources Institute estimates that forests remove around 16 billion tonnes of CO₂ from the atmosphere each year. This highlights their importance as a natural carbon sink.

The global forest carbon sink is enormous, but it is not guaranteed to remain that way.

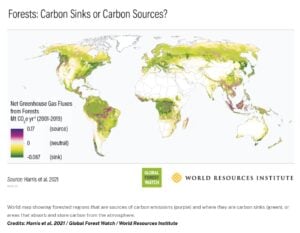
Deforestation, degradation, fires, and climate-related stresses can reduce the ability of forests to absorb carbon. In some cases, damaged forests can shift from being carbon sinks to becoming sources of emissions.

This is why protecting existing tropical forests can be an important part of climate strategy.

forest carbon emission

The distinction between carbon removal and avoided emissions is also important.

When a forest continues growing and absorbs additional CO₂ from the atmosphere, that represents carbon removal. When an existing forest is protected from being cleared, the primary climate benefit is the avoidance of emissions that would have occurred if stored carbon had been released.

Both outcomes are valuable, but they should not be treated as identical forms of carbon removal.

Why Protecting Existing Forests Matters

Tropical forests play a particularly important role in the global carbon cycle.

They store enormous amounts of carbon while supporting biodiversity, regulating rainfall and providing livelihoods for millions of people. They currently hold 861 gigatonnes of carbon in their branches, leaves, roots, and soils. However, measuring forest carbon is becoming more complicated as climate change alters forest ecosystems.

Recent research suggests some tropical forest regions have experienced shifts in their carbon-storage capacity, reinforcing the importance of protecting forests while they remain functioning carbon sinks.

For carbon markets, this creates both an opportunity and a challenge.

brazil tropical forest

Forest conservation can deliver significant climate benefits, but accurately measuring additional carbon storage, preventing leakage and ensuring permanence remain critical to maintaining the credibility of forest-based climate finance.

TFFF Could Strengthen Forest Climate Finance

The TFFF is attempting to address part of this financing gap by treating forests as a long-term economic asset.

Its proposed structure combines public and private capital. The broader initiative aims to mobilize $125 billion, with roughly $25 billion expected from governments and public institutions and the remainder from private sources. World Resources Institute: TFFF financing model

The capital would generate investment returns that can help fund payments to tropical forest countries.

That structure is important because forest conservation requires funding year after year.

Deforestation pressures do not disappear after a single grant cycle. Farmers, communities, governments and forest managers need sustained economic incentives to keep forests standing.

The TFFF therefore seeks to create a more predictable source of finance while shifting the economic value of forests toward conservation.

The Next Test Is Mobilizing More Capital

The UK commitment is significant, but it is only one part of the larger financing challenge.

The TFFF still needs to build the capital base required to reach its ultimate $125 billion target. Reaching the initial $10 billion public-finance goal could be an important signal to other governments and institutional investors.

Reuters reported that reaching that first target could also help unlock additional funding, including potential support from the United States.

The facility’s success could influence future approaches to nature and carbon finance. If countries can demonstrate that long-term investment returns can support predictable payments for maintaining forests, similar models could emerge for other ecosystems.

The UK’s investment remains subject to final due diligence, including reviews of the facility’s final size, governance, structure and loan terms.

For tropical forests, however, the underlying message is already clear: protecting carbon-rich ecosystems increasingly needs to be treated not just as an environmental responsibility, but as a long-term financial investment.

The post UK’s $541 Million Forest Bet: Can Brazil’s TFFF Turn Tropical Forests into Climate Assets? appeared first on Carbon Credits.

Gold Standard Launches Green Hydrogen Methodology to Generate Carbon Credits

Gold Standard Launches Green Hydrogen Methodology to Generate Carbon Credits

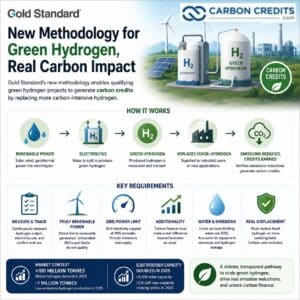
Gold Standard has launched a new methodology that allows qualifying green hydrogen projects to generate carbon credits when they replace more carbon-intensive hydrogen production. The methodology covers hydrogen made through water electrolysis using renewable electricity. It can support both new projects and upgrades at existing industrial sites.

The new framework gives hydrogen developers another way to attract carbon finance. It also sets strict rules for renewable power, additionality, water use, and emissions accounting.

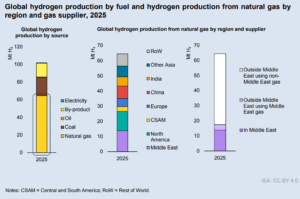
The move comes as global hydrogen demand grows, while low-emissions production remains small. The International Energy Agency (IEA) reports that global hydrogen demand exceeded 100 million tonnes in 2025. Meanwhile, low-emissions hydrogen production stayed around 1 million tonnes.

Gold Standard Targets Hydrogen’s Fossil Footprint

Gold Standard’s Green Hydrogen Production methodology applies to projects that make hydrogen through electrolysis and use renewable electricity. The rules cover both greenfield projects, which build new green hydrogen plants, and brownfield projects, which add electrolysers to existing industrial facilities and replace fossil-based hydrogen.

Eligible projects can serve existing industrial users that previously relied on hydrogen made from coal, oil, or natural gas. The methodology can also cover new uses where green hydrogen replaces a more polluting fuel.

Credits depend on the amount of qualifying green hydrogen actually produced and used. A project, therefore, cannot claim credits simply because it has an electrolyzer or uses renewable power.

Every Kilogram of Hydrogen Must Be Accounted For

Gold Standard puts a strong emphasis on direct measurement. Projects must measure the electricity used and the amount of hydrogen produced. They must also show where the hydrogen goes and confirm that the end use qualifies for credit.

The methodology requires continuous measurement of hydrogen production using equipment such as mass flow meters or precision load cells. Projects must also track hydrogen delivered or sold to eligible users.

If developers cannot prove that a certain volume went to a qualifying end use, that volume cannot generate credits. This approach helps reduce the risk of overstating emissions reductions.

Green Hydrogen Must Prove Its Power Is Truly Renewable

The methodology also sets detailed rules for renewable electricity. Projects can use renewable power from sources such as solar, wind, and geothermal energy. They must prove where the power comes from and show a clear link between renewable generation and hydrogen production.

Simply buying unbundled renewable energy certificates, or RECs, does not qualify.

Gold Standard states that unbundled RECs and guarantees of origin can’t count as renewable electricity. This is because they lack a direct link to the electricity used by the hydrogen plant.

Off-site renewable projects can provide power with a power purchase agreement (PPA); however, they need to meet extra requirements.

For example, the renewable project generally must begin commercial operation within 24 months of the hydrogen facility’s start date. Gold Standard can extend that period by up to 12 months, giving a maximum of 36 months in documented cases outside the developer’s control.

The methodology also moves toward hourly matching between renewable generation and hydrogen production as tracking systems become available.

Gold Standard green hydrogen methodology and carbon credits

Grid Power Gets a Strict 10% Limit

Some grid electricity is allowed, but only in limited amounts. A project can use grid power when renewable supply is not enough, but grid electricity cannot exceed 10% of total annual electricity use.

Gold Standard also applies different emissions rules based on the grid’s carbon intensity. If the grid emissions factor is below 0.2 tonnes of CO2e per MWh, related hydrogen can still qualify as green under the methodology.

If the grid factor reaches or exceeds 0.2 tCO2e/MWh, the project must count the actual emissions linked to that grid electricity. These rules lower the risk of a project using lots of fossil-heavy grid power. This way, it can’t falsely claim credits for zero-emission hydrogen.

Carbon Finance Must Make a Real Difference

Gold Standard also requires developers to show that carbon finance helps make the project possible. The methodology looks at financial conditions, common practices, legal requirements, and lock-in risks.

Projects must also complete an ongoing assessment of their financial needs. This matters because green hydrogen projects may receive subsidies, tax benefits, or other government support.

The rules aim to prevent credits from rewarding emissions reductions that would have happened anyway.

Gold Standard also applies a Downward Adjustment Factor (DAF) to the crediting baseline. The factor considers the host country’s official net-zero target and lowers the baseline over time. This makes the crediting system more conservative as national climate policies strengthen.

Water and Supply Chain Emissions Matter

Water use is another part of the methodology. Electrolysis needs water, which can create pressure in areas that already face water shortages. Gold Standard limits the share of local drinking water use to 5% and requires checks on water availability and hydrological risks.

The methodology also accounts for emissions from equipment used to produce green hydrogen. Developers must consider emissions linked to the manufacture and transport of electrolysers, solar panels, wind turbines, and battery systems during the first crediting period.

The rules also account for hydrogen leakage. Gold Standard uses a 100-year global warming potential of 14.4 for hydrogen when calculating those emissions. That makes the methodology broader than simply comparing green hydrogen with fossil hydrogen at the production plants.

Credits Require Proof of Real Fossil Fuel Displacement

The methodology focuses on actual changes in how hydrogen and energy are produced. Developers must prove that current industrial users have used fossil-based hydrogen for at least three years before they can switch to green hydrogen.

Some uses are excluded entirely. Projects can’t get credits for green hydrogen used in:

  • enhanced oil recovery, 
  • unconventional fossil fuel extraction or processing, and
  • untargeted blending into natural gas networks.

For new hydrogen demand, developers must show that green hydrogen replaces a more emissions-intensive fuel or conventional hydrogen. These rules make the emissions benefit easier to measure and help strengthen the additionality case.

Hydrogen Demand Surges While Clean Supply Lags

The new methodology enters the market as hydrogen demand continues to rise. The IEA reports that global hydrogen demand topped 100 million tonnes in 2025. However, low-emission hydrogen production was only about 1 million tonnes. The agency says low-emissions production grew 20% in 2025, showing progress but also a large gap with overall demand.

global hydrogen production 2025 from IEA

Electrolysis capacity is also growing. The IEA reports that global electrolyser capacity doubled in 2025, exceeding 4 GW. Additionally, over 2.5 GW of new capacity is being built for operation in 2026.

However, the industry still faces high costs, limited infrastructure, and uncertain demand. Carbon finance could help some projects close part of the cost gap. Still, carbon credits alone are unlikely to make green hydrogen competitive in every market.

Green Hydrogen Gets a New Carbon Finance Route

Gold Standard’s new methodology gives green hydrogen developers a clearer path to carbon finance. The rules call for directly measuring hydrogen output. They also set strict renewable power needs. Lastly, projects must prove they replace more carbon-heavy hydrogen or fuels. 

If carbon finance can support more green hydrogen projects, the methodology could help expand low-carbon supply in industries such as refining, chemicals, ammonia, and steel. Yet, developers still need customers, renewable electricity, infrastructure, and financing.

Gold Standard’s framework does not guarantee a flood of new credits. It creates a stricter path for projects to prove that green hydrogen replaces real sources of emissions and delivers measurable climate benefits.

The post Gold Standard Launches Green Hydrogen Methodology to Generate Carbon Credits appeared first on Carbon Credits.

Europe’s Wildfires Release 27 Million MT of CO2 as France Sets New Emissions Record

Europe’s Wildfires Release 27 Million MT of CO2 as France Sets New Emissions Record

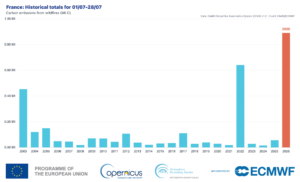
Wildfires have released an estimated 27 million metric tons of carbon dioxide (MtCO2) across Europe so far in 2026, with France accounting for a record amount of emissions, according to the European Union’s Copernicus Atmosphere Monitoring Service (CAMS).

The fires are creating a growing climate risk. They are not only releasing carbon stored in forests and other ecosystems. They can also weaken Europe’s ability to absorb emissions through its land and forests.

France has been one of the clearest examples. CAMS reported that French fires produced 0.89 million tons of carbon (Mt C) during July alone, the highest July level in its record. The previous July record was 0.64 Mt C in 2022.

France’s Fires Set a Record as Europe Burns

The scale of France’s fires reflects an unusually hot and dry summer across parts of Western Europe. CAMS uses satellite observations and its Global Fire Assimilation System to estimate emissions from fires in near real time. Its data showed that France had its highest annual fire emissions through the end of July in the available record.

France wildfire September 2026
Source: Copernicus Atmosphere Monitoring Service

The wider 2026 fire season has also been severe. EU data from the European Forest Fire Information System showed that 647,375 hectares had burned in the EU by September 2. This was due to 1,913 fires, each larger than 30 hectares.

The burned area in 2025 was lower than in the past, which was the EU’s worst year. Still, it was above the average of about 328,000 hectares from 2006 to 2025. This means the 27 MtCO2 emissions figure is part of a broader pattern of widespread fire activity rather than a single extreme event.

Climate Change Is Raising Fire Risk

Researchers say climate change is increasing the conditions that allow large fires to develop.

A World Weather Attribution study found that human-caused warming made extreme fire conditions in southwest France and central Spain more likely in 2026. The analysis linked the high fire risk to a combination of extreme heat, unusually low rainfall and severe soil moisture deficits.

In southwest France, conditions of similar severity are now expected about once every 20 years. In central Spain, they are expected roughly once every six years.

spain wildfire carbon emissions 2026
Source: World Weather Attribution

Researchers found that climate change has boosted extreme fire weather. In southwest France, such severe conditions are now at least twice as likely. In central Spain, they are at least 20 times more likely.

Land management can also affect fire behavior. Forest structure, vegetation, population patterns, and land use all influence how quickly fires spread. This means climate change is an important driver, but not the only one.

Europe’s Forest Carbon Sink Is Losing Strength

The wildfire problem matters to carbon markets because forests and other land ecosystems are a major part of Europe’s climate strategy.

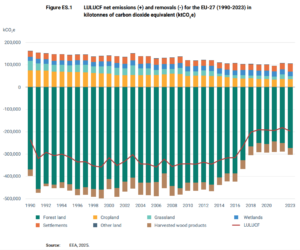
The EU’s land-use, land-use change and forestry sector, known as LULUCF, removed a net 198 MtCO2e in 2023, equal to about 6% of EU greenhouse gas emissions. The European Environment Agency (EEA) noted that the sector’s carbon sink has weakened. The average annual sink from 2014 to 2023 is about 30% lower than in the previous decade.

LULUCF net emissions and removals for the EU-27
Source: EEA

Wildfires are one factor behind that decline. Fires can quickly release carbon stored in vegetation and soils, reducing the amount of carbon that land can absorb.

The EEA has warned that more frequent and severe disturbances, including wildfires and drought, are affecting Europe’s forest carbon stocks. That creates a challenge for Europe’s climate goals.

  • The EU aims for a 310 MtCO2e net-removal target for the LULUCF sector by 2030. However, current national projections show that existing measures won’t meet this goal.

Wildfires Put Forest Carbon Credits to the Test

The growing fire risk has serious implications for nature-based carbon projects. Forest and reforestation initiatives depend on carbon remaining stored for decades.

However, a major wildfire can instantly destroy that stored carbon. When projects burn, carbon standards do not penalize individual corporate buyers. Instead, registries rely on “buffer pools”—shared insurance reserves of carbon credits that are permanently retired to cancel out the losses.

Real-world data shows that these safety nets are under severe strain from modern climate realities. Actuarial analyses of the California Air Resources Board (CARB) compliance program reveal that wildfires have triggered massive credit cancellations. For example, a single event—the Lionshead Fire—alone reversed 963,534 credits.

This is part of a much larger systemic threat. A landmark study by CarbonPlan and UC Berkeley found that California’s program set aside about 6.8 million credits. This amount covers wildfire risk for a century across its entire portfolio.

By 2024, cumulative losses from devastating fire seasons had blown past 10.7 million credits. The program effectively exhausted its hundred-year wildfire insurance pool decades ahead of schedule.

VCM registries face similar pressure. Premier international registries like Verra maintain global buffer accounts comprising tens of millions of tons of CO2.

When major projects fail, like the Colville Indian Reservation forest project in Washington, registries must freeze or cancel millions of credits. This helps keep corporate buyers protected.

Future Fire Risk Could Surge Nearly 200%

New research suggests that Europe’s wildfire problem could become significantly worse later this century without stronger climate action and fire management.

A study in Global Change Biology, led by the Potsdam Institute for Climate Impact Research, found that intense fire weather could raise Europe’s annual burned area by 39% by the end of the century in a low-emissions scenario. Under a high-emissions scenario, the increase could reach about 192%, or nearly three times current levels.

The researchers also found that better prevention, early detection, and firefighting could greatly reduce the increase. Improvements in fire management can cut burned area by 72% to 92%. This depends on the situation. Even so, stronger fire management would not fully offset the effects of severe climate change.

The study highlights an important point for carbon markets. Protecting forests cannot rely only on planting more trees. Projects also need to consider whether those forests can survive increasingly severe climate hazards.

Europe Faces a Tougher Fight to Protect Its Carbon Sinks

The 27 MtCO2 estimated from European wildfires in 2026 adds another layer to the region’s climate challenge. The immediate issue is the carbon released by fires. The longer-term concern is the loss of forests and other ecosystems that would otherwise remove CO2 from the atmosphere.

Europe’s land carbon sink remains an important tool for reaching climate neutrality, but the EEA says its capacity is already declining. For carbon markets, that means the focus must extend beyond how many credits a forest project can generate. The durability of those removals matters just as much.

More resilient forests, stronger fire prevention and better land management can help protect Europe’s carbon sinks. Yet, the latest research shows that these measures will have to work alongside major cuts in greenhouse gas emissions.

As extreme heat and drought increase fire risk, Europe faces a difficult cycle: climate change can make wildfires more severe, fires can release more stored carbon, and damaged forests can become weaker carbon sinks. Breaking that cycle will be critical to both the region’s climate targets and the future reliability of nature-based carbon removal.

The post Europe’s Wildfires Release 27 Million MT of CO2 as France Sets New Emissions Record appeared first on Carbon Credits.

UNEP Warns Global Warming May Overshoot 1.5°C, Calls for Faster Emissions Cuts and Carbon Removal

The world is on track to cross the critical 1.5°C warming threshold within the next few years. A new United Nations Environment Programme (UNEP) report says the threshold is increasingly difficult to avoid, but it does not mean the climate fight is over.

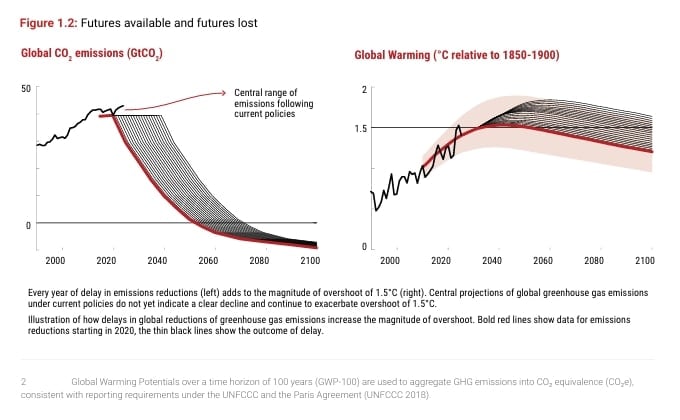
UNEP’s Limiting Overshoot report outlines a difficult but still possible path: allow temperatures to rise above 1.5°C for a limited period, push warming to its lowest possible peak, and then bring global temperatures back down.

The strategy depends on much faster emissions cuts, stronger climate adaptation and a major expansion of carbon dioxide removal (CDR). It also highlights a growing reality for governments and businesses: reaching net-zero emissions may no longer be the final destination. The world may eventually need to move into net-negative emissions to reverse some of the warming.

1.5°C Is Becoming a Temporary Threshold

The Paris Agreement established 1.5°C as a key long-term limit for global warming compared with pre-industrial levels. UNEP press release revealed that current climate action, however, is not moving quickly enough to keep warming below it indefinitely.

So even if governments fully implement existing national climate plans and meet additional net-zero commitments, the most optimistic scenario considered by UNEP still sees warming peak at around 1.8°C.

In this context, UN Secretary-General Antőnio Guterres said,

“This summer’s scorching heat, raging wildfires and deadly floods are a warning of what lies ahead. We must make the overshoot above 1.5 degrees as small and short as possible. That demands an overshoot of ambition.”

Other pathways result in even higher temperatures.

The difference between 1.5°C and 1.8°C may look small on paper, but the climate consequences can be significant. Every additional fraction of a degree increases pressure on ecosystems, food systems, water supplies, infrastructure and human health.

For vulnerable countries and communities, the consequences could be especially severe.

Small island nations and low-lying coastal cities face growing risks from rising seas. Extreme heat and flooding could become more disruptive, while changing ocean conditions would place additional pressure on marine ecosystems and the communities that depend on them.

UNEP carbon emissions
Source: UNEP

The Longer Temperatures Stay High, the Greater the Risk

The problem is not only how high temperatures rise. How long they remain elevated also matters.

Higher and prolonged warming increases the risk of major climate systems reaching tipping points. UNEP highlights threats involving the Greenland and West Antarctic ice sheets, the Amazon rainforest and the Atlantic Meridional Overturning Circulation, or AMOC.

Some climate changes could build gradually. Others could happen much faster than expected.

The effects would also spread through economies. Rising temperatures can increase energy demand, damage infrastructure, raise insurance costs and put additional pressure on financial systems.

Food and water security are another major concern. Without effective adaptation, global food production could decline by as much as 14% by 2050, according to the report.

These risks make limiting the peak temperature increasingly important, even if the 1.5°C target is temporarily exceeded.

Global warming
Source: UNEP

Additionally, Inger Andersen, Executive Director of UNEP, said:

“There are no good outcomes if we remain above 1.5°C. Across the globe, extreme heatwaves are already proving that climate impacts will strike faster, hit harder, and last longer – costing more lives and causing deeper disruption. Now is the time we must double down on climate action. We can – and must – get on the right path. By cutting greenhouse gas emissions, strengthening resilience and adaptation, and ensuring exceedance of 1.5°C is as small and short as possible.”

The World’s Best Remaining Option: Overshoot, Peak and Decline

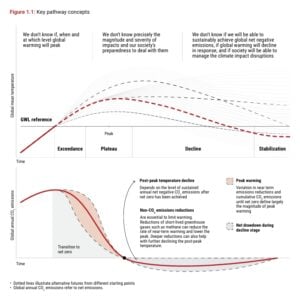
UNEP describes an “overshoot, peak and decline” pathway as the best remaining option for reducing the damage from a temporary breach of 1.5°C.

The approach has three broad stages.

  1. First, countries need to slow warming as quickly as possible. Deep cuts in greenhouse gas emissions, particularly methane and other short-lived climate pollutants, would slow the rate of temperature rise.
  2. Next comes the peak. During this period, economies would need to continue cutting emissions and reach at least net-zero while adapting to increasingly severe climate impacts.
  3. The final stage involves bringing temperatures down through sustained net-negative carbon dioxide emissions. This is where carbon removal becomes critical.
Carbon removal
Sourced from UNEP Report

Carbon Removal Moves From Backup Plan to Climate Tool

Carbon dioxide removal involves taking CO₂ out of the atmosphere and storing it for the long term. Approaches can include restoring forests and other nature-based systems, alongside engineered carbon removal technologies.

UNEP makes an important distinction: carbon removal cannot replace emissions reductions.

Companies and governments cannot continue emitting at current levels and rely on CDR to solve the problem later. Emissions must fall sharply first, with carbon removal addressing residual emissions and eventually helping the world move toward net-negative emissions.

The report also stresses the importance of keeping peak warming well below 2°C. Carbon removal can contribute to a return below 1.5°C only if remaining emissions are brought down substantially, and removal is deployed responsibly.

Strong governance will therefore become increasingly important. Carbon removal projects need credible measurement, environmental safeguards and rules that address questions of scale, fairness and long-term storage.

Adaptation Will Be Just as Important

Even a successful return below 1.5°C would not erase the damage caused during the period of higher temperatures.

Some communities could face permanent changes to their environments, livelihoods and economies. In certain locations, relocation may become necessary.

Adaptation must therefore progress alongside emissions reductions and carbon removal.

The most effective strategies can deliver both benefits at the same time. Nature-based cooling, for example, can help reduce heat exposure while supporting ecosystems and improving resilience.

Adaptation will also need to become more flexible. Climate risks can change rapidly, and infrastructure designed for past conditions may not be suitable for a warmer world.

Three Phases of the Climate Response

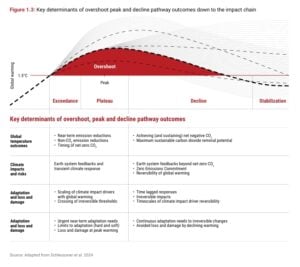
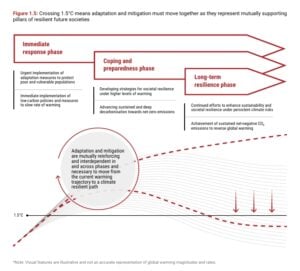
UNEP divides the response into three interconnected phases.

Immediate action focuses on slowing warming through rapid emissions reductions, especially methane cuts, while protecting vulnerable communities and ecosystems.

Coping and containment begins as temperatures approach their peak. Governments and businesses would need to accelerate decarbonization, reach at least net-zero, and strengthen resilience against increasingly severe impacts.

Long-term resilience comes as temperatures begin to decline. Sustained net-negative CO₂ emissions would be needed alongside long-term adaptation and stronger climate resilience.

The timeline for moving through these stages will depend heavily on how quickly governments act.

emission mitigation
Source: UNEP

Climate Action Is Now a Race Against the Peak

Crossing 1.5°C should not be treated as a new acceptable climate target. The central challenge is to make any overshoot as small and short as possible.

Every fraction of a degree avoided can reduce damage. Every year spent at higher temperatures can increase the risk of irreversible changes.

Reaching the best possible outcome will require more than carbon removal. Governments need stronger climate policies, faster renewable energy deployment, deeper emissions cuts, methane reductions and major investment in adaptation.

Finance and international cooperation will also be essential. Countries with greater historical responsibility for emissions face greater pressure to move faster and provide support to more vulnerable nations.

The climate challenge has therefore entered a new phase. Net-zero remains essential, but it may be only the midpoint. The longer-term goal could require removing more carbon from the atmosphere than humanity emits.

The window for keeping that pathway open is narrowing. The decisions made now will determine not only whether temperatures cross 1.5°C, but also how high they climb, how long they stay there, and whether the world can eventually bring them back down.

The post UNEP Warns Global Warming May Overshoot 1.5°C, Calls for Faster Emissions Cuts and Carbon Removal appeared first on Carbon Credits.

World Bank, Brazilian Bank Plan $100M Carbon Fund to Finance Brazil Projects

World Bank, Brazilian Bank Plan $100M Carbon Fund to Finance Brazil Projects

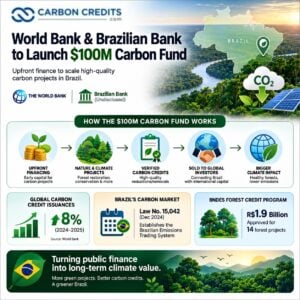
The World Bank and a Brazilian bank are structuring a carbon fund with an initial target of $100 million to provide upfront financing for carbon projects in Brazil. The resulting carbon credits would then be sold to international investors. 

The identity of the Brazilian bank and the final structure of the fund have not been disclosed. It is also not yet clear how many projects the fund could finance or how many carbon credits they could generate.

Still, the proposed vehicle points to a growing effort to connect international capital with Brazil’s large pipeline of nature and carbon projects. While the World Bank’s partner remains confidential, market speculation points to major institutions like BNDES or Banco da Amazônia (BASA) due to their strong history with green capital. However, these names are strictly market context, not confirmed facts yet.

Upfront Funding Could Fill Brazil’s Carbon Finance Gap

Carbon projects often face a financing problem at the start. Developers may need years of investment before projects generate verified carbon credits that can be sold.

An upfront financing fund could help bridge that gap. Developers can get funding sooner instead of waiting for future credit sales. They can use this money for activities like forest restoration, conservation, or other projects that reduce emissions.

The model could also give international investors greater access to Brazilian carbon projects. The proposed $100 million fund is still being set up. So, its investment terms and risk-sharing details are not yet clear.

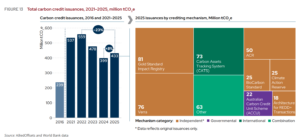
The announcement comes as demand for carbon projects is shifting toward assets with stronger environmental and social value. The World Bank said in its State and Trends of Carbon Pricing 2026 report that global carbon credit issuances rose 8% from 2024 to 2025.

Total carbon credit issuances

At the same time, credit prices fell slightly overall, while some higher-value categories continued to receive premiums. These included credits eligible for international aviation and highly rated forest conservation and reforestation projects.

World Bank Has Already Tested Carbon Finance in Brazil

The new fund would build on earlier World Bank efforts to connect Brazilian climate projects with private finance.

In 2022, the World Bank approved a $500 million project with Banco do Brasil. This project aims to boost sustainability-linked lending and help Brazilian companies access carbon markets. The project aims to reduce emissions by up to 90 million tonnes of CO2e by 2030. It also seeks to attract $1.4 billion in private capital.

That project is separate from the new $100 million fund. The latest report only identifies the current partner as a Brazilian bank.

The World Bank also used a different financing structure for Amazon restoration in 2024. It issued a $225 million, nine-year Amazon Reforestation-Linked Outcome Bond. Returns for investors depend partly on carbon removal units from reforestation projects. Mombak raised about $36 million to boost its reforestation efforts in Brazil.

These transactions illustrate how carbon and climate results can be included in everyday financial products. This approach goes beyond just direct project investments.

Brazil Is Building a Larger Carbon Market

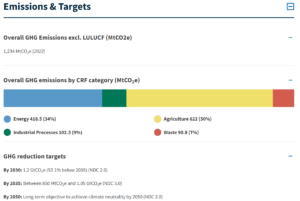
Brazil is also creating a stronger domestic framework for carbon markets. The country established the Brazilian Emissions Trading System, or SBCE, through Law No. 15,042, enacted on December 11, 2024. The law created a regulated carbon market and set rules for emissions trading, carbon credits, and related infrastructure.

brazil ghg emissions trading system
Source: ICAP

Implementation is now moving forward. In July 2026, Brazil’s Ministry of Finance began public consultations. They focused on which sectors would be included in emissions monitoring, reporting, and verification (MRV). The consultation also addressed a proposed timetable for implementing the system.

The government said the MRV framework will help create an official and reliable emissions database. That information will later help support:

  • decisions on the emissions cap,
  • allocation of Brazilian Emissions Allowances, and
  • the limits for using verified reduction or removal certificates to meet compliance obligations.

The developing regulated market could eventually create another source of demand for eligible emissions reductions.

Nature and Forestry Could Be Major Opportunities

Brazil’s forests offer a large potential project base, particularly for restoration and carbon removal. Public financing is already helping scale this sector.

The BNDES Forest Credit program has approved R$1.9 billion for 14 projects. These projects focus on ecological restoration, productive restoration, native-species forestry, and forest management. BNDES says the program has attracted R$1.59 in private resources for every R$1 invested by the bank.

The bank has also supported projects focused directly on carbon removal. In 2025, BNDES approved R$100 million for Mombak to reforest degraded areas in the Amazon while supporting biodiversity recovery and carbon capture.

These projects illustrate why Brazil could be an important market for carbon finance. The country has vast degraded lands and important forest ecosystems. It is also developing a growing policy framework for carbon markets.

Global Investors Are Looking for Better Credits

The proposed fund also comes as the carbon market becomes more selective. The World Bank reported that carbon credit issuances increased in 2025, but overall prices declined slightly. Credits linked to international aviation and highly rated forest conservation and reforestation projects still attracted premiums.

Investors are now focusing more on the quality, use case, and project type of carbon credits. They’re not seeing all credits as the same anymore.

For a Brazilian fund targeting international buyers, project quality, measurement, and verification will, therefore, be critical. Strong monitoring and clear ownership of the resulting credits would also matter for investors assessing future revenue.

Right now, there’s no public information on whether the proposed $100 million fund will target voluntary carbon markets, Brazil’s future regulated system, international Article 6 transactions, or a mix of these markets.world bank brazilian bank $00M carbon fund

Article 6 Eligibility Is Not Yet Confirmed

Brazil is building its international carbon market. However, it’s too soon to say that projects funded by the new fund will qualify for international transfers under Article 6 of the Paris Agreement.

Article 6.2 allows countries to transfer internationally traded mitigation outcomes, known as ITMOs, under cooperative approaches. A corresponding adjustment stops the same emissions reduction from being counted by both the selling and buying countries.

Whether a project can use this framework depends on national authorization and other eligibility requirements. The latest report on the $100 million fund does not disclose whether its credits will receive such authorization.

For now, the fund should therefore be viewed as a proposed financing mechanism rather than a confirmed source of Article 6 credits.

The Bigger Goal: Turn Public Finance Into Private Capital

The most important feature of the proposed vehicle may be its focus on upfront finance. Brazil has already shown that public and development-bank capital can help bring private money into climate projects.

A new international-investor fund could extend that approach specifically to carbon projects. The opportunity is significant, but the details will determine its impact. Investors will need clarity on project selection, expected returns, credit ownership, verification, market eligibility, and risks before committing capital.

For Brazil, the timing is important. Its regulated carbon market is taking shape, private investment in forest projects is growing, and international demand is increasingly focused on higher-quality credits.

The proposed $100 million fund could help connect those trends. But until the World Bank and its Brazilian partner disclose more details, the size of the opportunity remains an early-stage estimate rather than a confirmed pipeline.

The post World Bank, Brazilian Bank Plan $100M Carbon Fund to Finance Brazil Projects appeared first on Carbon Credits.

Microsoft Uses NORDEN’s Book & Claim Pilot to Tackle Scope 3 Emissions

A new maritime decarbonization pilot is showing how companies could reduce supply chain emissions without waiting for low-carbon fuels to become available on every shipping route.

Danish shipping company NORDEN has delivered the first verified maritime emissions reductions through the Roundtable on Sustainable Biomaterials (RSB) Book & Claim registry. The pilot, completed with Microsoft and RSB, marks the first time a maritime carrier has issued and delivered verified emissions reductions through the RSB system.

The development could give companies a more practical way to tackle shipping-related Scope 3 emissions, particularly when sustainable fuels remain limited in availability.

Anne Jensen, COO at NORDEN, commented:

“For many companies, some of the most difficult emissions to address are those embedded deep within global supply chains, where they often have little visibility or direct influence over how goods are transported.

This transaction demonstrates how Book & Claim can help bridge that gap. By enabling companies to invest in verified emissions reductions from maritime transport, regardless of where the fuel is used or where they sit in the value chain, we can help accelerate decarbonisation across industries.”

Shipping Remains a Major Emissions Challenge

The maritime sector carries most of the world’s international trade, but it also produces a significant carbon footprint.

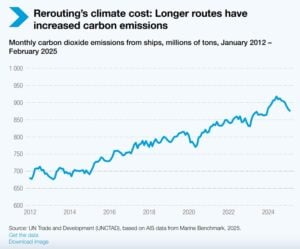
The latest figures cited by the United Nations Conference on Trade and Development (UNCTAD) show that shipping greenhouse gas emissions increased by 5% in 2024. Longer voyages, including those caused by geopolitical disruptions and rerouting, contributed to the increase. At the same time, only about 8% of the world’s fleet by tonnage was equipped to use alternative fuels.

shipping emissions

  • The International Maritime Organization (IMO) estimates that global shipping produced 1.056 billion tonnes of CO2 in 2018, about 2.89% of global anthropogenic CO2 emissions at the time.

The sector therefore faces a difficult transition. Ships have long operating lives, alternative fuels are still developing, and supply is not evenly distributed across global ports.

That creates a problem for companies trying to reduce emissions linked to their transported goods.

A business may want to use a lower-emission fuel for its cargo, but the required fuel may not be available at the port where its particular vessel operates.

NORDEN’s Book & Claim model is designed to address that gap.

How NORDEN’s Maritime Book & Claim Model Works

Under a Book & Claim system, the physical movement of a low-emission fuel does not have to match the customer’s specific cargo movement.

Instead, NORDEN can use lower-emission fuel where it makes the most operational sense within its fleet. The resulting emissions reductions are then documented and allocated to a customer.

This separates the physical use of the fuel from the customer’s shipping activity.

For companies, that means they do not necessarily have to change their logistics routes or wait for sustainable fuel to become available at every port.

Scaling Biofuel Through Book & Claim

NORDEN says its biofuel solutions can be used either as blends or as B100, with emissions reductions of up to 80%–90%, depending on the fuel and application. The company also says customers can select the level of emissions reduction based on their ambitions and budget.

The important distinction is that the model is built around documented and verified emissions reductions rather than simply purchasing a conventional carbon offset.

NORDEN first had to obtain RSB Book & Claim trader certification before it could issue and sell verified reductions through the registry. RSB developed the certification by adapting its existing Book & Claim framework, previously used in aviation, for maritime transport and carriers.

Why Microsoft Is Testing the Model

Microsoft is the first company globally to use the RSB registry’s Book & Claim system for shipping emissions. The move fits into a much larger challenge for the technology giant: reducing emissions across its value chain.

Microsoft’s latest sustainability report highlights the growing emissions challenge from its expanding AI and data center infrastructure.

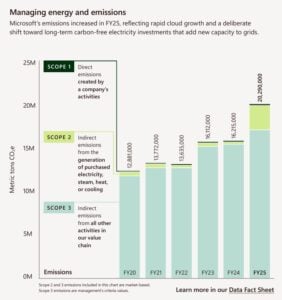
In FY2025, Microsoft reported 20.29 million metric tons of CO₂e across Scopes 1, 2 and 3. That was 25% higher than the 16.21 million metric tons reported a year earlier. Microsoft linked the increase mainly to data center growth and changes in its use of renewable energy certificates.

  • Scope 3 remained the largest source, accounting for 85.82% of total emissions, down from 97.29% in FY2024. Scope 2 made up 13.34%, while Scope 1 accounted for 0.84%.
  • Precisely, Scope 3 emissions were 17.41 million metric tons. Capital goods made up the largest share at 44.57%, followed by purchased goods and services at 25.28%. Together, they accounted for nearly 70% of Scope 3 emissions. Transportation also contributed to the footprint. Upstream transportation and distribution accounted for 3.66% of Scope 3 emissions, while downstream transportation and distribution made up 0.42%.

Turns to Shipping to Cut Scope 3 Emissions

These figures show why cleaner shipping can play a role in Microsoft’s climate strategy. Maritime transport is only a small part of its overall Scope 3 footprint, but it gives the company a direct way to reduce emissions linked to its global supply chain.

More importantly, its Scope 3 emissions remained a growing problem as they were 26% higher in FY2024 than its 2020 baseline. This makes maritime freight an important area for intervention.

microsoft scope 3 emissions
Source: Microsoft

Microsoft has already been working with suppliers and other partners to address emissions embedded in its wider supply chain. In 2024, the company contracted 19 GW of new renewable energy across 16 countries and continued investing in technologies and partnerships designed to tackle hard-to-abate Scope 3 emissions.

The NORDEN pilot adds another tool to that strategy.

Bella Horstmann, Senior Manager, Market Development, Microsoft, said:

“Decarbonising supply chains requires solutions that are both credible and scalable. This collaboration with NORDEN and RSB shows how Book & Claim can help accelerate progress in sectors where change is otherwise complex and demonstrates that companies don’t need to wait to start reducing their shipping emissions in a verified and meaningful way.” 

The Pilot Could Help Scale Maritime Decarbonization

NORDEN and Microsoft had already announced their collaboration in 2025. At the time, the companies said the pilot could reduce Microsoft’s maritime Scope 3 emissions by nearly 10,000 tonnes of CO2e over three years.

The latest transaction takes that collaboration a step further by putting the reductions through the RSB registry.

That verification component could prove critical as more companies look for credible ways to account for supply chain emissions.

Book & Claim does not eliminate the need to increase the physical supply of sustainable marine fuels. Instead, it can create demand while the industry works through fuel availability, infrastructure, and cost challenges.

RSB now plans to update its Book and Claim Chain of Custody procedure to support broader adoption across maritime transport. NORDEN also plans to work with customers and partners to expand the model.

The timing is significant. Shipping emissions are rising again, while the availability of alternative-fuel-capable vessels remains limited.

For companies such as Microsoft, the challenge is therefore not simply finding cleaner ships. It is finding a system that can connect real emissions reductions with complex global supply chains.

NORDEN’s pilot suggests Book & Claim could become one part of that solution.

However, strong verification and transparent accounting remain essential. If the model scales, companies can use it to cut maritime Scope 3 emissions today. Meanwhile, the shipping industry can continue building the cleaner fuel infrastructure needed for the long term.

The post Microsoft Uses NORDEN’s Book & Claim Pilot to Tackle Scope 3 Emissions appeared first on Carbon Credits.

CATL’s Jianxiawo Mine Loses EIA Approval: Will China’s Lithium Supply Take a Hit?

CATL’s Jianxiawo lithium mine has suffered another major setback, with Chinese regulators revoking its environmental impact assessment (EIA) approval and forcing the operation back into care and maintenance.

The development is important for the global lithium market because Jianxiawo is China’s largest lithium mine by planned capacity. Its prolonged shutdown comes at a time when lithium inventories have been falling, and prices have recovered sharply from their 2025 lows.

Benchmark Mineral Intelligence originally reported on September 1 that the mine’s EIA had been revoked. The licence setback subsequently highlighted the potential impact on China’s lithium supply.

Jianxiawo Faces Another Delay

The Jianxiawo mine is located in Yichun, Jiangxi province, a major lithium-producing region in China. The operation extracts lithium-bearing lepidolite, a lower-grade ore that has become increasingly important to China’s domestic battery-material supply chain.

The mine had already been offline since August 2025 after its mining permit expired. That shutdown followed tighter regulatory scrutiny of lithium operations in Jiangxi and changes affecting the classification and permitting of lithium resources.

Progress toward a restart appeared to accelerate in June 2026. CATL secured a safety production permit on June 29, removing what Benchmark had described as the final major official hurdle to restarting the mine.

That optimism did not last.

The operation briefly restarted in July but was subsequently placed back into care and maintenance. The latest problem is environmental approval. With the EIA revoked, Jianxiawo now needs to go through another environmental review before a meaningful restart can take place. Benchmark estimates the process could extend into the fourth quarter of 2026 or even 2027.

The issue also appears connected to concerns surrounding the mine’s tailings facilities and environmental management, making the approval process more significant than a simple administrative delay.

CATL’s Expected Lithium Output Has Been Cut

The biggest immediate consequence is the reduction in expected production.

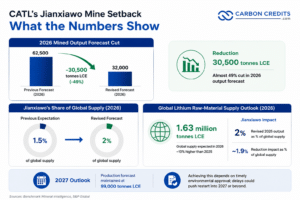
  • Benchmark has cut its forecast for Jianxiawo’s 2026 mined output to 32,000 tonnes of lithium carbonate equivalent (LCE) from 62,500 tonnes LCE previously.

That is a reduction of 30,500 tonnes LCE, or almost 49%.

The revised figure is particularly significant because Jianxiawo was expected to become a major source of additional Chinese lithium supply following its restart. Benchmark had previously expected the mine to contribute roughly 1.5% of global mined lithium supply in 2026.

For perspective, S&P Global expects global lithium raw-material supply to reach about 1.63 million tonnes LCE in 2026, up roughly 10% from 2025. On that basis, Jianxiawo’s revised 32,000 tonnes would represent around 2% of global annual supply, while the 30,500-tonne reduction represents almost 1.9% of the global supply estimate.

The impact is therefore meaningful, even though the mine alone is not large enough to determine the global market balance.

Benchmark has kept its 2027 production forecast for Jianxiawo at approximately 99,000 tonnes LCE, suggesting that the current disruption does not necessarily mean the resource will remain offline permanently. However, that forecast becomes more difficult to achieve if environmental approval slips into next year.

CATL LITHIUM

What Does It Mean for Lithium Prices?

The timing is particularly important.

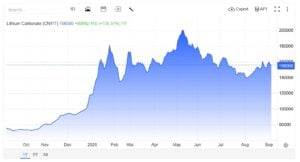
Lithium prices have already staged a major recovery in 2026. A market benchmark tracked by Trading Economics stood at around 156,000 yuan ($22,000) per tonne on September 3, up more than 105% from a year earlier. The price has also risen about 11% over the past month, showing how quickly sentiment has changed.

lithium prices
Source: Trading Economics

The Jianxiawo setback could add another bullish factor.

China’s battery-grade lithium carbonate and lithium hydroxide inventories have been declining since September 2025, according to Benchmark. Lower inventories make the market more sensitive to unexpected production losses because buyers have less material available to absorb supply disruptions.

That does not mean lithium prices will automatically surge.

Global supply is still expanding. S&P Global’s forecast is positive, and the market had previously been characterized by ample supply. New production from other mines can also partly offset Jianxiawo’s shortfall.

The more important question is therefore whether the mine remains offline for months or slips into 2027.

A Bigger Problem for China’s Lithium Supply

Jianxiawo matters beyond its individual production numbers because it highlights the growing regulatory risk surrounding China’s domestic lithium industry.

China dominates lithium refining and battery manufacturing, but some of its domestic ore resources are relatively challenging to process. Lepidolite operations in Jiangxi are particularly important because they provide feedstock for China’s enormous conversion industry.

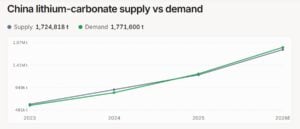
  • SDIC Securities’ August 12, 2026 forecast puts China’s lithium carbonate supply at 1.725 million tonnes in 2026, compared with 1.208 million tonnes in 2025.

If environmental and permitting requirements continue to delay projects, domestic supply growth could become slower than expected.

That could force Chinese refiners and battery manufacturers to source more material from overseas producers. CATL has already been reported to seek alternative feedstock following previous disruptions at Jianxiawo.

The result could be higher competition for imported spodumene and lithium chemicals, potentially supporting prices outside China as well.

china lithium
Source: SIDC

Lithium Market Could Become More Sensitive to Supply Shocks

The Jianxiawo setback does not create an immediate global lithium shortage. The revised 2026 production loss is relatively small compared with total global supply.

But markets rarely price commodities based only on current production.

Expectations matter.

  • A restart at Jianxiawo was expected to bring a significant amount of additional supply into the market. Removing almost 30,500 tonnes LCE from that expectation changes the outlook, particularly when inventories are already tighter and battery demand remains strong.

Energy storage is also becoming an increasingly important source of lithium demand alongside electric vehicles. Strong battery demand means supply disruptions can have a larger effect on prices when producers and converters have limited inventories.

For now, the most likely impact is upward pressure rather than a full-blown lithium price shock. If Jianxiawo receives environmental approval and resumes production before the end of 2026, the market could absorb much of the lost output. If the review extends into 2027, however, traders may begin pricing in a more persistent supply constraint.

The bigger message is clear: Jianxiawo’s lithium is not lost, but its return to the market is no longer guaranteed on the timeline investors expected. With lithium prices already recovering and inventories tighter, another delay at one of China’s largest planned lithium mines could keep the market firmly focused on supply risk.

The post CATL’s Jianxiawo Mine Loses EIA Approval: Will China’s Lithium Supply Take a Hit? appeared first on Carbon Credits.
Verra Wins ICVCM Approval for VCS Version 5 as Carbon Market Integrity Tightens

Verra Wins ICVCM Approval for VCS Version 5 as Carbon Market Integrity Tightens

Verra has gained key backing for its Verified Carbon Standard (VCS) Version 5. The Integrity Council for the Voluntary Carbon Market (ICVCM) recognized VCS Version 5 as CCP-Eligible on September 2, 2026. The decision shows that the latest version of Verra’s program meets the ICVCM’s Core Carbon Principles (CCPs). These principles set a global standard for trustworthy carbon markets.

The decision is important. Verra runs the world’s largest voluntary carbon credit program. It has issued about 1.3 billion Verified Carbon Units (VCUs) across 2,579 VCS projects in 132 countries. This comes as the voluntary carbon market shifts to stricter rules on credit quality, transparency, and community protections.

However, the approval does not mean every VCS credit can now carry the CCP label. The ICVCM uses a two-step process. First, it assesses the crediting program. It then assesses the specific methodologies and credit categories used to generate credits.

Verra Raises the Bar for Carbon Credit Quality

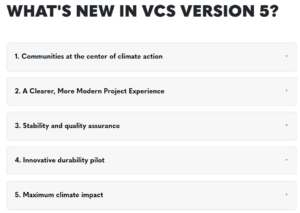
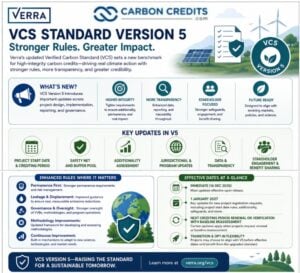
Verra launched VCS Version 5 in December 2025 as a major update to its carbon crediting rules. The new version aims to improve program integrity, usability, and climate impact. It also strengthens social and environmental safeguards and places more focus on the rights and role of local communities.

Verra developed the new version through three public consultations, which generated nearly 5,000 comments from around 200 respondents. The company says this was the highest response rate for a VCS program consultation.

  • The updated rules cover the entire project lifecycle. They include project design, validation, monitoring, verification, and credit issuance.

Verra states that projects must create carbon credits that are additional, properly measured, durable, independently verified, traceable, and not double-counted. These requirements address some of the main concerns that have affected confidence in voluntary carbon markets.

Verra VCS Version 5 updates
Source: Verra

Community Safeguards Take a Bigger Role

One of the biggest changes in Version 5 is its focus on people living in and around carbon projects. Verra says the new rules strengthen protections for Indigenous Peoples and local communities. Projects must improve stakeholder engagement, assess social and environmental risks, and put safeguards in place.

The standard also calls for clearer financial transparency and fair benefit-sharing arrangements before projects begin. This is important because many carbon projects involve forests, farmland, or other land used by local communities.

A project may deliver a measurable climate benefit but still face serious concerns if it does not respect land rights or share benefits fairly. By putting these safeguards directly into the program rules, Verra is trying to make social performance a core part of credit quality rather than a separate add-on.

ICVCM Approval Comes With an Important Catch

The distinction between CCP-Eligible and CCP-Approved is critical.

The ICVCM first checks if a crediting program has good governance, transparency, tracking, third-party verification, and clear rules for measuring emissions reductions and removals. After that, it assesses the methodologies used to create different types of credits.

Only credits from a CCP-Eligible program and a CCP-Approved methodology may bear the CCP label. This means VCS Version 5’s new status strengthens the program, but buyers still need to check the methodology behind a specific credit.

That two-step system is designed to avoid assigning a single broad quality label to credits that use very different methods.

ICVCM Approves 13 Verra Methodologies

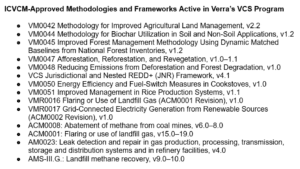
Alongside VCS Version 5, the ICVCM has approved 13 methodologies and one VCS Jurisdictional and Nested REDD+ Framework that are active in Verra’s program. The approved methodologies cover several project types, including:

  • Afforestation, reforestation and revegetation, biochar, improved forest management, REDD+, cookstoves, rice production, landfill gas, renewable electricity and coal-mine methane.

The approved methodologies are the following:

Verra ICVCM-Approved Methodologies

As of August 12, 2026, the ICVCM’s broader assessment program had approved 44 methodologies in total, per its assessment-status page. That means Verra’s approved methodologies now form a meaningful part of the CCP-approved market.

Version 5 Is Not Fully Mandatory Yet

Another important detail is timing. Verra launched VCS Version 5 in December 2025, but many of its project-level requirements do not become mandatory until January 1, 2027.

Verra fully operationalized Version 5 in June 2026 by publishing the updated templates and guidance needed for project developers. This allows projects to begin using the new system.

  • Existing projects have transition paths, while new projects registering after January 1, 2027 generally must use Version 5 requirements.
  • All existing projects must transition to Version 5 safeguard requirements after January 1, 2030. Some projects have a longer transition period.

This staged approach gives developers time to adapt while gradually moving the whole program toward the new rules.

Carbon Reversal Risk Gets a New Option

Version 5 also introduces a pilot for managing non-permanence risk. Land-based carbon projects can face the risk that stored carbon is released later through events such as fires, drought, or land-use changes.

Verra’s traditional system uses a pooled buffer approach to manage some of this risk. Version 5 allows a pilot using insurance or fund-based approaches as alternatives.

The goal is to give project developers more ways to protect against carbon reversals. Verra says this could help unlock more financing for projects that use these approaches.

The move is especially relevant for nature-based projects, where long-term storage remains one of the biggest concerns for carbon buyers.

Verra VCS standard version 5

Can Tougher Rules Restore Confidence in the VCM?

The ICVCM’s endorsement comes at a critical time for voluntary carbon markets. Buyers increasingly want proof that credits provide real climate benefits. They also want clearer information about project risks, community impacts, and how credits are measured.

The ICVCM created the CCP framework partly to address those concerns. It says the CCP label should make it easier for buyers to identify and price high-integrity credits across different standards and project types. That could help reduce confusion in a market where credits can vary widely in quality and price.

For Verra, the decision also provides external recognition of the changes it has made to its flagship standard. However, the approval does not eliminate the need for project-level scrutiny.

A CCP-eligible program includes many projects. Individual credits rely on the methodology, project design, monitoring, and verification used.

What It Means for Carbon Credit Buyers

For buyers, the new VCS status could make some Verra credits easier to evaluate. However, they still need to check whether the specific methodology and credit category have CCP approval. They also need to consider the project’s location, vintage, environmental risks, and social impacts.

This is especially important because Verra has a very large existing project base. Its program has issued about 1.3 billion VCUs, but those credits span many project types and years.

New Version 5 projects will face stricter rules, but existing projects will transition over time. That means the voluntary market will have a mix of credits operating under older and newer requirements for several years.

The market will need clear communication about those differences.

For the wider VCM, the next question is whether these stricter rules translate into more buyer confidence, better project practices, and greater demand for high-integrity credits.

The ICVCM approval is therefore more than a standards update. It is another step toward a carbon market where quality, transparency, and community protections play a larger role in determining which credits attract buyers and climate finance.

The post Verra Wins ICVCM Approval for VCS Version 5 as Carbon Market Integrity Tightens appeared first on Carbon Credits.
Econetix Lands Million-Dollar RWE Deal as CORSIA Carbon Credit Shortage Deepens

Econetix Lands Million-Dollar RWE Deal as CORSIA Carbon Credit Shortage Deepens

Econetix, a carbon project developer, has signed a million-dollar deal with RWE Supply & Trading. This agreement allows the German energy trader access to carbon credits for the international aviation market under CORSIA.

The deal, announced September 1, 2026, will see Vienna-based Econetix supply CORSIA-eligible carbon credits from its certified project portfolio. RWE will then market the credits to airlines and other buyers that need units for compliance.

The deal shows a major challenge for CORSIA: airlines might need many more eligible credits than the market can provide right now.

RWE Builds a New Bridge to Airline Carbon Buyers

Under the partnership, Econetix will provide CORSIA-eligible credits from its portfolio to RWE Supply & Trading. RWE will act as the intermediary. It will use its trading platform and customer network to connect the credits with airlines and other compliance-driven buyers.

The companies did not disclose the exact value or volume of credits covered by the agreement. Econetix described it as a million-dollar forward supply agreement.

A forward deal allows a buyer to secure future credit supply before all of the credits are ready for delivery. That can be useful in CORSIA because projects often need time to secure host-country approval, complete certification, and receive the required labels.

For developers, a committed buyer can also make future projects easier to finance. For RWE, the agreement adds another source of credits for customers preparing for CORSIA’s first compliance deadline.

CORSIA’s Carbon Credit Gap Is Getting Harder to Ignore

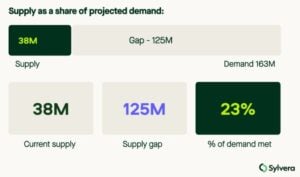
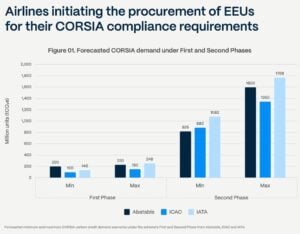
The timing reflects a major supply problem. ICAO’s latest CORSIA Eligible Emissions Unit Supply Project estimates 170 million to 236 million tonnes of demand during the 2024–2026 first phase. It puts eligible supply from 10 countries at about 36-38 million tonnes as of June 2026.

Sylvera data also shows a similar trend for the demand and supply gap for CORSIA credits. 

corsia credit demand and supply gap sylvera

ICAO estimates that the first phase could create a $4 billion to $5 billion climate investment opportunity for developing countries. These countries can provide eligible emissions units.

IATA’s June 2026 market update gives a similar warning. The main scenario shows a first-phase demand of 213 million tonnes. However, there are only 38 million tonnes of eligible units available. This results in a shortfall of about 175 million tonnes.

The small difference between the ICAO and IATA supply figures reflects timing and methodology. But both point to the same conclusion: CORSIA supply remains far below potential demand. That gap is creating stronger interest in forward agreements such as the Econetix-RWE deal.

What Makes a Credit CORSIA Eligible?

Not every carbon credit can enter the CORSIA market. ICAO maintains a specific list of approved emissions-unit programs and sets rules for eligible vintages and other conditions.

For the 2024–2026 first phase, eligible programs include standards such as:

  • American Carbon Registry,
  • Gold Standard,
  • Verra’s Verified Carbon Standard, and
  • Isometric, among others.

Credits also need to meet host-country requirements.

For many credits issued from 2021 onward, ICAO requires evidence linked to host-country authorization and corresponding adjustments. These rules help prevent a country from counting the same emissions reduction toward its own climate target after an airline uses the credit under CORSIA.

That makes CORSIA supply more difficult to build than a normal voluntary carbon project. A project may generate carbon credits, but that does not mean those credits are automatically eligible for aviation compliance.

Article 6 Is Becoming Central to CORSIA

The CORSIA market is also becoming closely linked to Article 6 of the Paris Agreement. Host countries must approve projects and follow accounting rules before credits can be used internationally.

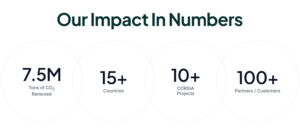
Econetix says its portfolio includes projects with Article 6 Letters of Authorization and corresponding adjustments. Its earlier Rwanda cookstove project, for example, received authorization for up to 1.77 million tonnes of CORSIA supply.

Econetix carbon developer in numbers
Source: Econetix

In August, Econetix also secured a Ugandan authorization covering up to 10 million tonnes of CO2e from its clean cooking program for vintages from 2025 to 2030. The company described that as the largest single Article 6 authorization granted to a private company in Uganda.

These authorizations do not mean all 11.77 million tonnes will immediately become available to airlines. Projects still need to meet the relevant CORSIA and certification requirements.

But they show how host-country approvals can create a pipeline of future eligible supply.

Econetix Builds a Six-Country CORSIA Pipeline

The RWE deal follows several other CORSIA-related transactions for Econetix. The company said it is advancing more than 10 projects across the Democratic Republic of Congo, Uganda, Tanzania, Malawi, Rwanda and Sierra Leone. It has already signed supply deals with SCB Environmental Markets and SmartestEnergy.

Econetix CORSIA article 6 carbon projects
Source: Econetix

In July, Econetix also delivered its first Phase 1-tagged CORSIA credits under an earlier million-dollar agreement with a major international commodity trading house. That delivery is important because it shows a distinction between having a project pipeline and delivering credits that buyers can actually use.

Econetix’s new RWE agreement adds another commercial channel for future supply. For the company, the strategy appears to be moving from individual project development toward a broader CORSIA supply platform.

Airlines Race Toward the 2028 Compliance Deadline

CORSIA’s timing is putting pressure on buyers. The scheme’s first phase runs from 2024 through 2026. Airlines must then cancel the eligible emissions units needed to meet their obligations. ICAO’s timetable sets January 31, 2028 as the deadline for cancellation of units linked to the first compliance period.

That means airlines do not simply need credits eventually. They need qualifying units ready for use ahead of the deadline.

ICAO says 130 states will participate in CORSIA from 2026, increasing to 134 states from 2027, together covering about 85% of international aviation emissions. As participation grows, the need for eligible units could increase. This is one reason airlines, traders and other buyers are securing supply early.

CORSIA compliance requirements abatable

The CORSIA Credit Crunch Could Reward Early Supply

CORSIA is moving toward a larger compliance market. IATA estimates airlines might buy over 200 million credits in the first phase, valued at $4 billion to $5 billion. Demand could reach almost 2 billion credits by 2035.

ICAO estimates a first-phase supply gap of up to 200 million tonnes, while IATA puts the gap at about 175 million tonnes in its central scenario.

That shortage makes forward deals such as the Econetix-RWE agreement more important. The deal gives RWE access to future CORSIA-eligible credits while giving Econetix a route to airline and other compliance buyers.

However, projects still need financing, host-country approval, validation, verification, and CORSIA eligibility before they can deliver credits. With airlines facing a January 2028 deadline to cancel units for the first compliance period, securing reliable future supply is becoming increasingly important.

The post Econetix Lands Million-Dollar RWE Deal as CORSIA Carbon Credit Shortage Deepens appeared first on Carbon Credits.