Kazakhstan Opens 5.2M Hectares for Carbon Projects, Eyes Article 6 Credit Trading

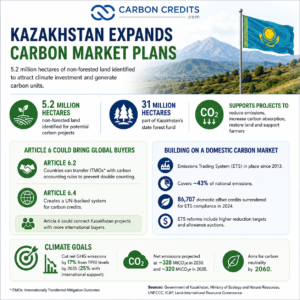
Kazakhstan has identified 5.2 million hectares of non-forested land for possible carbon projects. The move could help the country attract climate investment and create carbon units or credits for domestic and international markets.

The land is part of Kazakhstan’s 31 million-hectare state forest fund, according to Ecology and Natural Resources Minister Yerlan Nyssanbayev. The government says the land could support projects that cut emissions or increase carbon absorption.

Kazakhstan is also updating its carbon market rules and preparing to use Article 6 of the Paris Agreement for international carbon trading. The country aims to reach carbon neutrality by 2060. Its latest climate plan targets a 17% cut in net greenhouse gas emissions from 1990 levels by 2035, with a deeper 25% cut if it receives international support.

5.2 Million Hectares Could Support Carbon Projects

The 5.2 million hectares offer a large area for new carbon projects. However, Kazakhstan has not said that all of the land will produce carbon credits.

Minister Nyssanbayev said the land could support projects that reduce emissions and absorb carbon. The Asian nation sees opportunities in areas such as forestry, agriculture and energy efficiency. The government also wants carbon projects to help restore damaged land and expand green areas. Farmers could also gain new ways to take part in carbon markets.

However, the size of the land area does not tell us how many carbon units it could produce. Actual credit volumes will depend on the projects developed, the methods they use, and the results they can measure and verify.

New Rules Open a Path to Global Carbon Markets

Kazakhstan is also changing the rules for its carbon market. New rules on greenhouse gas emissions and carbon absorption took effect on August 10, 2026. They set procedures for climate projects under Article 6 of the Paris Agreement.

The rules cover validation, verification, monitoring, authorization, and baseline setting. They also set procedures for transferring verified emissions reductions or carbon removals to other countries.

This gives project developers a clearer process for moving from project design to carbon unit issuance and, potentially, international sales. But project approval does not automatically allow developers to sell all units abroad.

Projects must meet the required rules, monitor their results, and complete verification. International transfers also need government approval.

Article 6 Could Bring International Buyers

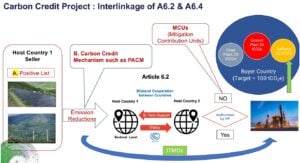
Article 6 gives countries a way to work together on emissions reductions. Under Article 6.2, countries can transfer internationally transferred mitigation outcomes, or ITMOs. The system includes carbon accounting and reporting rules to prevent double counting.

Carbon Credit generation article 6
Source: UNFCCC

Article 6.4 creates a separate UN-backed system for carbon credits.

Kazakhstan’s latest climate plan also points to Article 6 as a way to attract international climate finance. The plan says Kazakhstan’s legal system allows the issuance and transfer of ITMOs, the use of corresponding adjustments, and future links between its national carbon market and wider regional or global markets.

For project developers, this could create access to more international buyers.

For buyers, however, project quality will remain critical. Projects must show that their emissions reductions or carbon removals are real and measurable. They must also meet the accounting rules under Article 6.

Kazakhstan Already Has a Domestic Carbon Market

Kazakhstan is not starting from zero. The country has operated an Emissions Trading System (ETS) since 2013. The system covers major facilities in sectors such as power, oil and gas, mining, metals, chemicals and manufacturing. Facilities that emit more than 20,000 tonnes of CO2 a year fall under the main ETS threshold.

Kazakhstan’s Ministry of Ecology and Natural Resources says the ETS covers about 43% of the country’s national emissions.

The country also allows carbon projects outside the ETS to generate domestic carbon credits. Companies covered by the ETS can use these credits to help meet their obligations.

In 2024, 86,707 domestic offset credits were surrendered for ETS compliance, according to the International Carbon Action Partnership. The new plan aims to build on this existing market and give carbon projects a path to international buyers.

Kazakhstan 5.2 million hectares carbon project

ETS Changes Could Strengthen the Market

Kazakhstan is also working to make its ETS stronger. The government has discussed raising the annual emissions reduction rate to at least 2.73% during 2026–2030. That compares with 2.25% in 2024 and 2.26% in 2025.

The International Carbon Action Partnership says Kazakhstan’s draft national allocation plan for 2026–2030 proposed annual cap cuts of 10.4% to 23% from the 2025 level. The government is also developing an auction system for emissions allowances.

The Asian country received more support for these efforts in 2025. The World Bank’s Partnership for Market Implementation provided the country with a $4.8 million grant to strengthen its ETS, study allowance auctions, and prepare for international carbon markets under Article 6.

The project runs through June 30, 2028. These changes could help Kazakhstan build a stronger domestic carbon market while preparing for international trading.

Climate Goals Add Pressure for Investment

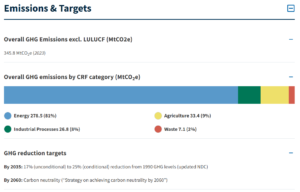
Kazakhstan’s carbon market plans also support its wider climate goals. Under its latest climate plan, Kazakhstan aims to cut net greenhouse gas emissions by 17% from 1990 levels by 2035. With international support, the country could target a 25% reduction.

Kazakhstan Emissions Trading System emissions and targets
Source:

Kazakhstan also aims to reach carbon neutrality by 2060. The country expects changes in its power sector to help lower emissions. Under its main climate pathway, Kazakhstan projects net emissions of about 328 million tonnes of CO2e in 2030 and about 320 million tonnes in 2035.

Carbon projects can help fund emissions cuts and carbon removal. Still, carbon credits alone cannot deliver Kazakhstan’s climate goals. The country must also reduce emissions from energy and heavy industry, where fossil fuels remain important.

Exporters Face a Growing Carbon Challenge

Kazakhstan’s carbon market plans also matter for its exporters. The European Union’s Carbon Border Adjustment Mechanism (CBAM) entered its full phase in 2026. Kazakhstan has highlighted the possible impact on its industrial exporters and the need for better emissions data and carbon pricing.

This is important for carbon-intensive industries such as metals. A stronger domestic carbon market could help Kazakh companies measure emissions more accurately and prepare for rising carbon costs.

It could also make the country’s carbon projects more attractive to international investors if Kazakhstan can provide reliable monitoring, verification and accounting.

Land Is Only the Starting Point

Kazakhstan’s decision to identify 5.2 million hectares for potential carbon projects provides the country with a large base for new emissions reduction and carbon removal projects. But land alone will not create a successful carbon market.

Developers need clear rules, good monitoring and independent verification. International buyers also need confidence that credits represent real emissions reductions or carbon removals.

Kazakhstan already has a domestic ETS. It is now building new rules that could connect its carbon market with international climate finance.

If the new system works as planned, the 5.2 million hectares could become an important source of future carbon projects. The broader market reforms could also give those projects a path to buyers in Kazakhstan and abroad.

The next test will be how quickly Kazakhstan turns the available land and new rules into verified, investable, and internationally transferable carbon units.

The post Kazakhstan Opens 5.2M Hectares for Carbon Projects, Eyes Article 6 Credit Trading appeared first on Carbon Credits.
BHP Profit Soars 30% While Emissions Rise, Targets Net Zero With Up to 5M Carbon Credits

BHP Profit Soars 30% While Emissions Rise, Targets Net Zero With Up to 5M Carbon Credits

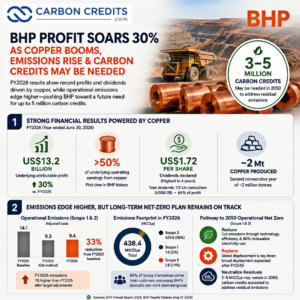
Mining giant BHP delivered stronger-than-expected financial results for FY2026 as surging copper prices drove growth and lifted shareholder returns. However, the company also reported that its operational emissions edged higher.

Copper played a bigger role in the result. BHP reported that copper made up over half of its underlying operating earnings for the first time. The company also produced around 2 million tonnes of copper for the second straight year.

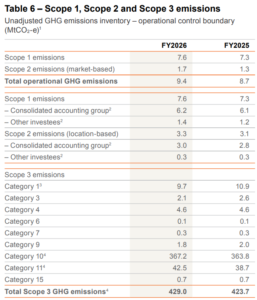
At the same time, BHP’s FY2026 Annual Report shows that its operational greenhouse gas emissions rose slightly year-on-year on an adjusted basis. The company reported 9.4 million tonnes of CO2e (MtCO2e) in Scope 1 and Scope 2 emissions from its operated assets.

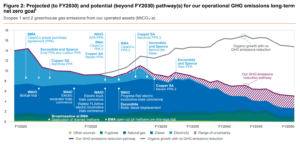
BHP has cut adjusted operational emissions by 33% from its FY2020 baseline. However, it still finds some emissions hard to eliminate. The miner says it might need 3 million to 5 million tonnes of carbon credits to help tackle residual emissions and meet its 2050 operational net-zero target.

The contrast highlights BHP’s two-track challenge: growing its business around copper and other future-facing commodities while cutting emissions across a large and complex mining portfolio.

Copper Powers BHP Profit and Dividend Growth

BHP’s strong FY2026 financial results give the miner more room to invest in growth and its long-term decarbonization plans.

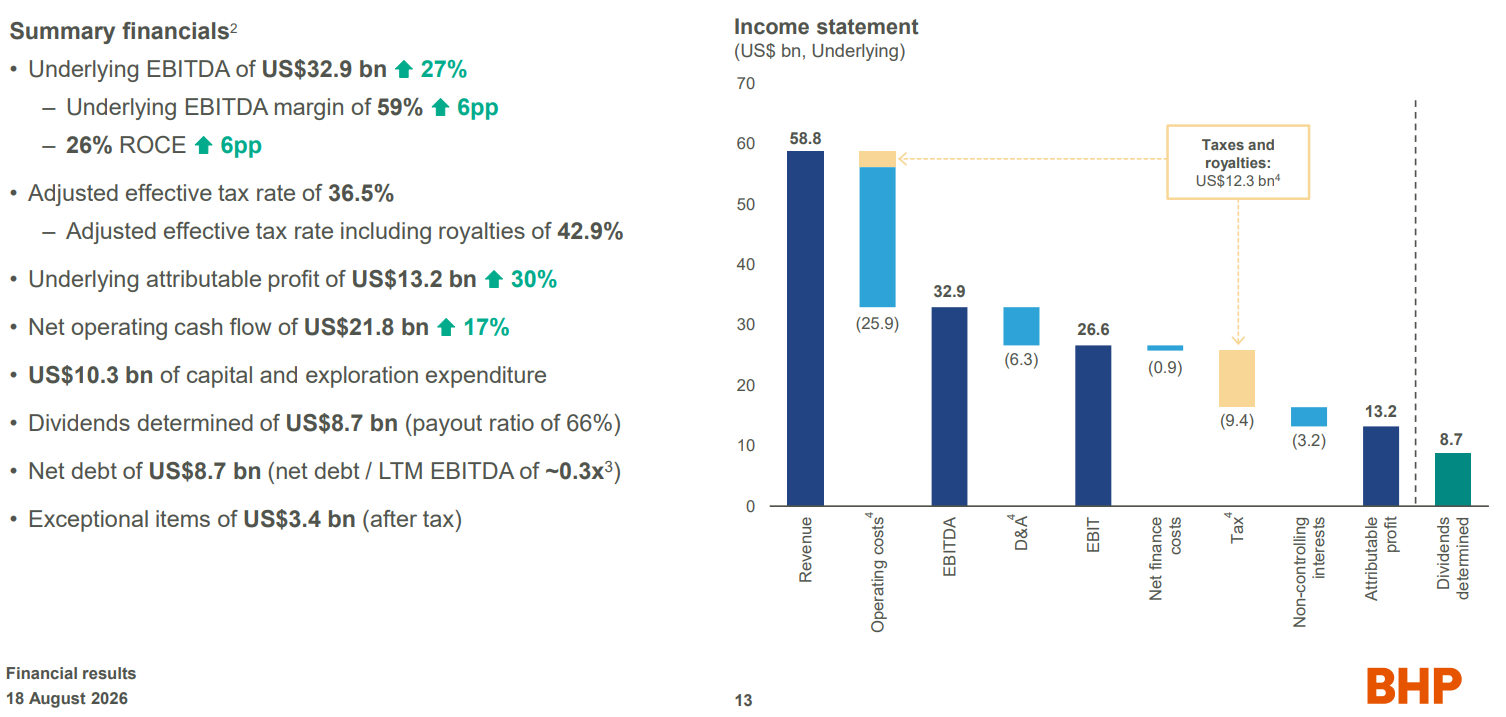
The company reported US$13.2 billion in underlying attributable profit, a 30% increase from FY2025 and above the US$12.66 billion analyst consensus cited by Reuters. BHP also reported US$9.8 billion in attributable profit for the year.

BHP financial results FY2026
Source: BHP Financial Report

Copper drove much of the improvement. Copper, including gold and uranium byproducts, generated US$18.19 billion in operating earnings, compared with US$14.53 billion from iron ore, making copper BHP’s largest earnings contributor.

BHP declared US$1.72 per share in dividends, its highest payout in four years. The company said total shareholder dividends reached 172 US cents per share, or US$8.7 billion, equal to 66% of underlying attributable profit.

The stronger result comes as BHP increases its focus on copper, which it expects to play a growing role in the global energy transition. BHP shares rose 2.65% to A$63.85 on August 18. Investors responded positively to the stronger-than-expected FY2026 results and higher dividends.

BHP stock price

However, the Australian miner also reported rising GHG emissions in its 2026 Annual Report.

BHP’s Operational Emissions Tick Higher

BHP’s adjusted operational emissions fell from 14.1 MtCO2e in FY2020 to 9.4 MtCO2e in FY2026, a 33% reduction from its baseline. However, progress was not linear.

BHP reported higher emissions at BHP Mitsubishi Alliance (BMA) because of increased material movement and more methane-intensive mining areas. Emissions at New South Wales Energy Coal (NSWEC) also increased because of higher production and a revised methane emissions model.

Stable performance at Western Australia Iron Ore and Escondida helped balance some of those increases. The temporary suspension of Western Australia Nickel also contributed.

BHP also changed how it calculates Scope 2 emissions at its Australian operations by using a national residual mix factor (RMF) where available. Applying the new method changed the reported FY2025 comparison from a 36% reduction against the FY2020 baseline to 34%.

BHP total ghg emissions FY2026
Source: BHP Annual Report

That makes the adjusted year-on-year comparison important. BHP says FY2026 emissions were 1% higher than FY2025 after applying the adjustments used for its climate targets.

Scope 3 Emissions Dwarf BHP’s Operational Footprint

BHP’s wider emissions footprint is much larger when it includes its value chain. The company reported 429.0 MtCO2e of Scope 3 emissions in FY2026, up 1% from 423.7 MtCO2e in FY2025. Most of those emissions come from customers processing BHP’s products.

The downstream processing of iron ore and steelmaking coal accounted for 85% of reported Scope 3 emissions. Energy coal combustion contributed another 10%, while direct suppliers accounted for 2% and upstream and downstream shipping for 1%.

BHP has a separate long-term goal to reach net-zero Scope 3 emissions by 2050. The company says reaching that goal is uncertain. It relies on customers using lower-emissions steelmaking technologies.

Its 2050 operational net-zero goal is different. That goal covers only Scope 1 and Scope 2 emissions from BHP’s operated assets.

BHP ghg emissions scope 1 and 2 net zero
Source: BHP

BHP May Need 3–5 Million Carbon Credits

The biggest new carbon market figure in the report comes from BHP’s long-term operational emissions pathway. BHP says it intends to reduce emissions through structural measures wherever technology is mature, commercially available, and viable. It expects carbon credits to address emissions that remain after those measures.

The company now estimates that 3 MtCO2e to 5 MtCO2e of emissions could remain in CY2050. BHP says it would need carbon credits to offset those emissions and achieve its net-zero operational goal.

  • That range translates into roughly 3 million to 5 million carbon credits, as each credit represents one tonne of CO2e.

BHP stresses that this is an estimate, not a firm future purchase commitment. The company says its estimate could change as low- and zero-emissions technologies improve.

This distinction matters. BHP does not plan to use offsets as a substitute for cutting its operational emissions. Instead, it expects credits to cover the residual emissions that it cannot eliminate.

Technology Delays Could Increase Reliance on Offsets

BHP says diesel displacement remains its largest future lever for cutting operational emissions. The company has made progress on renewable electricity. It reported 80% renewable electricity usage across its operated assets globally. BHP also says its BMA mines in Queensland moved to 100% renewable power from July 2026.

The harder challenge is replacing diesel in heavy mining equipment.

BHP began trials of battery-electric haul trucks and locomotives during FY2026. At Jimblebar in Western Australia, it started testing two Caterpillar battery-electric haul trucks in March 2026. It also began trials involving two Wabtec FLXdrive battery-electric locomotives at Port Hedland.

However, BHP does not expect broad deployment of battery-electric mining systems across its operations until after FY2030. The company says some technologies needed for diesel displacement remain under development. It also faces challenges around charging infrastructure, power systems, mine planning, maintenance, and workforce skills.

BHP expects its continued operational decarbonization work to require at least US$4 billion of incremental nominal spending in the 2030s.

BHP emissions rise and carbon credits needed 2050

Methane Remains Another Challenge

Diesel is not BHP’s only difficult emissions source. Methane accounted for 12% of BHP’s Scope 1 and Scope 2 emissions in FY2026. The company says it can capture and abate drainage methane at its underground BMA steelmaking coal mine when it is safe and practical to do so.

Open-cut mines present a harder problem. BHP says no proven technology can currently abate fugitive methane from open-cut mines at scale. The company started a proof-of-concept trial for novel methane gas drainage at an operating open-cut mine during FY2026. It will continue that work in FY2027.

These technology gaps help explain why BHP expects some residual emissions to remain in 2050.

Carbon Credits Could Become BHP’s Net-Zero Backstop

BHP’s latest financials and emissions data show both progress and a growing challenge. The company has already cut adjusted operational emissions by 33% from FY2020. It has also expanded renewable electricity use and started testing technologies that could eventually replace diesel.

Yet, emissions increased slightly in FY2026, while some of the technologies needed for deeper cuts remain immature. That leaves carbon credits as part of BHP’s long-term pathway.

The company now thinks that 3 million to 5 million tonnes of residual emissions might still exist in 2050. This could lead to a future need for a similar amount of carbon credits.

For carbon markets, the figure is significant. It shows how even major miners pursuing large operational reductions may still depend on high-quality carbon removals or other eligible credits to address hard-to-abate emissions.

The next decade will determine how large that gap ultimately becomes. If electrification, renewable power and methane technologies advance faster than expected, BHP could reduce its reliance on offsets. If technology deployment falls short, the company’s need for carbon credits could grow.

The post BHP Profit Soars 30% While Emissions Rise, Targets Net Zero With Up to 5M Carbon Credits appeared first on Carbon Credits.
Vietnam Approves Singapore Carbon Pact, Opening New Article 6 Market

Vietnam Approves Singapore Carbon Pact, Opening New Article 6 Market

Vietnam and Singapore have agreed on a carbon credit deal. This brings them closer to starting cross-border carbon trading under Article 6 of the Paris Agreement.

The Vietnamese Government issued Resolution 235/NQ-CP, approving the Implementation Agreement on carbon credit cooperation with Singapore. It also assigned the Ministry of Foreign Affairs to complete the required procedures and notify the agreement’s entry into force.

The move gives Vietnamese companies and project developers a clearer legal path to generate carbon credits for transfer to Singapore.

The two countries originally signed the agreement on September 16, 2025. Singapore’s government states that the pact sets up a legal framework. This framework helps generate and transfer carbon credits from projects that follow Article 6.

Vietnam Moves Singapore Carbon Pact Toward Implementation

The August 2026 approval is an important step because the agreement now moves closer to actual implementation. The pact allows eligible mitigation projects in Vietnam to generate outcomes that can become internationally transferred mitigation outcomes (ITMOs). Vietnam can then authorize those outcomes for transfer to Singapore.

Article 6.2 provides the rules for countries to cooperate on these transfers. It also requires strong accounting to ensure that countries do not count the same emissions reduction twice.

Singapore’s carbon market platform states that its Implementation Agreements set up a two-way framework. This framework covers project approval, reporting, and necessary adjustments. These agreements also allow private companies to develop projects that can generate ITMOs.

For Vietnam, the framework could help connect domestic climate projects with international buyers and financing.

Projects Must Meet Carbon Credit Rules

The agreement does not allow every carbon credit from Vietnam to enter Singapore’s market. Project developers must follow the rules of both countries and meet the requirements of the bilateral agreement. Singapore has also set environmental integrity rules for international carbon credits.

These rules cover issues such as double counting and leakage. Singapore requires eligible credits to meet Article 6 requirements and represent verified emissions reductions or removals.

Carbon Credit generation article 6
Source: UNFCCC

The Singapore-Vietnam framework also sets out a formal process for project approval, ITMO issuance, and transfer. Singapore’s current Vietnam framework says the Joint Committee will oversee the agreement. The committee includes representatives from Singapore’s National Environment Agency and Vietnam’s Ministry of Agriculture and Environment.

However, some operational details remain under development. Singapore will share more details soon on the documents and steps required for Article 6 authorization. The August approval makes it legal, but developers still need to finish the detailed approval process to transfer credits.

Corresponding Adjustments Protect Market Integrity

Corresponding adjustments form a key part of the agreement. When Vietnam approves an ITMO transfer to Singapore, it must adjust accordingly when the parties make that transfer. The agreement requires Vietnam to follow the Article 6.2 guidance adopted under the Paris Agreement.

This accounting step stops Vietnam from using the same emissions reduction for its climate target after sending it to Singapore. Singapore can then recognize the transferred mitigation outcome for an approved purpose.

The agreement also requires both countries to meet reporting obligations under the Paris Agreement. This includes reporting under Article 6.2 and Article 13.

These rules matter because the growth of international carbon markets depends on credible accounting. Without these safeguards, the same emissions cut might back multiple climate claims.

Singapore’s Carbon Tax Creates Demand for New Credits

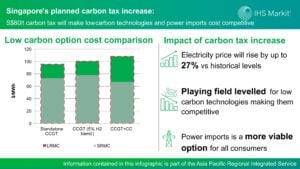
Singapore has a strong policy reason to develop a supply of high-quality international carbon credits. The country introduced its carbon tax in 2019. The rate reached S$45 per tonne in 2026 and 2027, and Singapore aims to raise it to S$50 to S$80 per tonne by 2030.

singapore carbon tax increase
Source: S&P Global

Since January 2024, facilities that owe carbon tax can use eligible international carbon credits. They can offset up to 5% of their taxable emissions. This creates potential demand for eligible credits from Vietnam.

However, supply remains limited. Singapore’s National Environment Agency says carbon credit projects typically take up to four years to generate credits. It also said stronger market focus on credit integrity and changing international rules have slowed the supply of eligible credits.

Vietnam could be a key future supplier if projects get approved. This would allow them to earn credits that meet Singapore’s needs.

The Deal Adds Climate Benefits Beyond Carbon Trading

The wider Singapore Article 6 framework also includes measures to support climate action in host countries. The country requires carbon credit developers to contribute 5% of the value of authorized Article 6 carbon credits under its Implementation Agreements. The money supports adaptation efforts in host countries and/or the UNFCCC Adaptation Fund.

Singapore also requires 2% of Article 6-authorized carbon credits to be canceled at issuance. These credits cannot enter the market, helping contribute to an overall reduction in global emissions.

The Singapore-Vietnam agreement itself gives its Joint Committee a role in determining additional contributions to overall mitigation and adaptation at the time of issuance. These measures aim to extend the climate benefits of carbon trading. They go beyond just transferring emissions reductions between countries.

Vietnam Could Unlock New Climate Finance

Vietnam’s approval could create new opportunities for investment in emissions reduction projects. The two countries have previously highlighted potential cooperation in areas such as clean energy, sustainable agriculture, technology and the circular economy. Vietnam has also sought Singapore’s experience in operating carbon credit markets and exchanges.

The agreement can help Vietnamese project developers reach international buyers. It may also attract financing for projects that cut or eliminate greenhouse gas emissions.

However, the agreement does not guarantee a certain volume of carbon credits or a specific price. Developers still need to secure project approvals, meet methodology requirements, and complete verification. They must also find buyers for the resulting credits.

The timing depends on how quickly Vietnam and Singapore finish the procedures. It also relies on how fast eligible projects move through the system.

Singapore Builds a Growing Article 6 Carbon Network

The Vietnam pact forms part of Singapore’s wider strategy to build a network of bilateral carbon market agreements. As of June 2026, Singapore had signed 11 Implementation Agreements with countries including Vietnam, Mongolia and the Philippines. The full list also includes Papua New Guinea, Ghana, Bhutan, Chile, Peru, Rwanda, Paraguay and Thailand.

Singapore has signed 20 memorandums of understanding with over 20 countries, said Trade and Industry Minister of State Alvin Tan. The government is working with businesses to develop projects that can generate Article 6 credits.

Singapore’s carbon tax and international credit framework give these partnerships a potential source of demand. At the same time, the government says it needs more projects to build the supply of eligible credits.

Vietnam’s approval therefore comes at an important time for both countries. For Vietnam, the agreement could help channel more international finance into emissions reduction projects. For Singapore, it could expand its future supply of high-integrity international carbon credits.

The next step will be implementation. As Vietnam completes the remaining procedures and both governments operationalize the project approval process, the pact could turn into a new channel for Article 6 carbon trading and climate finance in Southeast Asia.

The post Vietnam Approves Singapore Carbon Pact, Opening New Article 6 Market appeared first on Carbon Credits.
NexGen Energy Begins Construction of Rook I as Uranium Demand Rises

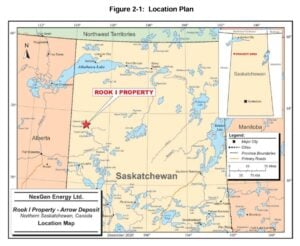
NexGen Energy has started building its Rook I uranium project in Saskatchewan, Canada. This marks a significant step toward creating one of the largest new uranium mines in the world.

It was reported that the C$2.2 billion ($1.6 billion) project focuses on the high-grade Arrow deposit. Once completed, Rook I is expected to produce around 30 million pounds of uranium each year. This would place it among the top uranium producers globally and make NexGen a key supplier for the growing nuclear energy market.

Uranium demand is rising sharply. Nuclear power is gaining traction as countries seek reliable, low-carbon electricity. The rapid growth of artificial intelligence is also increasing energy needs, NexGen revealed in a post on X.

Rook I Moves to Construction Phase

Major earthworks and surface infrastructure are in progress. The company has commissioned a 3,000-foot airstrip and completed expanded site accommodations, which are now in use.

NexGen plans to finish the full 5,840-foot airstrip by the end of 2026. Shaft development is set to begin in 2027.

Building the underground mine and processing facilities will take about four years. The project will use conventional underground mining, followed by processing the ore into uranium concentrate, known as yellowcake.

Importantly, the project has cleared major regulatory hurdles. The Canadian Nuclear Safety Commission approved the environmental assessment in March and granted NexGen a construction license for Rook I.

This approval allows the company to move forward after years of exploration and regulatory work.

rock1

A High-Grade Uranium Deposit

The Arrow deposit gives Rook I a major edge: exceptionally high uranium grades.

  • The 2021 feasibility study outlined probable reserves of about 239.6 million pounds of uranium at an average grade of 2.37% U3O8.
  • NexGen’s total measured and indicated resource stands at about 256.7 million pounds, including the reserves, plus another 80.7 million pounds in inferred resources.

These grades are well above the global average for uranium deposits.

As a result, the project needs to move less rock to produce a large amount of uranium. NexGen estimates only about three trucks per day will be needed to feed the mill, while roughly 1.5 trucks per day will remove processed material.

This relatively low movement could reduce the project’s infrastructure needs and environmental impact compared to lower-grade mining operations.

The geology supports conventional underground mining. Unlike some deposits that need complex methods like in-situ recovery, Arrow is located in hard rock at depth. The company says this setting allows for a more predictable mining operation.

nextGen uranium
Source: NextGen

A Large Production Profile

The scale of Rook I is critical for the uranium market.

The 2021 feasibility study outlined an 11-year mine life and projected total production of about 233.6 million pounds of yellowcake. It estimated an after-tax net present value of C$3.5 billion at an 8% discount rate, a 52.4% internal rate of return, and a payback period of less than one year.

The planned annual production of about 30 million pounds would exceed the licensed capacity of Cameco’s McArthur River-Key Lake operations, which stands at 25 million pounds.

Cameco expects to produce between 14 million and 16.5 million pounds from those operations in 2026.

Thus, Rook I could significantly boost global uranium supply once it begins production.

Nuclear Power Is Driving Long-Term Uranium Demand

The timing of this project is crucial.

Around 80 nuclear reactors are under construction worldwide, adding about 88 gigawatts of new capacity. This could increase global nuclear capacity by roughly 20% by the early 2030s.

At the same time, 38 countries aim to triple global nuclear capacity by 2050.

If achieved, global nuclear capacity could rise from around 380 GW to about 1,200 GW. This expansion would require a substantial increase in uranium supply.

Artificial intelligence could add to the demand.

Data centers need a lot of electricity, and the global AI buildout is speeding up. If the U.S. meets its AI-related electricity needs entirely with nuclear power, uranium demand could reach as much as 60 million pounds annually by 2030, according to NexGen’s estimates.

This highlights the scale of the challenge facing the uranium industry.

The Supply Problem Could Be Even Bigger

Uranium supply cannot quickly respond to sudden demand increases.

Developing a new mine can take 15 to 20 years from discovery to production. Today’s investment decisions will affect uranium supply well into the 2030s and 2040s.

NexGen forecasts a potential uranium supply deficit of about 335 million pounds per year by 2040. Meeting projected demand of roughly 530 million pounds would require mine production to triple from current levels.

These numbers show why new projects like Rook I are increasingly important.

The industry has mined about 8.6 billion pounds of U3O8 since uranium mining began. Over the next 25 years, the world could need about 7.3 billion pounds.

In short, the nuclear industry could consume nearly as much uranium in the next quarter-century as it has mined in the last 80 years.

Rook I Could Support a Low-Carbon Energy System

The project’s potential goes beyond just uranium production.

Nuclear power generates electricity with very low operational carbon emissions. Therefore, more uranium supply could help expand nuclear generation as countries aim to cut emissions while ensuring reliable electricity.

  • NexGen estimates Rook I could produce enough uranium to power around 46 million homes with carbon-free electricity.
  • The company also estimates that this nuclear generation could displace over 300 million tonnes of CO2 annually, equivalent to taking nearly 70 million cars off the road each year.

These figures depend on how the uranium is used and the assumptions behind the calculations. Still, they show why high-grade uranium projects are gaining attention as nuclear power returns to global energy discussions.

For NexGen, the next challenge is execution.

With construction now underway, Rook I is shifting from long-term development to a potential new source of uranium supply. If NexGen delivers on time, the mine could start production just as nuclear power, AI-driven electricity demand, and energy security concerns put more pressure on the global uranium market.

The post NexGen Energy Begins Construction of Rook I as Uranium Demand Rises appeared first on Carbon Credits.
CATL Says All 20 Battery Plants Are Carbon Neutral as Supply Chain Takes Center Stage

CATL Says All 20 Battery Plants Are Carbon Neutral as Supply Chain Takes Center Stage

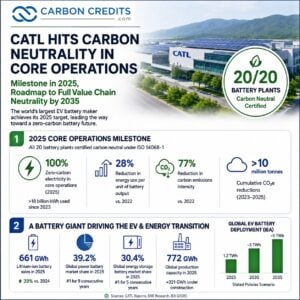
CATL, the world’s largest electric vehicle battery maker, says it has achieved carbon neutrality across its core operations, with all 20 battery plants certified as carbon neutral. The Chinese battery giant announced the milestone on August 17, 2026, after meeting a target it set for 2025. CATL also unveiled a new plan to make its entire battery value chain carbon neutral by 2035.

The timing is important. Global battery demand continues to grow quickly. The International Energy Agency (IEA) says global EV battery deployment reached 1.2 TWh in 2025, up almost 30% from 2024. It expects EV battery deployment to reach almost 3 TWh by 2030 under its Stated Policies Scenario.

That growth puts more pressure on battery makers to cut emissions not only from factories, but also from the wider supply chain. Robin Zeng, Chairman and CEO of CATL, remarked:

“As the world ramps up efforts toward net-zero, zero-carbon batteries will not be a choice but a necessity in the near future. We are ready to share our technologies and experience with partners across the industry, helping to shape global carbon standards and advance industry-wide decarbonization.”

CATL Reaches Its 2025 Carbon Neutrality Goal

CATL announced its core-operations carbon neutrality target in 2023. The company planned to reach carbon neutrality in its core operations by 2025 and across its battery value chain by 2035.

The battery giant says it met the first goal as planned. All 20 battery plants have now received carbon-neutral certification. CATL says 100% of the electricity used in its core operations came from zero-carbon electricity in 2025.

Since 2023, the company says it has consumed more than 18 billion kWh of zero-carbon electricity.

CATL also reports that energy use per unit of battery output fell 28% from 2022 levels, while carbon emissions intensity fell about 77% over the same period.

  • From 2023 to 2025, CATL says it achieved more than 10 million tonnes of cumulative CO2e emissions reductions.

The company uses the ISO 14068-1 framework for carbon-neutral certification. This matters because “carbon neutral” does not mean a factory produces no greenhouse gas emissions at all. It means the company applies measures to reduce emissions and address the remaining emissions within the relevant carbon-neutrality framework.

CATL’s own data also shows why reducing factory emissions matters. The company has built a large manufacturing base to meet rising battery demand.

A Battery Giant With a Growing Footprint

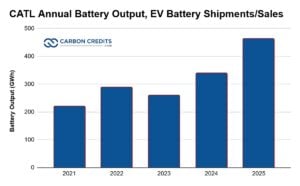
CATL’s scale makes the milestone significant for the wider battery industry. The company sold 661 GWh of lithium-ion batteries in 2025, a 39% increase from the previous year. 

CATL top battery makers global SNE research

SNE Research data cited by CATL put its global power battery market share at 39.2%, keeping it in first place for the ninth consecutive year. CATL’s global production capacity reached 772 GWh in 2025, with another 321 GWh under construction at the end of the year.

The company also remains a major player in energy storage. Its energy storage battery shipments held a 30.4% global market share in 2025, according to SNE Research, marking its fifth consecutive year in first place.

The wider market is moving in the same direction. The IEA estimates that global lithium-ion battery manufacturing capacity exceeded 4 TWh at the end of 2025, about 30% higher than a year earlier. China accounted for more than 80% of global capacity.

CATL Annual Battery Output, EV Battery Shipments, Sales
Source: CATL Reports

As production expands, reducing the emissions intensity of each battery becomes increasingly important.

The Supply Chain Is the Bigger Climate Challenge

CATL’s factory milestone does not solve the full emissions problem. The company says more than 80% of carbon emissions across its product lifecycle come from its supply chain. It also says total value chain emissions exceed those from its core operations by more than five times.

Those emissions come from activities such as raw-material production, processing, manufacturing, and logistics. This makes the next stage of CATL’s climate strategy much harder. The company can directly control its own factories. It has less direct control over mines, chemical producers, material suppliers, and transport companies.

The Chinese firm has already collected baseline carbon data from more than 100 core Tier 1 suppliers. It wants to expand carbon data coverage across key upstream parts of the supply chain.

Starting in 2027, CATL plans to require new suppliers to provide product carbon footprint data. It will also consider renewable electricity use and energy efficiency in annual supplier reviews. Suppliers with stronger emissions performance could receive better order allocation and longer-term agreements.

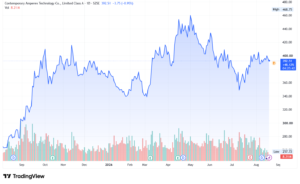
CATL 300750 stock price

The announcement has acted as a long-term stabilizer rather than a short-term price booster, with the stock seeing a minor 0.91% dip shortly after. While this green milestone secures CATL’s access to strict markets like Europe, investors remain cautious. This is because 80% of the company’s total emissions come from its suppliers, meaning CATL now faces the harder, more expensive challenge of cleaning up its upstream supply chain by 2035.

CATL Targets the Full Value Chain by 2035

CATL’s new roadmap focuses on four main areas: materials and process innovation, manufacturing, green logistics, and battery recycling. The company plans to increase the use of lower-carbon materials and improve production processes. It also aims to achieve 100% green electricity use across its value chain by 2035.

CATL plans to expand zero-carbon logistics across its supply chain and continue building its global battery recycling network through Brunp Recycling.

The company has already taken steps on recycling. CATL says it recycled 210,000 tonnes of spent batteries in 2025, up 63.2% from 2024. It regenerated 24,000 tonnes of lithium salts, an increase of 40.4%.

CATL carbon neutral

CATL will also begin a supply chain decarbonization program with an initial group of 30 core suppliers. These actions could have a wider effect because battery supply chains remain highly concentrated. 

Why the Milestone Matters for EVs

Battery production sits at the center of the electric vehicle transition. The IEA expects global EV battery deployment to more than double from 1.2 TWh in 2025 to almost 3 TWh by 2030 under its Stated Policies Scenario. It further projects deployment to reach almost 5 TWh by 2035 under that scenario. That means battery manufacturers will need to produce far more cells while limiting their environmental impact.

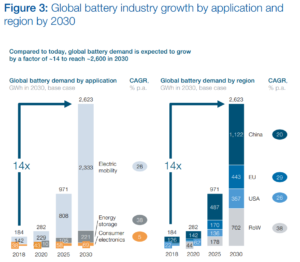
The World Economic Forum analysis shows the global battery demand will grow to over 2.6 TWh in 2030.

global EV battery demand 2030

CATL’s factory-level achievement shows that large-scale battery production can move toward lower operational emissions. But the company’s own data points to the bigger challenge: most of its product lifecycle emissions occur outside its factories.

The 2035 target will therefore depend heavily on suppliers. If CATL can push lower-carbon electricity, cleaner materials, more efficient production, lower-emission logistics and recycling deeper into its supply chain, the impact could extend well beyond its 20 plants.

From Factory Decarbonization to Supply Chain Action

CATL’s latest announcement marks a shift from controlling emissions inside its factories to tackling emissions across the battery industry. The company has already reached its 2025 core-operations carbon neutrality target and certified all 20 battery plants as carbon neutral. It now has nine years to address the much larger emissions footprint across its value chain.

The challenge is substantial. CATL says more than 80% of lifecycle emissions come from its supply chain, while global battery demand continues to climb.

The next test will be whether CATL can turn its supplier requirements and 2035 roadmap into measurable emissions cuts across mining, materials, manufacturing, logistics and recycling. For an industry expected to supply several terawatt-hours of batteries each year, that could become as important as expanding battery capacity itself.

The post CATL Says All 20 Battery Plants Are Carbon Neutral as Supply Chain Takes Center Stage appeared first on Carbon Credits.
OpenAI’s $20 Billion Georgia Data Center Puts ChatGPT’s Energy Footprint Under Scrutiny

OpenAI’s $20 Billion Georgia Data Center Puts ChatGPT’s Energy Footprint Under Scrutiny

OpenAI’s rapid expansion of ChatGPT is creating a growing energy challenge for the company and the communities hosting its data centers. That challenge is now playing out in Georgia, where OpenAI plans to build a $20 billion data center campus in Effingham County.

The project, called Project Camellia, is planned for 3.2 gigawatts (GW) of power. OpenAI says Georgia Power would deliver the electricity in phases from 2028 through 2032.

The project has drawn objections from environmental and consumer groups. They want more details about the power contract and stronger protections for Georgia electricity customers. The debate also raises a wider question for ChatGPT: how much energy and other resources will be needed as AI use keeps growing?

OpenAI Faces Questions Over Georgia Power Deal

OpenAI says it will pay the full cost of the electricity and infrastructure needed for Project Camellia. Georgia Power has also said the project will include financial protections for its customers. The ChatGPT developer stated:

“Building this infrastructure in the United States strengthens domestic industry, creates good jobs, and helps ensure American communities participate in the economic opportunity created by AI. Project Camellia can help build that foundation while creating lasting opportunity in Effingham County and Southeast Georgia, and would be entirely privately funded.”

However, environmental groups want more transparency.

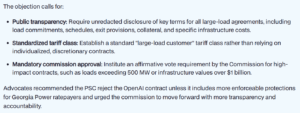
The Southern Alliance for Clean Energy, Sierra Club and Natural Resources Defense Council have objected to the proposed agreement. They say in the letter that important details remain unclear and are calling for stronger safeguards before the contract moves forward.

Their concerns include the size of the electricity load, infrastructure costs, and the possible effect on other power customers. Their letter reads:

“The magnitude of the load from the announced OpenAI project heightens the consequences of any shortcomings in the fully redacted contract’s cost-recovery provisions. A contract that does not adequately ensure recovery of all costs incurred to serve the load could leave Georgia Power customers responsible for those costs.”

OpenAI Georgia power objection
Source: Southern Alliance for Clean Energy

The issue matters because 3.2 GW is an extremely large power demand. The International Energy Agency (IEA) notes that traditional data centers often use 10 to 25 megawatts, while large AI data centers can require more than 100 MW. Project Camellia would therefore operate on a much larger scale than a typical data center.

OpenAI says the project will also be designed to reduce its impact on the local power system. It plans to lower its electricity use during periods of high demand so that residential customers are less affected.

How Much Energy Does ChatGPT Really Use?

The Georgia project also highlights a problem with measuring ChatGPT’s environmental footprint. OpenAI does not publish one total figure for the electricity used by ChatGPT worldwide.

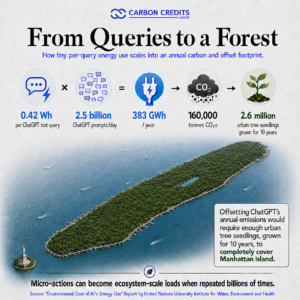
The energy needed for each query also varies. It depends on the model, the task, the length of the response, and the hardware used. OpenAI cites an Epoch AI estimate that a typical GPT-4o query uses about 0.3 watt-hours of electricity.

That number may sound small, but ChatGPT operates at huge scale. The United Nations University estimates that ChatGPT handles about 2.5 billion prompts each day. Its analysis estimates that global AI systems could have a much larger resource footprint as usage expands.

This creates an important distinction. Lower energy use per query does not necessarily mean lower total energy use. If the number of AI users and tasks grows faster than efficiency improves, overall electricity demand can still increase.

ChatGPT carbon footprint

That is one reason the environmental debate is shifting from individual prompts to the much larger data center system that supports them.

AI Is Driving Data Center Power Demand Higher

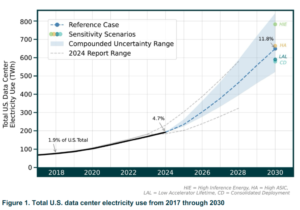
Data centers are becoming a major source of electricity demand. The IEA estimates they consumed about 415 TWh in 2024, with demand expected to more than double to 945 TWh by 2030, nearly 3% of global electricity use.

AI is a key driver. Electricity use from accelerated servers, which mainly support AI workloads, is expected to grow about 30% annually through 2030 in the IEA’s base case.

The U.S. faces an especially sharp increase. Data centers could account for nearly half of U.S. electricity demand growth through 2030, with consumption rising about 240 TWh from 2024 levels.

US data centers electricity use 2030

Project Camellia is part of this broader trend. As OpenAI and other AI companies expand computing capacity, utilities will need more power generation and grid infrastructure.

Water Is Another Environmental Concern

AI data centers also require water for cooling, although usage varies by facility and cooling system.

OpenAI says Project Camellia will use a closed-loop cooling system that recirculates water rather than continuously withdrawing and discharging large volumes. The company says this design will keep ongoing water use low.

The issue remains important as AI data centers expand. A 2026 United Nations University study estimates that global data centers could have a water footprint of about 9.3 trillion liters by 2030, alongside a land footprint exceeding 14,500 square kilometers.

These figures cover the global data center system, not OpenAI or ChatGPT alone. However, they show that AI’s environmental impact extends beyond electricity use.

OpenAI Is Expanding Its AI Infrastructure

Project Camellia is also only one part of OpenAI’s wider infrastructure expansion. The company says it needs substantially more computing power as AI systems become more capable and handle longer and more complex tasks.

OpenAI is developing other large data-center projects in the United States and abroad.

  • In Michigan, its Stargate project is planned around a 1-GW data center campus. OpenAI says the site will use closed-loop cooling.
  • OpenAI is also developing infrastructure in Norway. The company initially announced a project with 230 MW of capacity, with plans that could allow for added capacity later. The company says the Norway project will use renewable power and closed-loop direct-to-chip cooling.

These projects show that OpenAI is trying to address some of the environmental effects of its growth through cleaner electricity and more efficient cooling. However, the scale of the expansion remains significant.

Transparency Will Shape AI’s Climate Debate

The Georgia dispute points to a larger issue for OpenAI and ChatGPT. AI companies are improving model efficiency, but they are also expanding their computing infrastructure at a rapid pace. The project shows how the ChatGPT boom is becoming an energy and environmental issue as much as a technology story.

OpenAI has already made commitments for Project Camellia that include paying its own energy costs, keeping water use low, and providing public reporting through an annual independent audit. The company will now need to show that these commitments work in practice.

For ChatGPT, the key issue is not simply how much electricity one prompt uses. It is the combined effect of billions of prompts, increasingly powerful models, and the data centers needed to run them.

Lower energy use per AI task will help, but the long-term impact will depend on how quickly OpenAI can improve efficiency, expand clean power, reduce water use, and provide clear data on the resources behind its growing AI systems.

The post OpenAI’s $20 Billion Georgia Data Center Puts ChatGPT’s Energy Footprint Under Scrutiny appeared first on Carbon Credits.
Samsung SDI Takes Full Control of $3.5B Indiana Battery Plant as EV Strategy Shifts

Samsung SDI Takes Full Control of $3.5B Indiana Battery Plant as EV Strategy Shifts

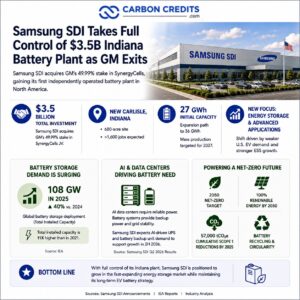
Samsung SDI is taking full control of a $3.5 billion battery plant in Indiana after General Motors decided to exit its joint venture. The South Korean battery maker will acquire GM’s 49.99% stake in SynergyCells, the joint venture developing the facility in New Carlisle, Indiana. The move gives Samsung SDI full ownership of the project and its first independently operated battery production facility in North America.

The companies originally planned the plant to produce electric vehicle (EV) batteries. Samsung SDI and GM agreed in 2024 to invest about $3.5 billion, with an initial annual capacity of 27 gigawatt-hours (GWh) and an expansion path to 36 GWh.

Mass production was targeted for 2027, but market conditions have changed. Samsung SDI now plans to use the facility initially for energy storage system (ESS) batteries and other advanced applications. The decision reflects slower-than-expected EV demand in the U.S. while battery storage demand continues to grow.

Samsung SDI Takes the Wheel in Indiana as GM Exits

Samsung SDI and GM announced their battery partnership in 2023. They finalized the Indiana joint venture in August 2024.

The project is located on a 680-acre site in New Carlisle. The original plan called for more than 1,600 jobs and annual battery production of 27 GWh in the first phase. The companies also planned to expand the facility to 36 GWh.

GM will now sell its 49.99% interest to Samsung SDI. The purchase price has not been disclosed.

The ownership change reflects the weaker-than-expected growth of EV demand, according to Samsung SDI. The two companies will end the joint venture but continue their broader strategic relationship.

They have also agreed to jointly develop next-generation prismatic battery cells for future EV applications. This keeps GM connected to Samsung SDI’s battery technology without requiring the automaker to remain an owner of the Indiana facility.

Indiana Plant Gets a New Market

The biggest change is the planned shift toward energy storage. Samsung SDI said the Indiana facility can respond to growing demand for ESS batteries in the U.S. The company has not publicly specified how much of the plant’s eventual capacity will be dedicated to ESS products.

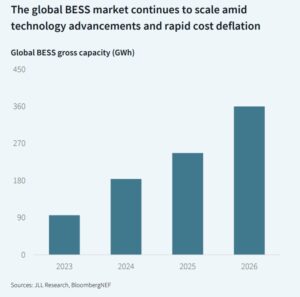
That flexibility could become important as the battery market expands beyond electric cars. The International Energy Agency (IEA) reported that global battery storage deployment reached 108 GW in 2025, up 40% from 2024. Utility-scale systems accounted for about 87 GW, or roughly four-fifths of the total.  Other industry analysis shows the following gross capacity for the battery energy storage systems (BESS) market.

global BESS market

Battery storage has become one of the fastest-growing technologies in the global power sector. Total installed battery storage capacity is now 11 times higher than in 2021, according to the IEA. The shift toward BESS therefore gives Samsung SDI another market for a factory that was originally designed around EV demand.

AI Is Adding to Battery Storage Demand

The growth of artificial intelligence is creating another source of demand for batteries. AI data centers require large amounts of electricity and highly reliable power. Battery systems can provide backup power and help manage short-term changes in electricity supply.

Samsung SDI has been targeting this market.

In its second-quarter 2026 results, the company said it expects AI-driven UPS and battery backup unit demand to support its business in the second half of the year. It also pointed to U.S. prismatic LFP battery production and expansion of EV projects as growth drivers.

Global Battery Demand Still Has Long-Term Growth

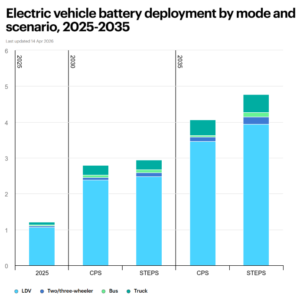
The Indiana strategy does not mean EV batteries are losing their long-term importance. The IEA’s Global EV Outlook 2026 found that global EV battery deployment reached 1.2 TWh in 2025, almost 30% higher than in 2024. EVs accounted for more than 70% of total battery deployment last year.

The agency expects global EV battery deployment to reach almost 3 TWh by 2030 under both its Current Policies Scenario and Stated Policies Scenario.

Electric vehicle battery deployment by mode and scenario
Source: IEA

Electric trucks are also becoming a larger source of battery demand. They accounted for about 8% of global EV battery deployment in 2025, up from less than 5% in 2024. The IEA expects that share to reach about 10% by 2030.

Battery manufacturing capacity is expanding as well. Global battery cell manufacturing capacity grew almost 30% in 2024, reaching more than 3 TWh. U.S. manufacturing capacity grew almost 50%, with Korean companies accounting for nearly 70% of that increase.

This supports Samsung SDI’s decision to maintain a large U.S. manufacturing presence even as the immediate EV market outlook changes.

Samsung SDI Pairs U.S. Expansion With a Net-Zero Push

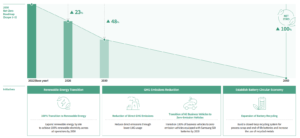
The Indiana expansion also fits into Samsung SDI’s wider environmental strategy. The company has a 2050 net-zero target and joined the RE100 initiative in 2022. Its environmental strategy includes shifting to renewable electricity, reducing direct greenhouse gas emissions, moving business vehicles to zero-emission vehicles, and expanding battery recycling.

Samsung SDI’s latest sustainability report sets a goal of 100% renewable energy use by 2050 across its operations. The company is also working to reduce direct emissions and expand the use of recycled battery materials.

The company reported that it reduced a significant amount of greenhouse gas emissions across its facilities in 2024 as part of its climate roadmap. It also reported that its cumulative direct (Scope 1) greenhouse gas reductions reached 32,000 tons by 2024, which grew to a total of 57,000 tons the following year.

Samsung Net Zero Roadmap
Source: Samsung Sustainability Report 2026

Samsung SDI is also investing in battery circularity. Its sustainability strategy includes developing closed-loop systems for production scrap and used batteries and increasing the use of recycled metals. These measures will become more important as the company expands its manufacturing footprint in North America.

Battery Strategy Is Becoming More Flexible

Samsung SDI’s takeover reflects a wider change in the battery industry. Battery manufacturers are still preparing for strong long-term EV growth, but they are also responding to changing demand in the near term. Energy storage, data centers, and other power-intensive industries are creating new markets for battery technology.

The IEA’s latest data supports this broader view. Battery storage grew 40% globally in 2025, while EV battery deployment also increased almost 30%.

For Samsung SDI, the ability to serve both markets could make the Indiana plant more valuable. The company will have greater control over the facility after acquiring GM’s stake. It can also adjust its production strategy as demand changes.

At the same time, the company still has a relationship with GM through the development of next-generation prismatic EV batteries.

Samsung SDI battery plant indiana

A New Role for Samsung SDI’s Indiana Plant

Samsung SDI’s decision to take full control of the Indiana facility changes the project’s original purpose but not its broader strategic importance.

The $3.5 billion plant was initially planned as a major U.S. EV battery hub, with 27 GWh of initial annual capacity, an expansion path to 36 GWh, and more than 1,600 expected jobs.

Now, its first major role could be in the BESS market. That shift comes as global battery storage reaches record levels and AI increases demand for reliable electricity infrastructure. At the same time, EV battery demand continues to grow and is expected to approach 3 TWh annually by 2030.

Samsung SDI’s move shows how the battery industry is adapting to a changing market. Rather than relying on EV demand alone, the company is positioning its Indiana investment to serve a broader mix of electric mobility, grid storage, and emerging power needs.

The post Samsung SDI Takes Full Control of $3.5B Indiana Battery Plant as EV Strategy Shifts appeared first on Carbon Credits.
Lloyds Sets £100B Sustainable Finance Target to Power the UK’s Net-Zero Shift

Lloyds Sets £100B Sustainable Finance Target to Power the UK's Net-Zero Shift

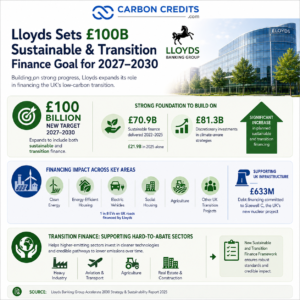
Lloyds Banking Group is setting a new £100 billion sustainable and transition finance target for 2027 through 2030, giving the UK banking group a larger role in financing companies as they cut emissions and invest in cleaner technologies.

The new goal is part of Lloyds’ Accelerate 2030 strategy. It broadens the bank’s focus on sustainable finance. Now, it also includes transition finance. This helps higher-emitting companies and sectors shift to lower-carbon business models.

The target comes after Lloyds delivered £70.9 billion of sustainable finance from 2022 through 2025, including £21.9 billion in 2025 alone. The new four-year target therefore represents a significant increase in the bank’s planned financing activity.

Lloyds Expands Its Sustainable Finance Ambition

Lloyds’ new target builds on several existing sustainable finance commitments. The bank previously targeted £30 billion of sustainable finance for Commercial Banking customers from 2024 through 2026.

It also set goals for £10 billion of EV financing and £11 billion of mortgage lending for EPC A and B-rated properties from 2025 through 2027.

The new £100 billion goal is broader. It covers both sustainable finance and transition finance. This allows Lloyds to support businesses that may not yet qualify for green finance but have credible plans to reduce emissions.

That distinction is important for sectors such as heavy industry, transport, agriculture and real estate. Many of these industries cannot switch to low-carbon systems overnight.

Transition finance offers loans and other financial products. This helps companies invest in cleaner equipment, boost energy efficiency, or change their production systems.

£70.9B Already Deployed Sets the Stage for More

Lloyds has made sustainable finance a growing part of its broader business strategy. The bank reported £70.9 billion of sustainable finance since 2022, with £21.9 billion supported in 2025. It also reported £81.3 billion in discretionary investments in climate-aware strategies.

The bank’s sustainable finance activity covers several areas, including: 

  • Clean energy,
  • Energy-efficient housing,
  • Electric vehicles,
  • Social housing,
  • Agriculture and
  • Other projects linked to the UK’s transition.

Lloyds also committed £633 million in debt financing to Sizewell C, the UK’s new nuclear power project. The bank says one in eight electric vehicles on UK roads is financed by the Group. These figures show that the new £100 billion goal is not a standalone climate pledge. It builds on an existing lending and investment business.

Lloyds Banking Group 100B euro sustainable finance

Transition Finance Targets Hard-to-Abate Sectors

The biggest change is the addition of transition finance. The UK government defines transition finance as financial products and services that help higher-emitting companies and activities reduce emissions over time. These products should support a credible pathway that aligns with global climate goals.

This matters because many businesses cannot immediately move to zero-emission operations.

A steel producer, for example, may need years to replace equipment. An airline may need time to adopt sustainable aviation fuel and more efficient aircraft. Farmers may need financing to change equipment and farming practices.

Transition finance can help fund these steps. Lloyds’ 2025 Sustainable Financing Framework already said it was reviewing how to include transition finance. The bank has now developed a new Sustainable and Transition Finance Framework to support the expanded target.

The framework is intended to give the bank a consistent basis for deciding which activities qualify for sustainable and transition finance.

The UK Needs Billions More to Fund Energy Transition

Lloyds is expanding its target as the UK works to increase private investment in the energy transition. UK energy transition investment hit £51.1 billion in 2024, according to government data from BloombergNEF. This is a drop from £58.1 billion in 2023, but still higher than early 2020s levels.

The UK government is also trying to make London a larger global center for sustainable finance.

In 2025, the government said 70% of FTSE 100 companies had already developed many of the key elements of a transition plan. It also said net-zero sectors were growing three times faster than the overall economy in the previous year, based on CBI Economics data.

Energy Secretary Ed Miliband noted:

“This government is determined to make the UK the sustainable finance capital of the world as we seize the huge economic opportunities provided by clean energy.”

The government has backed recommendations from its Transition Finance Market Review to help expand the market. For banks such as Lloyds, that creates an opportunity to finance companies that need capital to meet changing climate and energy requirements.

Lloyds Sees Climate Finance as a Growth Opportunity

Lloyds is also presenting the new target as a commercial opportunity. The bank’s wider Accelerate 2030 strategy targets mid-single-digit compound annual income growth from 2027 through 2030. It also aims for a cost-to-income ratio below 45% and return on tangible equity of about 20% by 2030. 

That means sustainable finance is being placed alongside the bank’s broader growth plans. This approach is becoming more common across the financial sector. Banks are looking at the transition not only as a climate issue but also as a source of new lending, investment and advisory opportunities.

Lloyds says its purpose is to “Help Britain Prosper.” Its sustainability strategy links financing the transition with long-term economic growth and resilience.

The bank will provide over £35 billion in new finance to UK companies in 2026. This includes £9.5 billion specifically for small and medium-sized businesses.

Lloyds’ Own Net-Zero Targets Raise the Stakes

As a major lender, Lloyds also faces pressure to reduce emissions linked to its own operations and financing activities.

Lloyds Bank ghg emissions profile and target 2025
Source: Lloyds Banking Group

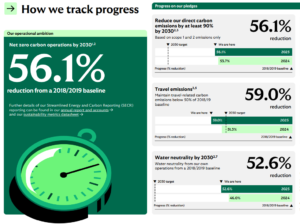
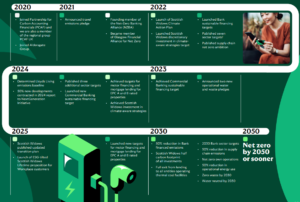
The bank has a target to achieve net-zero carbon operations by 2030. It also aims to cut its Scope 1 and 2 emissions by at least 90% by 2030 and reduce supply-chain Scope 3 emissions by 50%.

  • More importantly for a bank, Lloyds aims to reduce bank-financed emissions by more than 50% by 2030, on the path to net zero by 2050 or sooner.
Lloyds Bank net zero roadmap
Source: Lloyds Banking Group

The bank has also set sector-specific financed-emissions targets. These targets make the new £100 billion financing goal more significant. Lloyds will need to grow transition finance while also managing the emissions risks within its lending portfolio.

The £100B Question: Will the Finance Deliver Real Cuts?

The expansion of transition finance also creates a challenge. Not every loan labelled “transition” will automatically deliver meaningful emissions reductions. The quality of the underlying transition plan matters.

This is why Lloyds’ framework and measurement rules will be important. The bank says its transition approach includes client engagement, assessment of transition risks and opportunities, and greater use of data to support decisions. Its 2025 sustainability report also highlighted work with clients in sectors where emissions and transition risks are material.

The UK government has also stressed the need for high-integrity transition finance. Its Transition Finance Market Review called for instruments that can attract long-term capital while maintaining market confidence.

For Lloyds, the value of the £100 billion target depends on two things. First, how much money it helps to raise. Then, where that money goes and the environmental results it achieves.

A Bigger Role for Banks in the UK Transition

Lloyds’ new £100 billion sustainable and transition finance target marks a major expansion of its climate-finance ambitions. This plan helps the bank bring transition finance into its core target. The move also comes as the UK seeks more private capital for clean energy, energy efficiency and industrial decarbonisation.

For Lloyds, the opportunity is also commercial. Transitioning businesses need financing for new equipment, cleaner energy, efficiency upgrades and other investments. Yet, the bank also needs to show that its financing supports genuine progress rather than simply increasing the amount of capital labelled sustainable.

If Lloyds can combine its £100 billion financing goal with strong transition standards and measurable emissions results, the strategy could make the bank a larger force in both the UK’s financial sector and its wider path toward net zero.

The post Lloyds Sets £100B Sustainable Finance Target to Power the UK’s Net-Zero Shift appeared first on Carbon Credits.
Microsoft Cuts Carbon Removal Buying 80% as AI Emissions Put Climate Goals Under Pressure

Microsoft Cuts Carbon Removal Buying 80% as AI Emissions Put Climate Goals Under Pressure

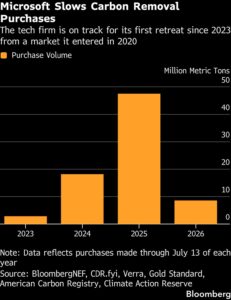
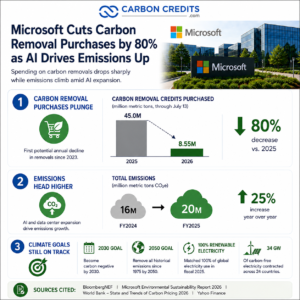
Microsoft is sharply reducing its carbon removal purchases this year as the company spends heavily to expand its artificial intelligence (AI) business. The tech giant purchased 8.55 million metric tons of carbon removal credits through mid-July 2026, about 80% less than it bought during the same period in 2025, according to BloombergNEF calculations. The drop could mark Microsoft’s first annual decline in carbon removal purchases since 2023.

The change comes as Microsoft’s emissions are moving in the opposite direction. The company’s latest sustainability report shows that total emissions rose 25% in fiscal 2025, driven mainly by the expansion of its data center network and growing electricity demand linked to AI.

The contrast highlights a growing challenge for technology companies: AI is driving rapid business growth, but it is also increasing the energy and emissions burden of building the infrastructure needed to support it.

Microsoft Pulls Back From Its Carbon Removal Buying Spree

Microsoft has been one of the world’s largest corporate buyers of carbon removal. In fiscal 2025, the company signed agreements covering a record 45 million metric tons of carbon dioxide removal with 21 companies. That was twice the volume contracted in fiscal 2024 and nine times the amount contracted in fiscal 2023.

The company has used these purchases to support a wide range of removal technologies. They include nature-based projects, biochar, carbon mineralization, and engineered carbon removal.

Microsoft says its carbon removal program is intended to help build a market for technologies that can remove carbon at scale. The latest reduction does not mean the company has abandoned carbon removal.

The tech firm continued to make purchases in 2026. In May, it agreed to buy 650,000 metric tons of carbon removal credits from BioCirc, even after reports that it had paused some new deals. That suggests a more selective approach rather than a complete exit.

Still, the decrease in its removal purchases this year ( as of July 13) compared to last year is massive, as shown in the chart below.

microsoft carbon removal purchases mid-2026

AI Growth Is Sending Microsoft’s Emissions Higher

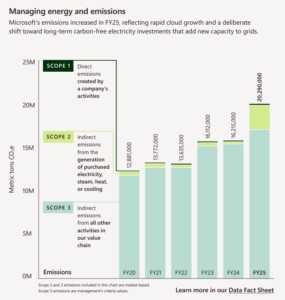
The change comes as Microsoft’s environmental footprint is growing. The company reported that its total Scope 1, 2 and 3 emissions increased 25% year over year in fiscal 2025. The company said the increase was driven mainly by the expansion of its data center infrastructure and its decision to stop using some non-additional, unbundled renewable energy certificates.

Microsoft’s total emissions reached about 20 million metric tons of CO2e in fiscal 2025, compared with about 16 million metric tons a year earlier.

The company also reported a major change in its emissions mix. Scope 2 emissions accounted for 13% of Microsoft’s total footprint in fiscal 2025, up from nearly 2% the previous year. The Windows developer said this reflects the growing role of electricity systems across its operations and supply chain.

Microsoft ghg emissions 2025
Source: Microsoft

Scope 3 remains the largest part of Microsoft’s overall footprint. This matters because AI services require large amounts of computing power. Expanding data centers means more servers, construction materials, electricity, and equipment across Microsoft’s supply chain.

Microsoft’s Carbon Goal Remains in Place

Despite increased emissions and reduced purchases so far this year, Microsoft has not abandoned its main climate target. The company aims to become carbon negative by 2030. It also aims to remove from the atmosphere by 2050 an amount of carbon equal to all the company’s direct and electricity-related emissions since its founding in 1975.

A spokesperson for the tech firm stated in response to Bloomberg News:

“Any adjustments we make are part of our disciplined approach, not a change in ambition.”

Microsoft’s 2026 sustainability report says the company matched 100% of its annual global electricity consumption with renewable energy in fiscal 2025. It also said it is expanding its focus on adding new carbon-free electricity to the grids where it operates.

The company has contracted 34 GW of carbon-free electricity across 24 countries, according to its sustainability reporting. These actions show that carbon removal is only one part of Microsoft’s climate strategy.

The company is also trying to reduce emissions from its operations, increase clean electricity supply, and cut emissions throughout its supply chain. 

Microsoft (MSFT) Stock Edges Higher

Microsoft (NASDAQ: MSFT) shares were up about 0.5% on August 13, after rising nearly 2% earlier in the session, according to a Yahoo Finance report. The modest gain came despite news of the sharp reduction in carbon removal purchases. This suggests that investors were paying more attention to Microsoft’s broader AI growth and spending plans than the carbon market development.

Microsoft MSFT stock

AI’s Emissions Problem Keeps Carbon Removal in the Mix

The reduction in purchases raises an important question: how will Microsoft deal with the emissions that it cannot eliminate quickly?

Carbon removal is designed for that part of the problem.

Microsoft’s original climate strategy called for cutting emissions by more than half by 2030 and using carbon removal to address the remainder. The company has said that its removal portfolio will include both nature-based and technology-based solutions.

But Microsoft’s own emissions data shows why the task is becoming harder. In fiscal 2024, the company said total emissions were already 23.4% above its 2020 baseline. At the same time, its energy use had increased 168%, while revenue had grown 71%.

The latest 25% year-over-year increase adds another challenge. If AI infrastructure continues to expand rapidly, Microsoft may need larger reductions elsewhere to stay on its 2030 path.

Microsoft carbon removal purchases down

Carbon Removal Enters a More Selective Market

Microsoft’s pullback comes as the wider carbon market is becoming more selective. The World Bank’s State and Trends of Carbon Pricing 2026 found that global carbon credit issuance increased 8% between 2024 and 2025. However, carbon credit prices declined slightly overall. Credits with strong ratings or high-integrity labels continued to receive premiums.

Future demand remains strong. Companies signed about $12 billion in offtake agreements for future carbon credits in 2025, three times the level recorded in 2024.

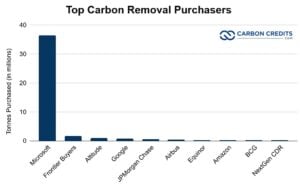
However, the market remains heavily dependent on a small number of large buyers. Microsoft has been the biggest driver of demand for carbon removal. Its purchasing decisions can therefore affect project developers, technology companies and investors across the sector.

Top 10 carbon removal purchases cdr.fyi data

A sustained reduction in Microsoft’s purchases could make it harder for early-stage carbon removal companies to secure long-term financing. At the same time, it could push the market toward projects that offer stronger evidence of permanent and measurable carbon removal.

AI Growth Is Raising the Stakes for Microsoft’s Climate Plan

Microsoft’s carbon removal pullback highlights a wider problem for the technology industry. AI is creating enormous demand for data centers and electricity. Companies are responding by building infrastructure at record speed. That growth can make it harder to reduce absolute emissions even when efficiency improves.

Microsoft has made major investments in clean electricity and carbon removal. It has also maintained its goal of becoming carbon negative by 2030. But its latest numbers show the scale of the challenge.

Emissions rose 25% in fiscal 2025, while carbon removal purchases through mid-July 2026 were down about 80% from the same period last year.

For Microsoft, the next phase will require more than buying carbon credits. It will depend on reducing emissions from data centers and suppliers while adding new clean electricity to the grids that power AI.
For the carbon removal industry, the shift is equally important. Microsoft remains a major buyer, but its latest move shows that future demand may depend less on volume and more on cost, quality, permanence, and measurable climate impact.

The post Microsoft Cuts Carbon Removal Buying 80% as AI Emissions Put Climate Goals Under Pressure appeared first on Carbon Credits.