NASA and DOE Sign Deal to Advance Space Nuclear Power: Can It Boost Clean Energy on Earth?

NASA and the U.S. Department of Energy (DOE) have signed an agreement to accelerate the development of nuclear power and propulsion technologies for future space missions. The partnership aims to help spacecraft travel farther, operate longer, and support a sustained human presence on the Moon.

The agreement, announced on October 8, 2026, establishes a framework for cooperation in nuclear research, fuel production, testing and mission development. It also supports U.S. efforts to strengthen its leadership in advanced nuclear technology.

The deal comes as electricity demand rises across the United States, driven by data centers, artificial intelligence, manufacturing and wider electrification. Although the agreement focuses on space exploration, advances in nuclear science and engineering could create opportunities for wider energy innovation.

NASA and DOE Team Up on Space Nuclear Technology

The partnership combines NASA’s space exploration expertise with DOE’s experience in nuclear science, reactor development, and fuel technology.

Nuclear power could help solve some of the biggest challenges facing deep-space missions. Solar panels become less effective when spacecraft travel far from the Sun or operate in areas with limited sunlight. On the Moon, long periods of darkness make solar power alone unreliable.

Nuclear systems can provide a steady source of energy for spacecraft, scientific equipment, and lunar facilities. They could also support advanced propulsion systems designed to improve future space travel.

The agreement covers two main technologies:

  • Nuclear fission: These systems generate energy by splitting atomic nuclei. They could power spacecraft, provide electricity to lunar bases, and support nuclear propulsion.
  • Radioisotope power systems: These convert heat from radioactive decay into electricity or provide heat to protect equipment in extremely cold environments.

By coordinating research, testing, and mission planning, NASA and DOE aim to move these technologies closer to practical use.

Space Reactor-1 and Lunar Reactor-1 Advance the Plans

One of NASA’s planned missions is Space Reactor-1 Freedom, which is scheduled for launch in 2028. The mission is expected to advance nuclear-powered space exploration and demonstrate technologies for future deep-space operations.

The agencies are also working toward Lunar Reactor-1, a planned fission power system intended to supply electricity to future lunar infrastructure. The U.S. objective is to have a lunar surface reactor ready for launch by 2030.

Reliable electricity will be essential for a long-term human presence on the Moon. Future facilities could need power for habitats, communications, scientific instruments, rovers, and equipment used to process local resources.

  • Nuclear power could help these systems operate through extended periods of darkness. It may also support future missions to Mars, where long distances and demanding conditions make reliable energy supplies important.
  • Radioisotope technology will remain another part of NASA’s plans. Its Dragonfly mission to Saturn’s moon Titan, scheduled for launch in 2028, will use a radioisotope generator to produce electricity and heater units to keep equipment warm.

NASA and DOE also plan to provide 24 radioisotope heater units for the European Space Agency’s Rosalind Franklin Mars rover.

Rising U.S. Electricity Demand Keeps Nuclear Power in Focus

Although the NASA-DOE agreement focuses on space, it comes as the United States faces growing electricity demand.

  • According to the U.S. Energy Information Administration (EIA), U.S. electricity generation reached approximately 4,430 billion kilowatt-hours in 2025, an increase of 2.8% from 2024. The agency expects generation to continue rising in 2026 and 2027.
  • The EIA’s September 2026 Short-Term Energy Outlook projects U.S. electricity sales of 4,135 billion kilowatt-hours in 2026 and 4,211 billion kilowatt-hours in 2027. These figures measure electricity sold to end users, rather than total generation.

Nuclear energy remains a major source of U.S. electricity. It supplied about 18% of utility-scale electricity generation in 2025, while fossil fuels accounted for approximately 58%.

The International Energy Agency (IEA), in its Electricity 2026 report, expects U.S. electricity demand to grow by close to 2% annually between 2026 and 2030. Data centers are expected to drive around half of the increase in U.S. electricity demand over this period.

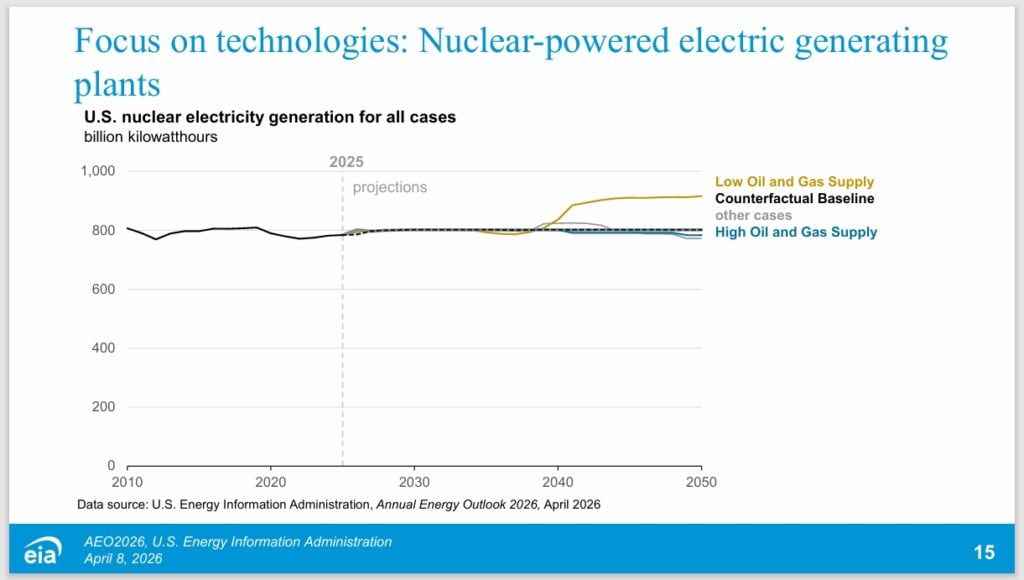
EIA electricity generation

These trends highlight the need for reliable electricity supplies. Nuclear plants can generate power around the clock, complementing variable sources such as wind and solar. However, meeting future demand will also require investment in renewable energy, storage, transmission networks, and other power sources.

The NASA-DOE agreement will not directly increase electricity generation on the U.S. grid. Instead, it focuses on developing nuclear technologies for space missions.

Could Space Nuclear Research Support Clean Energy?

Nuclear power is an important low-carbon energy source because reactors generate electricity without directly releasing carbon dioxide during operation. It could help reduce dependence on fossil fuels as electricity demand grows.

However, the benefits of the NASA-DOE agreement for clean energy on Earth will be indirect. Space reactors must meet different requirements from commercial nuclear power plants, so technologies developed for space cannot automatically be used in the electricity sector.

Still, the partnership could strengthen nuclear research, specialized fuel production, materials testing, and engineering capabilities. Some advances could eventually benefit other nuclear applications, depending on their technical and commercial suitability.

The agreement may also support workforce development and domestic supply chains for advanced nuclear technology. These capabilities could become valuable as the United States explores new ways to provide reliable, low-carbon energy.

Safety will remain essential. Nuclear systems used in space must meet strict requirements for fuel handling, reactor performance, launch integration, and reliable operation.

A New Frontier for Nuclear Innovation

The NASA-DOE partnership marks another step toward using nuclear technology to explore the Moon, Mars and beyond. Its immediate goal is to develop dependable power and propulsion systems for future missions.

At the same time, rising electricity demand is increasing the need for reliable, low-carbon energy sources in the United States. Nuclear power could help meet that need alongside renewables, energy storage and grid upgrades.

The agreement is not a direct clean-energy deployment program, and its broader benefits will depend on further research and testing. However, by advancing nuclear science and engineering, it could create opportunities that extend beyond space exploration.

In the long term, the partnership could help strengthen U.S. nuclear capabilities for both space missions and future energy innovation on Earth.

The post NASA and DOE Sign Deal to Advance Space Nuclear Power: Can It Boost Clean Energy on Earth? appeared first on Carbon Credits.

LEGO’s New Brick-by-Brick Climate Move: E-Methanol Replaces Fossil-Based Plastic

LEGO’s New Brick-by-Brick Climate Move: E-Methanol Replaces Fossil-Based Plastic

LEGO is turning to a renewable chemical to reduce its reliance on fossil fuels. The toy maker has started using e-methanol to help produce more than 90 types of plastic elements, including connectors, steering wheels, cross axles, and the hands of its famous minifigures.

The move marks a new step in LEGO’s effort to use more renewable and recycled materials. The company says the change follows more than five years of testing and work with suppliers to bring e-methanol into its manufacturing process.

The material offers an alternative to fossil-based ingredients used to make plastic. However, LEGO is not replacing all conventional plastic at once. The new material enters a shared production process where renewable and fossil-based sources are mixed.

The move comes as companies look for ways to cut emissions from materials that are difficult to replace. It also supports LEGO’s wider climate goals: cutting its total greenhouse gas emissions by 37% by 2032, compared with 2019, and reaching net zero by 2050.

LEGO Starts Using E-Methanol in More Than 90 Elements

LEGO’s new material is being used in more than 90 rigid and durable elements. These include small parts that connect pieces, steering wheels, cross axles, and minifigure hands.

These parts may be small, but making them requires plastic materials that meet strict safety and quality standards. LEGO products are made for repeated use. So, any new material needs to have the strength and durability LEGO demands.

The company noted in its release:

“This marks the latest step on our journey to increase the recycled and renewable materials we purchase to make Lego products, without compromising on safety, quality or durability.”

E-methanol gives LEGO another way to reduce its use of virgin fossil-based materials. Virgin fossil materials are made from newly extracted oil or gas rather than recycled or renewable sources. The company has not disclosed how many tonnes of e-methanol it will use, the share of each product made from it, or the expected emissions savings from this first rollout.

That makes the announcement an important manufacturing step, but not yet proof of a specific reduction in LEGO’s total emissions. The wider impact will depend on how quickly the company can increase its use of the material and how much fossil-based input it replaces.

From Renewable Power to Plastic: How E-Methanol Works

E-methanol is a form of methanol made using renewable electricity and captured carbon dioxide (CO₂). Methanol is a chemical used to make many products, including plastics and industrial materials.

The process begins with renewable electricity, which powers equipment that splits water to produce hydrogen. That hydrogen is then combined with captured CO₂ to make methanol.

LEGO’s e-methanol comes from the Kassø facility in southern Denmark. Developed by European Energy and operated with Japanese trading company Mitsui & Co., the plant began commercial production in 2025. The facility has an annual production capacity of 42,000 tonnes and runs on renewable energy. It uses CO₂ from a biogas facility as a key input.

The methanol can then be used to make plastic materials, replacing some of the fossil-based raw materials normally used in production. However, e-methanol is not the same as recycled plastic. It provides an alternative chemical feedstock, while recycling uses existing materials again. Both approaches can help reduce reliance on newly extracted fossil resources.

The climate benefits also depend on how the material is produced. Renewable electricity, the source of captured carbon, manufacturing emissions, and the amount of fossil-based material displaced all affect the final result.

LEGO e-methanol

A Shared Production System Helps Scale the Material

One challenge for LEGO is introducing new materials without disrupting its existing factories and supply chains. The company says its e-methanol enters a continuous production process where conventional fossil-based material is also present. This approach allows suppliers to increase the use of renewable inputs within existing production systems.

LEGO uses a method known as mass balance for some recycled and renewable materials. Under this system, suppliers mix certified renewable or recycled sources with conventional fossil-based inputs. They track the amounts entering and leaving the production system.

LEGO ghg emissions mass balanced
Source: LEGO

The approach can help companies increase the use of alternative raw materials without building an entirely separate manufacturing system.

However, it has an important limitation. LEGO cannot guarantee that each part has a specific minimum percentage of renewable or recycled material because the inputs are mixed. Instead, the company tracks the sources and quantities across the supply chain.

This distinction matters when assessing environmental claims. Using renewable feedstocks can reduce the need for fossil resources, but the exact benefit depends on the amount used and the accounting method.

LEGO says the e-methanol rollout is part of its wider effort to increase renewable and recycled materials without compromising product safety, quality, or durability. The toymaker is also using sustainable packaging materials and processes.

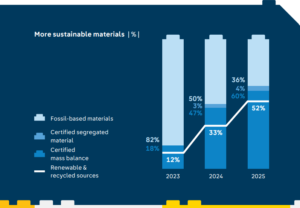
LEGO more sustainable materials
Source: LEGO

LEGO’s Material Shift Supports Its Climate Targets

LEGO has set a science-based target to cut its total greenhouse gas emissions by 37% by 2032, compared with a 2019 baseline. It also aims to reach net zero by 2050. The targets cover emissions from its operations and wider value chain, including suppliers.

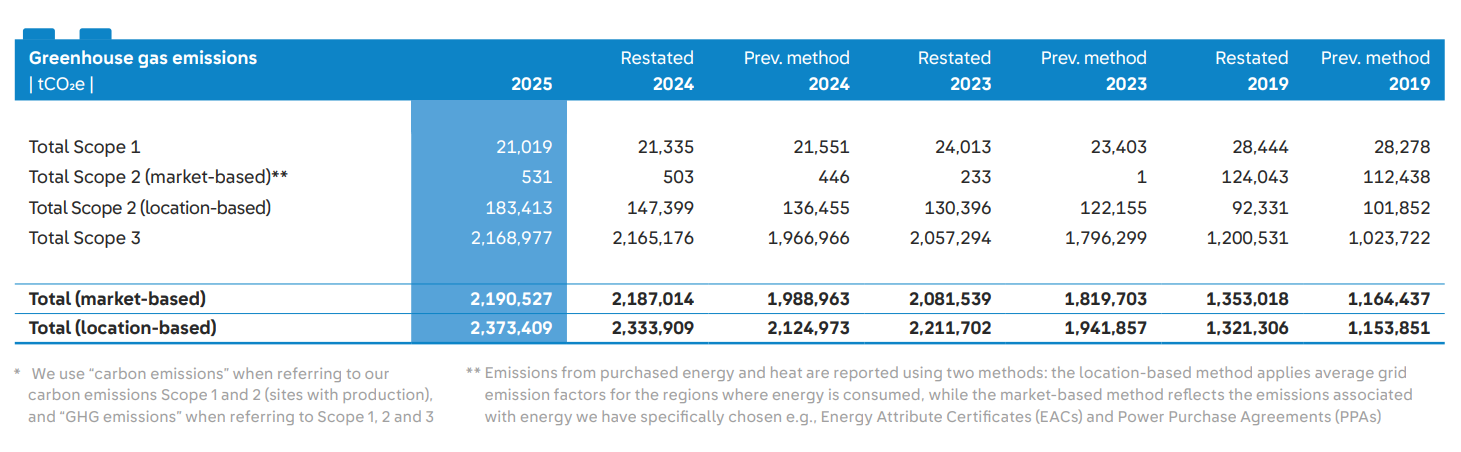
The latest figures show why further action is needed. LEGO reported 2.19 million tonnes of carbon dioxide equivalent (tCO₂e) in total greenhouse gas emissions in 2025. This is a small increase of 0.2% from 2024, based on its market-based reporting method. Most of these emissions came from its wider value chain, classified as Scope 3.

Scope 3 emissions include indirect emissions from activities such as producing purchased materials and transporting goods. These emissions can be harder to reduce because they occur outside a company’s direct control.

LEGO is working with suppliers to lower the impact of the materials it buys. It is also expanding renewable energy use at its factories and improving energy efficiency.

The company reported that 52% of the materials it purchased to make LEGO bricks and elements in 2025 came from recycled and renewable sources. These materials were used in more than 200 different elements, and around half of LEGO sets contained at least one such element. The figure relies largely on the mass-balance approach.

LEGO aims to keep raising that share by 2032, when the company celebrates its 100th anniversary. The e-methanol initiative adds another option alongside other renewable and recycled materials.

LEGO greenhouse gas emissions
Source: LEGO

E-Methanol Faces a Cost Gap as Global Methanol Output Tops 100 Million Tonnes

LEGO’s move reflects a wider effort to replace fossil-based chemicals with lower-carbon alternatives, but renewable methanol remains a small part of the overall market.

European Energy says more than 100 million tonnes of methanol are produced worldwide each year, mainly using natural gas and coal. The Kassø plant can produce 42,000 tonnes a year. This shows how limited current commercial e-methanol production is compared to traditional supply.

The International Renewable Energy Agency (IRENA) and the Methanol Institute have identified renewable methanol as a potential tool for cutting emissions in chemicals and transport. Their 2021 outlook said production costs were high and output was low. However, costs might decrease as technology and supply chains improve.

Current and future production costs of bio- and e-methanol
Source: IRENA

The International Energy Agency (IEA) has also warned that renewable fuel growth remains too slow to meet a net-zero pathway. The 2024 outlook predicts that e-fuel use must increase over ten times by 2030. This is necessary to meet the IEA’s Net Zero by 2050 Scenario. This applies to e-fuels broadly, not only e-methanol for plastics.

High production costs, the need for large amounts of renewable electricity, and limited supply remain major barriers. Companies also need clear ways to verify the source of materials and measure emissions savings.

For LEGO, the supply agreement offers access to a commercial source of e-methanol. Demand from manufacturers can boost investment in production capacity. However, the impact will depend on future contracts and prices.

Can Renewable Feedstocks Deliver Measurable Emissions Cuts?

LEGO’s e-methanol rollout will not immediately transform the materials used across its entire product range. The company has not yet announced the volume it will use or the emissions savings expected from the new material.

Still, the initiative shows how manufacturers can begin replacing fossil-based raw materials without redesigning every product or factory at once. The approach may also help suppliers gain experience with renewable feedstocks and improve production systems.

As LEGO works toward its 2032 emissions target and 2050 net-zero goal, e-methanol adds another tool to its materials strategy. Its long-term value will depend on scaling supply, reducing production costs, and proving that renewable inputs deliver measurable emissions cuts.

The post LEGO’s New Brick-by-Brick Climate Move: E-Methanol Replaces Fossil-Based Plastic appeared first on Carbon Credits.

South Korea Unveils $747 Billion Green Plan to Decarbonize Industry

South Korea Unveils $747 Billion Green Plan to Decarbonize Industry

South Korea has unveiled a 1,000 trillion won ($747 billion) green investment plan to cut emissions, expand clean energy, and help its industries compete in a lower-carbon economy.

The Korean Green Transformation Strategy, known as K-GX, will run from 2026 to 2035. Announced on October 7, 2026, it aims to support cleaner manufacturing, renewable energy, electric vehicles, and new climate technologies.

The government plans to mobilize 1,000 trillion won through public funding and policy-backed climate finance. It also expects a further 220 trillion won in private-sector investment for selected green projects. These are investment targets, not funds already spent.

South Korea’s Ministry of Climate, Energy and Environment said:

“This framework guarantees that South Korea will firmly adhere to its global carbon neutrality milestones while actively building domestic green jobs and securing the next generation of energy self-reliance.”

How South Korea Will Fund the Plan

South Korea wants to cut greenhouse gas emissions by 53% to 61% from 2018 levels by 2035 and reach carbon neutrality by 2050. The new plan is designed to support those goals while protecting the country’s manufacturing and export industries.

The government plans to combine public spending with loans, guarantees, and private investment. Its financing plan includes around 200 trillion won from government budgets and more than 790 trillion won in policy-backed climate finance. This financing aims to support clean energy infrastructure, industrial upgrades, and research into low-carbon technologies.

The government also wants private companies to invest another 220 trillion won in designated projects. Tax incentives, easier access to financing, and public-private partnerships are expected to help attract that money.

The goal is to help companies manage the high cost of changing how they make products. Many factories rely on fossil fuels, and replacing their equipment can take years and require major investment. However, the plan’s success will depend on how much funding reaches actual projects and whether those projects deliver measurable emissions cuts.

Five Industries Face Pressure to Cut Emissions

K-GX focuses on five major industrial groups:

  • steel,
  • petrochemicals,
  • cement,
  • semiconductors and displays, and
  • oil refining.

These industries support South Korea’s economy but can produce large amounts of greenhouse gases. Some also need very high temperatures or specialized industrial gases that are difficult to replace. The government plans to support cleaner production methods across these sectors.

In steelmaking, it aims to demonstrate hydrogen-based iron production at a scale of 30,000 tonnes by 2030. This technology uses hydrogen instead of coal to remove oxygen from iron ore.

Petrochemical and refining companies are expected to explore cleaner fuels, feedstocks, and electric equipment. Cement makers will focus on lower-carbon methods. At the same time, semiconductor and display manufacturers will find ways to cut emissions from industrial gases.

These changes could help South Korean manufacturers supply customers seeking lower-carbon products. But companies will need affordable clean electricity, reliable technology, and suitable infrastructure to make the transition.

South Korea Targets 100 GW of Renewable Power by 2030

South Korea aims to expand its renewable energy capacity to 100 gigawatts by 2030. Solar and wind power are expected to play major roles.

The government plans to upgrade the electricity grid. This will help it carry more renewable power from generation sites to factories and cities.

This is important because building solar and wind farms alone will not be enough. The country also needs transmission lines and other equipment to deliver that electricity where it is needed.

More renewable power could help manufacturers reduce emissions from their electricity use. It could also create opportunities for solar panel makers, wind developers, battery companies, and grid equipment suppliers. Still, meeting the target will depend on construction, permits, financing, and the speed of grid upgrades.

South Korea decarbonization

EVs and Hydrogen Vehicles to Gain Ground

South Korea wants electric and hydrogen-powered vehicles to account for more than 70% of new vehicle sales by 2035. The plan includes support for charging stations and cleaner transport. It also covers buses, rail, construction equipment, ports and ships.

The shift could support South Korean companies that make electric vehicles, batteries and charging equipment. It may also increase demand for better battery technology and related infrastructure.

The government has identified 10 priority green industries for support. These include electric vehicles, batteries, solar panels, wind power, small modular nuclear reactors, power equipment, power semiconductors, heat pumps, hydrogen and carbon capture.

It plans to support research and demonstration projects to help these technologies reach the market. However, growth will depend on costs, customer demand, and competition from other countries.

Can South Korea Cut Emissions Without Losing Industrial Ground?

South Korea’s climate targets require changes across its energy and manufacturing sectors. As a top ten global energy consumer reliant on coal for 33% of its power, the nation faces a steep climb to modernize its massive steel, semiconductor, and petrochemical industries.

Through new transition finance frameworks and stricter ESG reporting, the government aims to channel this capital into renewable energy, hydrogen tech, and low-carbon manufacturing. The ultimate goal is to help corporate giants slash emissions to hit South Korea’s aggressive climate targets: a 40% reduction by 2030 and full carbon neutrality by 2050.

2050 CARBON NEUTRAL STRATEGY South Korea
Source: UNFCCC
The transition will not be simple. Heavy industry depends on equipment that can operate for decades, and replacing it can be expensive. Companies will also need steady supplies of low-carbon energy. The K-GX strategy is intended to help meet those targets while supporting economic growth. 

The plan includes support for workers and regions affected by the shift away from high-emission industries. It also calls for stronger protection against climate risks for industrial sites and sectors such as shipbuilding and logistics.

These measures aim to make the transition easier for businesses and communities while encouraging companies to adopt cleaner technologies.

What the Plan Means for Green Investment

The strategy could create new demand for renewable power, grid upgrades, batteries, and low-carbon industrial equipment.

South Korea has also highlighted projects involving Hanwha Qcells, POSCO Holdings, LG Electronics, and Samsung Electronics. These companies presented projects linked to renewable energy, cleaner industry, and greener buildings at the strategy’s launch.

For investors, the $747 billion headline figure needs context. It represents planned financing to be mobilized over a decade, not a single government payment or guaranteed return.

Actual investment will depend on project approvals, company spending, and the ability of new technologies to compete on cost. Renewable energy growth needs better grid systems. Industrial upgrades must cut emissions effectively.

A Decade-Long Shift Toward a Lower-Carbon Economy

South Korea’s K-GX strategy sets out a 10-year plan to change how the country produces energy, manufactures goods, and moves people and products.

Its main goals are to:

  • Mobilize 1,000 trillion won in financing.
  • Attract 220 trillion won for private projects.
  • Reach 100 GW of renewable energy by 2030.
  • Make electric and hydrogen vehicles over 70% of new sales by 2035.

The plan supports South Korea’s wider target of cutting emissions by 53% to 61% from 2018 levels by 2035 and reaching carbon neutrality by 2050.

Whether it achieves these goals will depend on how quickly funding reaches projects, how much clean energy becomes available, and whether industries can adopt lower-carbon technologies at scale.

The post South Korea Unveils $747 Billion Green Plan to Decarbonize Industry appeared first on Carbon Credits.

UN Tightens Cookstove Carbon Credits With New Forest-Loss Reserve

UN Tightens Cookstove Carbon Credits With New Forest-Loss Reserve

The United Nations has introduced a new safeguard for clean cooking carbon credits. Projects under its Paris Agreement carbon market must now set aside some credits to cover the risk of forest carbon losses. Approved by the Article 6.4 Supervisory Body in October 2026, the rules apply to projects that help households burn less firewood or charcoal, or switch to cleaner cooking fuels.

Under the system, developers must place a share of their credits in a reserve pool instead of selling them all. The reserve covers the risk that trees saved through lower fuelwood use could later be lost to wildfires, drought, logging, or land clearing.

The change comes as clean cooking gains attention as a climate solution and a source of carbon market funding. However, cookstove credits have faced questions about how projects calculate emissions reductions and prove their climate benefits.

The new rules address the risk of losing forest-related benefits over time. They could also reduce the number of credits available for sale and affect project revenues. Mkhuthazi Steleki, Chair of the Supervisory Body, remarked:

“This decision gives cleaner cooking projects a new pathway under the UN carbon market, with clear rules to ensure that each credit represents a real and credible emission reduction. We have a clear mandate from Parties to build a high-integrity mechanism that supports the goals of the Paris Agreement. These methodologies put that mandate into practice, combining pathways for cleaner cooking projects with robust safeguards that support confidence in the mechanism.”

Two UN Methodologies Set New Rules for Clean Cooking

The UN approved two methodologies under Article 6.4, the Paris Agreement mechanism (PACM), for generating and trading carbon credits.

  • The first covers more efficient wood- and charcoal-burning cookstoves. These stoves use less fuel to prepare the same amount of food, potentially reducing emissions and pressure on forests.
  • The second covers projects that help households move to lower-emissions cooking options, including electricity and liquefied petroleum gas (LPG).

Both methodologies provide rules for measuring emissions reductions and calculating eligible credits. They also establish requirements for monitoring projects and assessing risks.

The methodologies matter because carbon credits can help finance the upfront costs of distributing cleaner cooking equipment. Revenue from credit sales can help expand projects. This is especially important in communities where families struggle to afford new stoves or fuels.

However, credits must represent genuine emissions reductions. If a project overestimates its benefits, it could issue more credits than its activities justify.

Paris Agreement Crediting Mechanism PACM

Why Cookstove Projects Need a Credit Reserve

The new reserve addresses the possibility that some climate benefits may not last. Using less firewood can reduce pressure on nearby forests. But the resulting forest benefits may be reversed if trees are later destroyed or cleared.

Under the UN rules, projects must contribute a portion of their credits to a common buffer pool. The pool acts as a safeguard against potential losses rather than allowing developers to sell every credit they generate.

The rules distinguish between natural and human-caused risks. Natural risks include events such as wildfires and drought. Human-caused risks include logging and land clearing.

The system uses scientific modelling to assess natural risks. It sets a default risk value for human-caused forest loss. Countries can reduce this value if they meet certain policy requirements.

The reserve does not mean every cookstove credit is expected to fail. Instead, it creates a financial and environmental safeguard against potential losses across projects.

However, the requirement could affect project economics. Developers may have fewer credits to sell, which could reduce revenue unless stronger credit integrity supports higher prices or attracts more buyers.

How Many Credits Must Projects Set Aside?

The reserve requirement varies according to risk and the conditions a project meets. For human-caused forest-loss risks, the rules establish a default reserve rate of 20%.

Countries can get reductions of up to two-thirds. To qualify, they need a forest emissions-reduction plan, a long-term climate strategy, and a REDD+ framework. REDD+ refers to efforts to reduce emissions from deforestation and forest degradation, alongside forest conservation and sustainable management.

A UN source told Climate Home News that improved cookstove projects might need a reserve of at least 9%. This is the case if all policy discounts are applied and risks are low. Projects in higher-risk areas or countries without the required frameworks could face larger deductions.

  • Consider a project that generates 100,000 credits. If its reserve requirement is 9%, it would set aside 9,000 credits and have 91,000 available for sale.

example of new UN PACM rule for cookstove carbon credits

At an illustrative price of $10 per credit, the 9,000 reserved credits would represent $90,000 in potential gross sales revenue. This is an example, not a reported market price, and excludes project costs. The actual financial impact will depend on each project’s reserve rate, credit volume, sale price, and operating costs.

Clean Cooking Has a Large Global Climate Impact

The rules target a major global energy and public-health challenge. The UNFCCC estimates that around 2.1 billion people still cook over open fires or use inefficient stoves and polluting fuels. These practices contribute to household air pollution, fuel consumption, and pressure on forests.

The World Health Organization estimated that household air pollution led to around 2.9 million deaths in 2021. This included over 309,000 deaths of children under five.

Cleaner cooking can help reduce these risks. More efficient stoves use less fuel. Electric cooking lowers household emissions if powered by low-carbon electricity.

The climate benefits depend on the technology, fuel mix, local conditions, and how projects calculate emissions reductions. Switching fuels won’t automatically cut emissions. Developers need to consider the emissions from alternative energy sources.

Carbon finance can help expand access to cleaner cooking equipment, especially where household budgets and infrastructure limit adoption. Projects need reliable monitoring. This shows that the equipment is used correctly and achieves the promised reductions.

UN new rules for cookstove carbon credits

Cookstove Credit Controversy Puts Integrity Under the Spotlight

The new rules arrive amid wider debate about the quality of cookstove credits. In February 2026, the UN issued its first credits under Article 6.4 for a clean-cooking project in Myanmar. The project distributes efficient cookstoves intended to reduce firewood use, household air pollution, and pressure on forests.

The issuance marked an important step for the new UN carbon market, but it also drew scrutiny from civil society groups. In October 2026, 130 civil society organizations urged a pause on issuing, transferring, and using credits from the Myanmar project. They want this action until an investigation is complete.

Their concerns are about:

  • The accuracy of emissions-reduction calculations,
  • Independent verification,
  • Human rights, and
  • Community safeguards.

Campaigners also cited earlier analyses that estimated the project overstated emissions reductions under previous carbon crediting rules. Some estimates showed over-crediting of about 14 times under the Clean Development Mechanism.

Under Article 6.4, the over-crediting was about seven times. These are estimates cited by campaigners, not established findings that should be treated as settled conclusions.

The controversy highlights a central challenge for carbon markets: credits must reflect reductions that can be measured and independently verified. Stricter rules on forest loss address one problem, but they don’t solve all issues. Concerns about project design, monitoring, and community effects remain.

What the New Rules Mean for Carbon Markets

The reserve adds a safeguard to the UN carbon market but may reduce project revenue by limiting the credits available for sale.

Buyers gain a clearer framework for managing forest-loss risks, while developers with lower reserve requirements can sell more credits. Countries may also be encouraged to strengthen forest protection policies to qualify for lower deductions.

However, the reserve does not resolve all concerns about over-crediting, monitoring, or community safeguards. Its effectiveness will depend on consistent enforcement, transparent reporting, and updated risk assessments.

The challenge is to strengthen carbon-credit integrity while keeping clean-cooking projects financially viable, particularly in lower-income communities that rely on carbon finance.

The post UN Tightens Cookstove Carbon Credits With New Forest-Loss Reserve appeared first on Carbon Credits.

Tesla (TSLA Stock) Turns to Arizona Desert Sun for Its Next Big Clean Energy Project

Tesla (TSLA Stock) Turns to Arizona Desert Sun for Its Next Big Clean Energy Project

Tesla is turning to the Arizona desert for a major new source of clean electricity. The project shows how the company is expanding beyond electric vehicles and growing its energy business. The project, called Sterling, is being built in Mohave County, Arizona. It will combine a large solar farm with a battery storage system. Energy company ContourGlobal is developing the facility, while Tesla has agreed to buy most of its expected electricity output.

The project will include 509 megawatts-peak (MWp) of solar capacity and a 360-megawatt battery system. It is expected to produce more than 1.1 terawatt-hours (TWh) of electricity each year when fully operational. Construction is underway, with completion planned for 2028.

Tesla has signed a long-term power purchase agreement (PPA) covering about 90% of the project’s expected electricity output. This deal gives Tesla access to a large supply of solar power without requiring it to own and operate the facility.

The project also shows why batteries are becoming important to the clean energy market. Solar panels produce electricity when the sun shines, while batteries store some of that power for use later in the day.

Inside Tesla’s New Arizona Solar Project

Project Sterling will cover more than 2,000 acres in the Mojave Desert, about 20 miles north of Lake Havasu City. It will include more than 760,000 solar panels and over 300 battery storage containers. The project has several key features:

  • Solar capacity: 509 MWp, equal to 450 megawatts of alternating-current output.
  • Battery power: 360 megawatts, with a total storage capacity of 1.4 gigawatt-hours (GWh).
  • Annual electricity: More than 1.1 TWh expected.
  • Construction jobs: An average of about 400 jobs during construction.
  • Target completion: 2028.

ContourGlobal will build, own, and operate the facility. Tesla will buy most of the electricity under its long-term agreement. According to ContourGlobal, the combined solar and battery system is designed to provide electricity for up to 16 hours a day. Actual supply will depend on sunlight, battery charging, operating conditions, and the terms of the power agreement.

Antonio Cammisecra, President & CEO of ContourGlobal,

“Arizona’s sun has been shining on this land for billions of years. Project Sterling will put it to work by turning sunlight into electricity and storing part of that energy for delivery after sunset. Today’s ceremony marks the visible beginning of our partnership with Mohave County, the State of Arizona, and our customer, Tesla. We are thrilled to celebrate this milestone with them and with the people who will now build this plant safely, with respect for the local community and the land of the Mojave Desert.”

The project will use lithium iron phosphate (LFP) batteries. This type of battery is widely used in large energy storage systems. The facility will also have liquid cooling and built-in fire protection.

ContourGlobal says Sterling is its largest renewable energy project worldwide and its largest power purchase agreement to date. A group of international banks is supporting the project’s financing through an equity bridge loan, a type of temporary financing used during project development and construction.

Why Tesla Needs Solar Power and Batteries 

Solar power has one major limit: it depends on sunlight. Panels produce electricity during the day, but output falls in the evening and can change with the weather.

Batteries help solve this problem. They store electricity when solar production is high and release it later when demand rises or sunlight fades. This makes solar power more useful for businesses that need electricity at different times of day. It can also help reduce exposure to changing electricity prices. However, the savings depend on market conditions and the terms of each power contract.

For Tesla, Project Sterling offers a long-term source of contracted clean electricity. The deal also shows how companies can support new renewable energy projects by agreeing to buy their power.

However, Tesla will not own the Sterling facility. ContourGlobal is responsible for building and running it, while Tesla is the main buyer under the power agreement.

The deal also does not mean all the electricity Tesla uses will come from renewable sources. The project’s wider impact will depend on how much power it delivers, when that power is used, and how Tesla accounts for its energy use.

Tesla arizona solar project sterling

Arizona’s Solar Boom Meets the Battery Storage Surge

Arizona is well suited to solar power because it receives abundant sunshine. The state already has a large solar industry, and projects that combine solar panels with batteries could help expand its role in the US energy market.

The Solar Energy Industries Association’s March 2026 state profile ranked Arizona third in residential solar capacity and fifth in utility-scale solar capacity. The state had nearly 9,800 solar jobs and attracted about $2.9 billion in solar investment during 2025, according to the association.

Large projects such as Sterling could add more renewable electricity to the region. Batteries may also help supply power when solar output drops, making it easier to use renewable energy at different times of day.

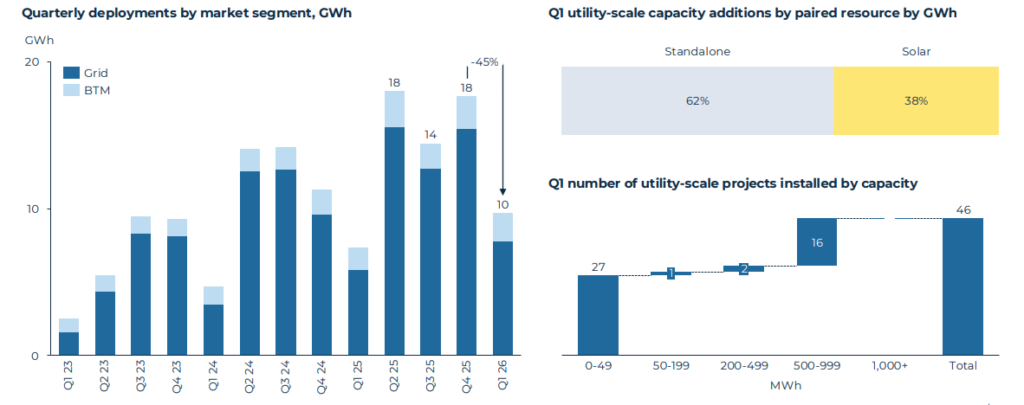
Energy storage is growing across the United States, too. The SEIA and Benchmark Mineral Intelligence reported that the country installed 9.7 GWh of energy storage in the first quarter of 2026, up 32% from the same period a year earlier.

US installed 9.7GWh of new BESS in Q1 2026, SEIA reports

The groups also forecast more than 610 GWh of total installed storage capacity by 2030. These figures cover the wider US market, not just Tesla projects. Still, they show how batteries are becoming a bigger part of the country’s energy system.

Beyond EVs: Tesla Builds Its Energy Business

Tesla is known mainly for electric vehicles, but energy storage is another important part of its business. Its products include Megapack, a large battery system for utilities and businesses, and Powerwall, which helps homes and smaller businesses store electricity.

tesla tsla ev delivery
Source: Tesla

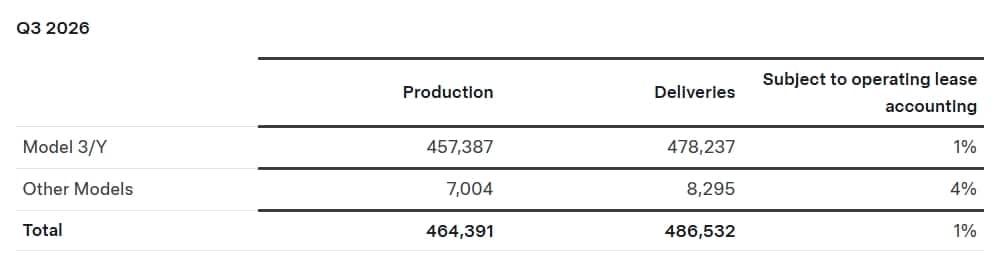
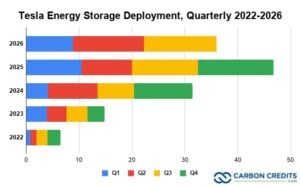
These products can help customers save power for later use, manage their electricity needs, and support the wider power grid. Tesla reported deploying 13.7 GWh of energy storage products in the third quarter of 2026. It also delivered 486,532 vehicles during the quarter. The company had scheduled the release of its full third-quarter financial results for October 21.

Tesla Energy Storage Deployment, Quarterly 2022-2026

Project Sterling is separate from those reported deployments because the facility is still being built. Once completed, it will add another large solar-and-battery project to the market in which Tesla operates.

The deal also shows that Tesla can expand its energy business by working with other companies. ContourGlobal will finance and run the facility, while Tesla will buy most of its electricity.

The project’s financial results will depend on the final cost, the amount of electricity delivered, and how well the facility performs. The companies have not disclosed the price Tesla will pay for the power.

Tesla Stock Shows Recent Gains Despite Volatility

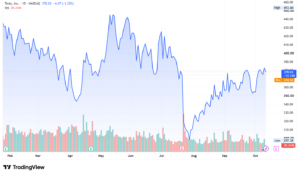
Tesla (TSLA) stock gained 2.05% on October 9, closing at $382.70, after rising from $375 on October 8. Despite the recent rebound, shares remain volatile as investors assess Tesla’s vehicle sales, autonomous-driving plans, and growth prospects.

Tesla TSLA stock

How the Project Could Help Cut Emissions

Solar panels generate electricity without directly burning fossil fuels. Batteries can store that electricity and release it later, which may reduce the need for power from coal or natural gas plants. However, the project’s total climate benefit will depend on which power sources its electricity replaces. Manufacturing solar panels and batteries, building the facility, and producing battery materials also create emissions.

The battery system is important because it allows some solar power to be used after the sun goes down. But batteries do not generate new electricity. They store power produced elsewhere, and some energy is lost when batteries charge and discharge.

The project’s actual emissions savings will therefore depend on how it operates and the wider electricity supply in the region. For Tesla, the agreement provides access to a large amount of contracted clean electricity. For Arizona, the project adds new solar and storage capacity and is expected to support hundreds of construction jobs.

A Bigger Role for Clean Energy

Project Sterling shows how solar power and battery storage can work together to supply electricity at different times of day. Its large capacity, long-term agreement with Tesla, and planned 2028 completion make it an important addition to Arizona’s clean energy pipeline.

For Tesla, the deal offers access to renewable electricity without the need to own the facility. For ContourGlobal, the agreement provides a major customer for its new solar-and-storage investment.

The project’s final climate and financial benefits will depend on how much electricity it delivers, how well the system operates, and which power sources it replaces. Still, projects that combine solar panels with large batteries are playing a growing role in the shift toward cleaner electricity.

The post Tesla (TSLA Stock) Turns to Arizona Desert Sun for Its Next Big Clean Energy Project appeared first on Carbon Credits.

Silver Supply Is Struggling to Keep Up: What It Means for Sierra Madre

Disseminated on behalf of Sierra Madre Gold & Silver Ltd.

Silver has posted five consecutive annual market deficits, but the bigger challenge may be how slowly mine supply can respond. With most silver produced as a byproduct of other metals, new primary production is difficult to bring online quickly. Sierra Madre Gold & Silver is taking a different route, expanding an existing Mexican operation while advancing another past-producing mine.

Silver’s supply problem is becoming increasingly hard to ignore.

Global mine production rose 3% to 846.6 million ounces in 2025, according to the World Silver Survey 2026. Recycling added another 197.6 million ounces, lifting total supply by 7%. Yet, total demand still reached 1.13 billion ounces, leaving the market with a 40.3-million-ounce deficit.
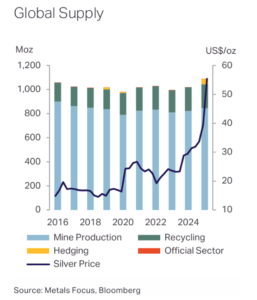
silver global supply

It was the fifth consecutive annual deficit. The Silver Institute and Metals Focus expect mine production to remain broadly flat in 2026, with the structural deficit widening to 46.3 million ounces.

The numbers point to a problem that cannot be solved simply by higher prices.

Silver production is unusually dependent on other metals. Roughly three-quarters of mine supply comes from byproduct production, meaning silver is recovered from mines primarily targeting copper, lead, zinc, or gold.

That limits how quickly the industry can respond when silver demand exceeds mine output.

For Sierra Madre, this creates a relevant backdrop. Rather than relying on a completely new mine to add future ounces, the company is expanding La Guitarra, an established Mexican operation, while advancing Del Toro, a past-producing silver complex.

The strategy highlights one potential part of the supply response: getting more production from assets that already have mining and processing infrastructure.

Silver Prices Can Rise Faster Than Mine Supply

The supply constraint is not simply a question of whether silver is valuable enough to mine. The industry needs time to translate higher prices into additional production.

The Silver Institute reported that the average silver price increased 42% in 2025, while mine production grew only 3%. Much of that mine-supply increase came from higher byproduct output from copper operations in Peru and the ramp-up of Polymetal JSC’s Prognoz mine in Russia. 
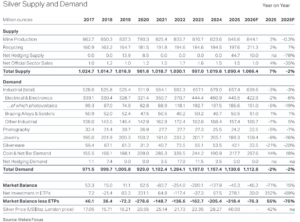
Silver Supply and Demand

That relationship is important. A higher silver price can improve the economics of primary silver projects, but it does not automatically cause copper, lead, or zinc mines to increase production. Their output decisions are driven primarily by the economics of their main metals.

New primary silver mines face another hurdle: development timelines.

Exploration must lead to a resource, followed by engineering, permitting, financing, construction, and commissioning. Even after construction, a mine needs sufficient grades and throughput to sustain commercial production.

That makes existing operations and past-producing assets relevant to the near-term supply picture. Sierra Madre’s La Guitarra complex is an example of that model.

La Guitarra Shows the Brownfield Approach

The company restarted commercial production at La Guitarra in January 2025, using an existing 500-tonnes-per-day mill. The property is fully permitted and includes underground mining operations in Mexico’s historic Silver Belt.

The company is now increasing capacity rather than building an entirely new processing operation. Its first expansion phase targets 750–800 tpd, while the second phase targets 1,200–1,500 tpd by Q3 2027.
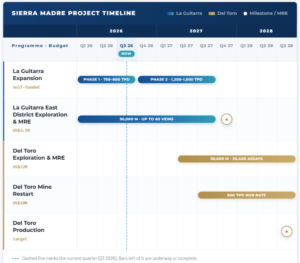
Sierra Madre Project Timeline

The expansion is already moving beyond the original configuration.

Sierra Madre reported in August that modifications to the existing mill and larger-capacity pumps had lifted daily throughput to as much as 672 tpd, a 34% increase over the previous 500-tpd level.

The company subsequently announced on September 28 that the plant had achieved throughput of up to 720 tpd on a steady basis as development at the Guitarra and Nazareno mines accelerated.

Those figures represent progress at an existing mine rather than supply from a newly constructed greenfield operation.

Greg Liller, Chief Operating Officer and Executive Chairman, commented, 

“We continue to advance our Phase 1 and Phase 2 expansions at Guitarra. With the new ball mill now installed, Sierra Madre has also accelerated underground development. We have started groundworks for the permitted dry stack tailings facility expansion, a key component of our Phase 2 plan to increase throughputs to 1,200 tpd to 1,500 tpd. We look forward to updating the market as we advance towards Phase 2 expansion.”

More Mill Capacity Requires More Mine Development

Expanding a processing plant is only one part of increasing silver supply. The mine must also deliver enough ore to keep that capacity utilized.

Sierra Madre is therefore advancing underground development alongside the mill expansion. Its recent work has focused on the Guitarra and Nazareno mines, with the company also developing the Coloso area.

The operating strategy is effectively being built from both ends: increase processing capacity while developing the underground workings needed to supply it. That distinction is important when assessing potential new supply.

A larger mill does not automatically mean proportionally more silver production. Actual output depends on ore availability, grades, recoveries, throughput, and operating performance.

For Sierra Madre, the objective is to turn existing infrastructure and underground resources into a larger operating base over time.

Del Toro Provides a Second Existing Asset

Sierra Madre is pursuing the same broad development philosophy with its second Mexican silver asset.

The company completed its acquisition of the Del Toro Silver Mine in Zacatecas on June 22, 2026, acquiring 100% of the operation from First Majestic Silver for consideration of up to US$60 million.

Del Toro is a past-producing underground silver-lead-zinc complex that First Majestic operated from 2013 to 2019. The property contains three underground mines, more than 62.5 kilometers of existing underground development and a 3,000-tpd processing facility. 

Sierra Madre also describes Del Toro as fully permitted, with access to power, water, roads, and an experienced local workforce. Those existing assets do not make a restart automatic.

Del Toro is currently on care and maintenance, and Sierra Madre still needs to complete additional exploration, resource work, mine planning, and restart activities before production can resume. But the starting point is different from a greenfield project.

The company is working with an established mining complex rather than developing an entirely new operation and processing plant.

Historical Production Gives Del Toro a Starting Point

Del Toro also has an operating history that provides context for its potential. First Majestic operated the complex between 2013 and 2019. Sierra Madre’s acquisition materials cite historical production averaging approximately 2.54 million silver-equivalent ounces per year between 2015 and 2018.

Sierra Madre’s initial plan is to restart Del Toro at approximately 800 tpd, with potential to increase throughput to 1,600 tpd. The company has targeted the start of the restart process for mid-2027, with production currently slated for mid-2028. These are company targets and remain subject to the work required to restart the operation.

Sierra Madre’s approach also includes additional exploration and resource modelling. Del Toro has an exploration database containing 631 drill holes totaling more than 137,000 metres, according to the company.

That existing geological information could help guide future work, although any new resource estimate will need to be established through additional technical work.

Why the Supply Structure Matters

The persistent deficit makes this distinction increasingly relevant.

The 2025 market was short 40.3 million ounces even after recycling contributed nearly 198 million ounces of supply. The Silver Institute expects mine production to remain broadly flat in 2026, with the deficit potentially reaching 46.3 million ounces.
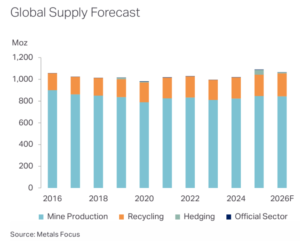
silver global supply forecast

At the same time, the industry’s dependence on byproduct production means that higher silver prices cannot necessarily produce an immediate wave of new mine supply. That leaves several potential sources of additional ounces:

  • Expansion of existing producing mines
  • Restart of past-producing operations
  • Development of advanced projects
  • New greenfield discoveries
  • Higher recycling

Each has different timelines and risks.

For the near term, established assets can potentially move through the development cycle faster than completely new discoveries because some of the required infrastructure and permitting framework may already exist.

La Guitarra and Del Toro fit into that category.

Sierra Madre Is Building Supply From Existing Assets

Sierra Madre is not large enough to change the global silver balance on its own. The significance of its strategy is different.

La Guitarra demonstrates how an existing mine can be restarted and expanded. Its processing capacity has moved from a historical 500 tpd configuration toward a planned 1,200–1,500 tpd operation, with throughput already reaching 720 tpd.

Del Toro provides another established asset, with three underground mines, more than 62.5 kilometers of development and a 3,000-tpd processing facility.

The broader silver market needs many such projects to advance if mine supply is to close the gap with demand. That is the central supply challenge.

Silver can move quickly in financial markets, but physical production moves much more slowly.

For Sierra Madre, the next stage is therefore about converting existing infrastructure into sustained additional output. For the wider market, the question is whether enough expansions, restarts and new projects can arrive quickly enough to narrow a deficit that has persisted for five consecutive years.

DISCLAIMER

New Era Publishing Inc. and/or CarbonCredits.com (“We” or “Us”) are not securities dealers or brokers, investment advisers, or financial advisers, and you should not rely on the information herein as investment advice. Sierra Madre Gold and Silver Ltd. (“Company”) made a one-time payment of $25,000 to provide marketing services for a term of one month. None of the owners, members, directors, or employees of New Era Publishing Inc. and/or CarbonCredits.com currently hold, or have any beneficial ownership in, any shares, stocks, or options of the companies mentioned.

This article is informational only and is solely for use by prospective investors in determining whether to seek additional information. It does not constitute an offer to sell or a solicitation of an offer to buy any securities. Examples that we provide of share price increases pertaining to a particular issuer from one referenced date to another represent arbitrarily chosen time periods and are no indication whatsoever of future stock prices for that issuer and are of no predictive value.

Our stock profiles are intended to highlight certain companies for your further investigation; they are not stock recommendations or an offer or sale of the referenced securities. The securities issued by the companies we profile should be considered high-risk; if you do invest despite these warnings, you may lose your entire investment. Please do your own research before investing, including reviewing the companies’ SEDAR+ and SEC filings, press releases, and risk disclosures.

It is our policy that information contained in this profile was provided by the company, extracted from SEDAR+ and SEC filings, company websites, and other publicly available sources. We believe the sources and information are accurate and reliable but we cannot guarantee them.

CAUTIONARY STATEMENT AND FORWARD-LOOKING INFORMATION

Certain statements contained in this news release may constitute “forward-looking information” within the meaning of applicable securities laws. Forward-looking information generally can be identified by words such as “anticipate,” “expect,” “estimate,” “forecast,” “plan,” and similar expressions suggesting future outcomes or events. Forward-looking information is based on current expectations of management; however, it is subject to known and unknown risks, uncertainties, and other factors that may cause actual results to differ materially from those anticipated.

These factors include, without limitation, statements relating to the Company’s exploration and development plans, the potential of its mineral projects, financing activities, regulatory approvals, market conditions, and future objectives. Forward-looking information involves numerous risks and uncertainties and actual results might differ materially from results suggested in any forward-looking information. These risks and uncertainties include, among other things, market volatility, the state of financial markets for the Company’s securities, fluctuations in commodity prices, operational challenges, and changes in business plans.

Forward-looking information is based on several key expectations and assumptions, including, without limitation, that the Company will continue with its stated business objectives and will be able to raise additional capital as required. Although management of the Company has attempted to identify important factors that could cause actual results to differ materially, there may be other factors that cause results not to be as anticipated, estimated, or intended.

There can be no assurance that such forward-looking information will prove to be accurate, as actual results and future events could differ materially. Accordingly, readers should not place undue reliance on forward-looking information. Additional information about risks and uncertainties is contained in the Company’s management’s discussion and analysis and annual information form for the year ended December 31, 2025, copies of which are available on SEDAR+ at www.sedarplus.ca.

The forward-looking information contained herein is expressly qualified in its entirety by this cautionary statement. Forward-looking information reflects management’s current beliefs and is based on information currently available to the Company. The forward-looking information is made as of the date of this news release, and the Company assumes no obligation to update or revise such information to reflect new events or circumstances except as may be required by applicable law.

For more information on the Company, investors should review the Company’s continuous disclosure filings available on SEDAR+ at www.sedarplus.ca.

Disclosure: Owners, members, directors, and employees of carboncredits.com have/may have stock or option positions in any of the companies mentioned: None.

Carboncredits.com receives compensation for this publication and has a business relationship with any company whose stock(s) is/are mentioned in this article.

Additional disclosure: This communication serves the sole purpose of adding value to the research process and is for information only. Please do your own due diligence. Every investment in securities mentioned in publications of carboncredits.com involves risks that could lead to a total loss of the invested capital.

Please read our Full RISKS and DISCLOSURE here.

The post Silver Supply Is Struggling to Keep Up: What It Means for Sierra Madre appeared first on Carbon Credits.
EnergyX Signs $2 Billion Lithium Supply Deal With Trafigura

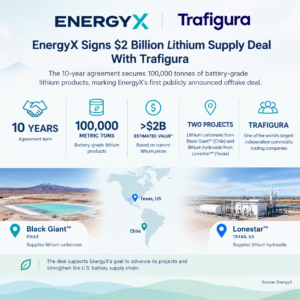
Energy Exploration Technologies, Inc or EnergyX, has signed a 10-year lithium supply agreement with global commodities trader Trafigura, securing a long-term buyer for products from its planned lithium projects in Chile and the United States.

The binding agreement covers 100,000 metric tons of battery-grade lithium products. Based on current lithium prices of approximately $20,000 per metric ton, EnergyX estimates the contract could generate more than $2 billion in revenue over its 10-year term.

Announced on October 13, 2026, the deal marks EnergyX’s first publicly disclosed commercial offtake agreement. It also gives the company a potential source of long-term sales revenue as it seeks financing to develop its lithium production facilities.

The agreement comes as demand for lithium-ion batteries expands beyond electric vehicles (EVs) to include grid-scale energy storage. However, EnergyX must still complete project development, secure sufficient financing, and bring its facilities into commercial production before it can fulfill the contract.

EnergyX to Supply Lithium From Chile and Texas

Under the agreement, EnergyX will supply battery-grade lithium carbonate from Project Black Giant in Chile and lithium hydroxide from Project Lonestar in Texas.

The contract follows a take-or-pay structure, under which Trafigura commits to purchasing agreed volumes under the terms of the contract. The arrangement provides a commercial framework for future sales, although the estimated $2 billion value depends on lithium prices and the contract’s pricing terms.

Trafigura will purchase an average of 10,000 metric tons of lithium products annually over the contract period, according to Reuters. This includes 5,000 metric tons each of lithium carbonate and lithium hydroxide per year.

The agreement also allocates a significant share of the projects’ planned initial production to Trafigura.

  • Project Black Giant, Chile: Trafigura will take 66% of the project’s Phase 1 output. EnergyX plans to produce 7,500 metric tons of lithium carbonate annually, with production targeted to begin in 2028.
  • Project Lonestar, Texas: Trafigura will purchase 30% of Phase 1 output. EnergyX plans to produce 15,000 metric tons of lithium hydroxide annually in Texas, with commercial production targeted for 2029.

The company is pursuing additional offtake agreements as it works toward securing commitments for 80% of planned production. Such agreements can help developers demonstrate market demand and strengthen their case when approaching lenders and investors.

Here’s the infographic that explains the key highlights of the deal:

energy X lithium trafigura

$690 Million US EXIM Financing in Focus

The Trafigura agreement could support EnergyX’s efforts to secure financing for its commercial lithium projects.

EnergyX has received a $690 million letter of intent from the US Export-Import Bank (EXIM Bank) for potential debt financing associated with Project Black Giant. An offtake agreement can help lenders assess future sales prospects, although it does not guarantee loan approval or the release of funds.

Additionally, the company has also secured a $225 million strategic investment from Italian energy company Eni for Project Black Giant, according to its announcement.

Together, the commercial agreement and financing initiatives are intended to advance EnergyX’s plans to develop lithium production capacity in the Americas.

“Offtake agreements are among the most important steps in taking a lithium project from development to production,” said Teague Egan, Founder and CEO of EnergyX. “A long-term purchase commitment from a counterparty of Trafigura’s scale and credit quality shows that the market wants EnergyX’s product. It also gives lenders and investors the revenue visibility they need before committing capital to commercial construction.”

The agreement is an important commercial milestone, but EnergyX still needs to fund, build, and commission its planned facilities. The timing and scale of future production will therefore be important to its ability to meet the contract.

Lithium Demand Forecast Points to Long-Term Growth

The deal comes amid changing demand patterns in the global lithium market. EV batteries remain a major source of consumption, while battery storage systems are becoming an increasingly important source of demand.

The International Energy Agency’s (IEA) Global Critical Minerals Outlook 2026 projects that lithium demand will more than triple by 2040 under its Stated Policies Scenario. Electric vehicles, battery storage, renewable energy, and electricity networks are major drivers of demand for critical minerals.

Battery storage is gaining importance as electricity grids accommodate more renewable power and data centers require additional electricity infrastructure.

  • Reuters reported in January 2026 that lithium demand from energy storage was expected to rise by 55% during the year, following growth of 71% in 2025, based on UBS data.

The report also highlighted forecasts of a potentially tighter lithium market in 2026, although analysts differed on the expected balance between supply and demand.

These trends could support long-term demand for battery-grade lithium chemicals. However, the market remains sensitive to EV sales, battery technology changes, new production capacity, and fluctuations in lithium prices.

Global Lithium Supply and Processing Capacity

Despite the demand outlook, the lithium industry has faced periods of oversupply and falling prices as new production has outpaced consumption. The market’s future balance will depend on how quickly demand grows relative to mine output, refining capacity, and recycling.

The IEA’s 2026 outlook suggests that the supply outlook for lithium has improved compared with earlier assessments as more projects enter the development pipeline. However, it also highlights an ongoing challenge: mining and refining capacity do not always develop at the same pace.

This distinction matters because lithium extracted from brines or mined from hard-rock deposits must be processed into chemicals that meet battery manufacturers’ specifications. Producing battery-grade lithium consistently at commercial scale can be more demanding than producing lower-grade material.

lithium battery market size

China remains central to this processing chain. Its established refining infrastructure gives it a major role in supplying lithium chemicals to battery manufacturers, while companies in the United States and other regions seek to develop alternative sources.

EnergyX aims to address part of this challenge through its direct lithium extraction (DLE) technology. The process is designed to extract lithium from brine without relying solely on conventional evaporation ponds. Its commercial performance will depend on factors such as recovery rates, operating costs, brine chemistry, and the ability to scale production reliably.

EnergyX Advances Direct Lithium Extraction Technology

Founded in 2018 by Teague Egan, EnergyX is developing lithium projects across North and South America. Its technology platform, GET-Lit, combines direct lithium extraction and refining processes intended to support lithium production from brine resources.

  • The company commissioned its Project Lonestar demonstration facility in Texas in 2026. The facility is designed to test its extraction technology using locally sourced brine from the Smackover formation, which extends across parts of the southern United States.
  • EnergyX is also advancing Project Black Giant in Chile, a planned 52,500-ton-per-year lithium project, according to the company’s announcement. Its other US operations include brine resources in Texas and Arkansas.

Commercial-scale production remains the next major step. Demonstration facilities can show whether a process works under operating conditions, but developers must still prove that the technology can deliver consistent output at the required scale and cost.

Daniel von Arx, Head of Battery Metals at Trafigura, said,

“We are pleased to support EnergyX as it develops its lithium projects in Chile and the US. Long-term offtake is an important step in moving projects into production, and this agreement reflects our ability to help bring strategic critical minerals projects online and build secure, diversified supply chains.

Drawing on our logistics network and market expertise, we look forward to supplying these battery-grade lithium products to customers, supporting supply chains for the US automotive and energy storage industries.”

What the Agreement Means for the Lithium Market

For EnergyX, the Trafigura deal provides a defined commercial route for future lithium production and may strengthen its efforts to secure project financing. For Trafigura, it offers access to planned lithium supplies from projects in two countries, with potential links to expanding battery and energy storage markets.

The agreement also reflects a broader effort to diversify lithium supply chains beyond established processing hubs. However, bringing new capacity online requires capital, reliable technology, regulatory approvals, and competitive production costs.

As battery demand expands, the market will need both additional lithium resources and enough processing capacity to convert them into battery-grade products. EnergyX’s progress will depend on whether it can translate its offtake commitment and technology development into commercially viable production.

The post EnergyX Signs $2 Billion Lithium Supply Deal With Trafigura appeared first on Carbon Credits.
Urenco and Thorizon Target Next-Gen Nuclear Fuel Markets as Uranium Demand Grows

Thorizon and Urenco have signed a memorandum of understanding (MoU) to explore cooperation on nuclear fuel for advanced molten salt reactors. The companies will assess how Urenco could supply enriched uranium and whether Thorizon’s future reactors could use depleted uranium, a by-product of the enrichment process.

The agreement could help Thorizon secure fuel for its planned reactors while allowing Urenco to expand its role in the advanced nuclear market.

The partnership comes as countries look to nuclear power for reliable, low-carbon electricity. However, the industry must address a key challenge: securing enough uranium and expanding the facilities needed to process it into reactor fuel.

What Thorizon and Urenco Bring to the Partnership

Thorizon is a European nuclear technology company developing molten salt reactors. The company is working on the Thorizon One, a reactor designed to produce electricity and industrial heat.

Unlike conventional reactors, which use solid fuel assemblies, molten salt reactors dissolve nuclear fuel in a liquid salt mixture. The salt also carries heat away from the reactor core.

Thorizon aims to develop a low-pressure reactor that could make better use of nuclear materials. However, the technology remains under development, and its commercial potential will depend on testing, licensing and successful deployment.

Urenco brings experience in uranium enrichment, a critical stage in the nuclear fuel cycle. The company operates enrichment facilities in Germany, the Netherlands, the United Kingdom and the United States.

Enrichment increases the concentration of uranium-235, the isotope used to sustain a nuclear chain reaction in most commercial reactors. Without the right fuel specifications, nuclear plants cannot operate as designed.

Under the MoU, the companies will explore several areas of cooperation:

  • Uranium enrichment: Urenco could support the supply of enriched uranium for Thorizon’s reactor programme.
  • HALEU supply: The companies will examine options for high-assay low-enriched uranium, or HALEU, used by certain advanced reactor designs.
  • Depleted uranium: They will investigate whether Thorizon’s technology could use this material as part of its fuel cycle.

The agreement is exploratory. It does not confirm a binding fuel supply contract or guarantee that Thorizon will use depleted uranium commercially.

HALEU and Depleted Uranium Could Play a Role

HALEU contains between 5% and 20% uranium-235. Conventional commercial reactors typically use uranium enriched to less than 5%.

Some advanced reactor designs need higher enrichment levels to meet their fuel and operating requirements. Thorizon plans to use HALEU in its molten salt reactor design, with the first reactors targeted for the mid-2030s.

Urenco is developing an Advanced Fuels Facility at Capenhurst in the UK, with HALEU production expected to begin in 2031. The proposed cooperation could help Thorizon explore a potential fuel supply route ahead of its planned deployment.

The companies will also study the possible use of depleted uranium.

Enrichment removes a portion of uranium-235 from natural uranium, leaving behind material with a lower concentration of that isotope. This leftover material, known as depleted uranium, consists mainly of uranium-238.

Some advanced reactor designs can use uranium-238 to produce fissile material through nuclear reactions. If Thorizon can establish a technically and commercially viable way to use depleted uranium, it could extract more value from existing nuclear materials and potentially reduce its reliance on newly mined uranium.

However, the outcome will depend on the reactor design, fuel chemistry, and technical validation.

Uranium Supply Struggles to Keep Pace With Demand

The proposed partnership comes as the nuclear industry prepares for higher fuel demand.

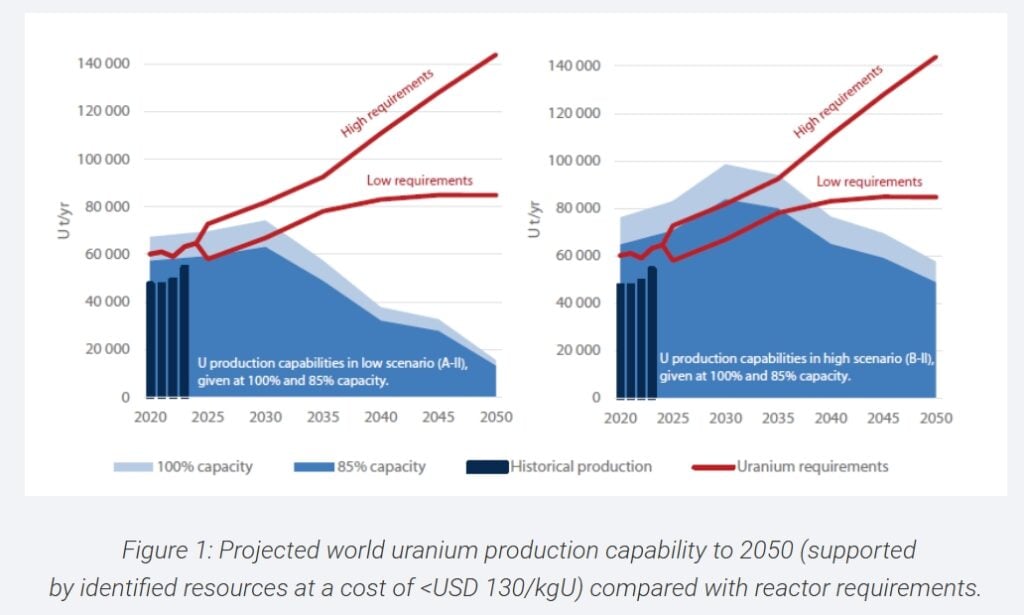
According to the World Nuclear Association (WNA), global nuclear reactors required an estimated 68,920 tonnes of uranium in 2025, while mines produced around 60,000 tonnes.

The difference highlights the industry’s reliance on inventories and secondary sources, including previously mined uranium, to meet reactor requirements.

Demand could rise further as countries extend existing reactor operations and build new nuclear plants. The WNA’s reference scenario projects annual uranium requirements could exceed 150,000 tonnes by 2040.

URANIUM
Source: NEA

Several factors could put pressure on future supply:

  • Growing nuclear capacity: New reactors and lifetime extensions will increase demand for nuclear fuel.
  • Long mining timelines: Uranium projects can take years to develop, permit, and bring into production.
  • Supply concentration: A relatively small number of countries account for much of global uranium production, making diversification important.
  • Processing constraints: Miners must supply uranium, but conversion, enrichment and fuel fabrication facilities must also keep pace with demand.

These challenges create opportunities for companies across the nuclear fuel cycle, from uranium miners to enrichment providers and advanced fuel developers.

Urenco Expands Its Enrichment Capacity

Urenco is investing in additional capacity to meet anticipated demand for enriched uranium.

On October 8, 2026, Urenco USA reported that it had started production in the sixth of eight planned new centrifuge cascades at its New Mexico facility. The expansion will add 700,000 separative work units (SWU) of annual enrichment capacity, with the final cascade expected in spring 2027.

Urenco also plans a further 2.1 million SWU expansion at the site, with initial production targeted for 2032.

These investments could help strengthen the fuel supply chain as conventional and advanced nuclear technologies compete for enrichment services.

For Thorizon, cooperation with an established supplier could help address one of the major hurdles facing new reactor designs: securing suitable fuel at the right time. For Urenco, the agreement provides a way to explore a potential role in the next generation of nuclear power.

The immediate outcome remains uncertain. The companies must still determine whether their proposed fuel arrangements are technically and commercially viable. But as uranium demand rises, partnerships that connect fuel suppliers with advanced reactor developers could become increasingly important.

The post Urenco and Thorizon Target Next-Gen Nuclear Fuel Markets as Uranium Demand Grows appeared first on Carbon Credits.
Korean Airlines Race for Carbon Credits as CORSIA Deadline Draws Closer

Korean Airlines Race for Carbon Credits as CORSIA Deadline Draws Closer

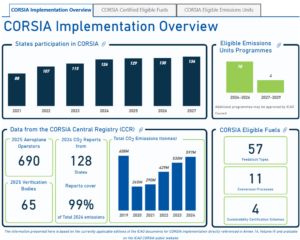
South Korean airlines are stepping up purchases of carbon credits as they face a growing compliance obligation under the International Civil Aviation Organization’s (ICAO) Carbon Offsetting and Reduction Scheme for International Aviation, or CORSIA.

The first compliance period covers 2024 through 2026, but airlines must secure and cancel the required eligible emissions units by the end of January 2028. With less than 16 months remaining, Korean carriers are moving to secure credits in a market where supply is already tightening.

Eastar Jet became the first South Korean airline to acquire CORSIA-eligible credits, purchasing 100,000 tonnes late last year. Trinity Airways, formerly T’way Air, followed in September 2026 with a purchase of 20,000 tonnes and plans to acquire more by the end of the year.

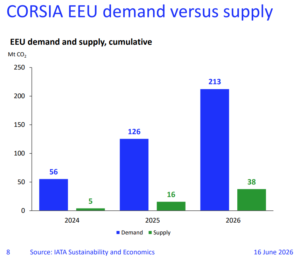
The moves highlight a broader challenge facing airlines worldwide: demand for CORSIA-eligible units is growing faster than authorized supply.

CORSIA’s First Compliance Test Is Getting Closer

CORSIA is the aviation industry’s global market-based system for addressing international flight emissions. Under the scheme, participating airlines must offset emissions above the applicable baseline by purchasing and cancelling eligible emissions units. The first phase covers 2024–2026, followed by the second phase from 2027–2035.

For 2024–2035, the CORSIA baseline is set at 85% of 2019 international aviation emissions. Any emissions above the applicable baseline create sector-wide offsetting requirements that are allocated among participating operators.

The compliance process is already underway.

Airlines must report their 2025 emissions during 2026. By November 30, 2026, states will use ICAO’s Sector’s Growth Factor to calculate each operator’s 2025 offsetting requirement. That makes 2026 a critical year for airlines to understand their eventual obligations and secure eligible units.

CORSIA implementation overview ICAO
Source: ICAO

Korean Airlines Face Millions of Tonnes of Credit Requirement

South Korea has eight airlines subject to its international aviation carbon law: Korean Air, Asiana Airlines, Jeju Air, Air Busan, Jin Air, T’way Air, Air Incheon and Air Seoul. Their potential exposure is significant.

For 2024, Korean carriers collectively had an estimated CORSIA offsetting requirement of about 2.75 million tonnes. Korean Air led with about 1.55 million tonnes. Asiana Airlines followed with around 706,430 tonnes, and Jeju Air had about 133,202 tonnes.

By July 2026, only Eastar Jet had secured credits. Its purchase of 100,000 tonnes was about 3.6% of the 2024 national airline requirement. Korean Air, Asiana and the other major carriers had yet to secure credits for that obligation, according to Korean reporting.

The final 2025 and 2026 requirements will depend on ICAO’s calculations and reported emissions. Therefore, the 2.75-million-tonne figure should not be treated as the final three-year requirement. Still, it shows the potential scale of the market.

Why CORSIA Credits Are Different From Standard Offsets

Airlines cannot simply buy any carbon credit and use it for CORSIA. ICAO maintains specific eligibility rules for emissions units. For the 2024–2026 first phase, eight programs are currently approved to supply eligible units, including:

  • American Carbon Registry,
  • Architecture for REDD+ Transactions,
  • Climate Action Reserve,
  • Global Carbon Council,
  • Gold Standard,
  • Isometric,
  • Thailand’s Premium VER Program, and
  • Verra’s Verified Carbon Standard.

Credits also face safeguards against double counting. Host countries may need to issue authorization confirming that emissions reductions used for CORSIA are not also counted toward their Paris Agreement climate targets. This is linked to the use of corresponding adjustments under Article 6.

This restricted eligibility makes the market smaller than the broader voluntary carbon market. It also helps explain why airlines cannot wait until the last minute to source credits.

CORSIA Supply Is Falling Behind Demand

The shortage is not limited to South Korea. The International Air Transport Association (IATA) estimates airlines will need to purchase and cancel more than 200 million CORSIA-eligible emissions units by January 2028 to meet requirements for the 2024–2026 first compliance period.

Yet, as of August 2026, only about 72 million emissions units were covered by 42 CORSIA-compatible Letters of Authorization issued by host countries. That leaves an estimated gap of roughly 150 million units that must be filled over the following 15 months.

CORSIA EEU demand versus supply
Source:

IATA said eligible supply is growing but remains well below the level needed. The available units are spread across Africa, Latin America and Asia-Pacific, with each region contributing a broadly similar volume.

The supply gap could put upward pressure on carbon prices as airlines move closer to the retirement deadline.

Korean Airlines Are Also Using SAF to Cut Obligations

Carbon credit purchases are only one part of the response. Airlines can also reduce their CORSIA obligations by lowering emissions through measures such as sustainable aviation fuel (SAF).

South Korea has been expanding its SAF market. The government plans to require 1% SAF blending for international flights departing Korea from 2027. The transport ministry estimated that this could reduce annual carbon emissions by about 160,000 tonnes, based on the country’s previous-year traffic volume.

Korean Air has already expanded its SAF use. In 2025, it began using domestically produced SAF on flights between Seoul and Japan. Its latest program applies a 1% SAF blend to selected flights between Incheon and Kobe and between Gimpo and Osaka through the end of 2026.

The SAF is made from used cooking oil and is CORSIA-certified. This drop-in fuel can therefore serve two purposes. It lowers the lifecycle emissions of flights and can reduce the number of carbon units an airline ultimately needs to purchase.

Korean Air Is Cutting Flight Emissions

Korean Air has also reported progress in reducing its direct flight emissions. The airline recorded 12.18 million tonnes of carbon emissions from aircraft operations in 2025, down from 12.60 million tonnes in 2024.

That represents a reduction of about 420,055 tonnes, or 3.3%, even though the number of flights increased approximately 2.6%.

The airline attributed the reduction to newer aircraft, optimized flight routes, improved fuel planning and more precise management of passenger, baggage and cargo weight.

Its newer aircraft fleet includes Boeing 787-9 and 787-10 aircraft, Airbus A350s and A321neos. Aircraft introduced since 2017 accounted for 41.6% of Korean Air’s total flights in 2025. These efficiency measures can help reduce both fuel consumption and future CORSIA exposure. 

Korean Airlines Are Also Using SAF to Cut Obligations

The Carbon Market Is Becoming an Aviation Cost

The Korean airline market shows how CORSIA is turning carbon emissions into a direct operating consideration.

The challenge is particularly significant because CORSIA credits must meet specific eligibility requirements. Airlines therefore compete for a relatively limited pool of units while international aviation demand continues to recover.

IATA estimates that over 200 million units will be needed by January 2028. In contrast, only about 72 million units have host-country authorizations as of August 2026. This shows a significant gap.

For Korean carriers, the next step is securing enough eligible units while continuing to reduce fuel use and adopt SAF. The market is already moving in that direction. Eastar Jet has secured 100,000 tonnes, while Trinity Airways has purchased 20,000 tonnes and plans further purchases.

For larger carriers such as Korean Air and Asiana, the potential requirement is substantially greater. As the January 2028 deadline approaches, CORSIA is therefore creating a new procurement market for airlines — one where access to eligible carbon units, SAF and lower-emission aircraft could directly affect compliance costs.

The Korean experience also reflects a broader global trend: as international aviation grows, carbon compliance is moving from a long-term sustainability issue toward an increasingly immediate financial and operational consideration.

The post Korean Airlines Race for Carbon Credits as CORSIA Deadline Draws Closer appeared first on Carbon Credits.