JPMorganChase Extends Climate Targets to 2035 and Expands Green Finance Rules

JPMorganChase Extends Climate Targets to 2035 and Expands Green Finance Rules
JPMorgan Chase is changing how it measures climate progress and green financing as global energy demand rises. The U.S. banking giant has updated its emissions targets, expanded the types of projects that count toward its green finance goal, and launched a new center focused on energy and the environment.

The changes reflect the bank’s view that cutting emissions must go hand in hand with reliable and affordable energy. Its updated approach includes financing for nuclear power, electricity grids and other low-carbon energy activities.

The bank also extended key climate targets from 2030 to 2035. It says the targets will help track progress across its lending portfolio, but they will not restrict its financing decisions.

The changes were announced on October 14, alongside the release of JPMorganChase’s 2025 Sustainability Report. They mark a broader approach to climate finance as artificial intelligence, manufacturing and electrification increase demand for power.

Heather Zichal, Head of the Center for Energy and the Environment and Global Head of Sustainability, said:

“Meeting energy demand while balancing affordability, security, reliability, and sustainability, what we call the ‘Four Forces,’ is one of the defining economic opportunities of our era.”

Oil, Power and Auto Sectors Get New 2035 Emissions-Intensity Targets

JPMorganChase first set portfolio-level emissions targets in 2021. These targets measure the carbon intensity linked to its financing in selected industries.

Carbon intensity measures emissions against a unit of business activity or output. Tracking it helps the bank assess how emissions linked to its lending change over time.

The bank has now updated its targets to align with the International Energy Agency’s 2025 Net Zero Emissions by 2050 scenario. The updated targets use 2035 as their target year rather than 2030. Three major changes stand out:

  • Oil and gas: The target is now a 47% reduction in carbon intensity by 2035, compared with the previous 45% reduction target by 2030.
  • Electric power: The target rises to a 79% reduction by 2035, from the previous 69% target by 2030.
  • Auto manufacturing: The target increases to a 65% reduction by 2035, compared with the previous 48% target by 2030.

These percentages refer to carbon intensity, not total emissions. They also do not mean the bank has already achieved these reductions. They are targets for measuring changes across its financing portfolio.
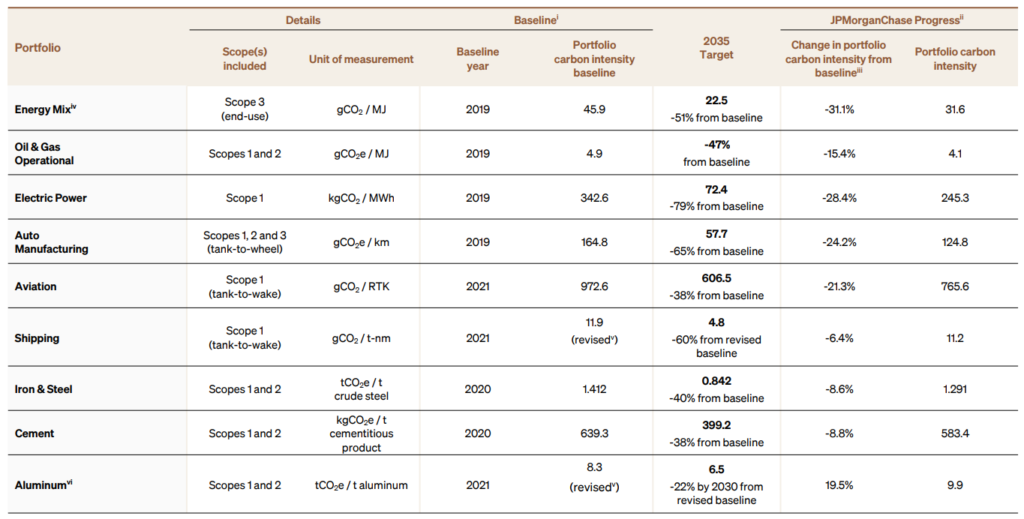
JPMorgan new climate targets 2035
Source: JPMorganChase

The bank also stresses that the IEA scenario is one possible path to reaching net zero, not a prediction of what will happen. JPMorganChase says its targets may change as technology, markets and available information develop.

Green Financing Now Includes Nuclear Power and Electricity Grids

JPMorganChase has also widened the types of activities that count toward the green objective of its $2.5 trillion Sustainable Development Target. The bank launched this 10-year goal in 2021. It aims to finance or help arrange more than $2.5 trillion for sustainable development by the end of 2030, including a $1 trillion green finance objective.

Under the new rules, eligible activities include:

  • Nuclear energy,
  • Electricity networks,
  • Grid upgrades,
  • Electric vehicle charging infrastructure, and
  • Zero- and low-carbon power generation at companies using various energy sources.

The change reflects the bank’s view that a cleaner energy system needs more than renewable power plants. Electricity grids need to link new energy sources to users. They must also provide reliable power to meet rising demand.

However, the expanded definition has an important effect on the reported figures. JPMorganChase applied the new eligibility rules to earlier years, too, allowing it to measure past financing under the updated system.

As a result, a higher green finance total does not necessarily mean the bank provided the same amount in new funding during that period. Some of the increase reflects activities that now qualify under the broader rules.

Bank Reports $520 Billion in Green Finance

JPMorganChase reported that it had financed or helped arrange $1.2 trillion toward its $2.5 trillion Sustainable Development Target by the end of 2025. Of that total, $520 billion counted toward its green finance objective.

  • The bank reported $217 billion in sustainable development financing during 2025, including $96 billion under the green objective.

The expanded eligibility rules contributed $145 billion to the reported green finance total. This is an important point when looking at the bank’s progress. The new figure includes financing that meets the new rules, not just new funding.

The green objective supports activities such as low-carbon energy, clean technology and projects that improve climate resilience. The bank says it has financed or helped arrange more than $500 billion in low-carbon energy since 2021. Its tax-focused investment team has also helped finance one in every four gigawatts of U.S. renewable energy and storage capacity, according to the bank.

These figures show the scale of JPMorganChase’s financing activity. However, money counted toward a green finance target is not the same as a measured reduction in greenhouse gas emissions. The actual climate impact depends on the projects financed and the results they deliver.
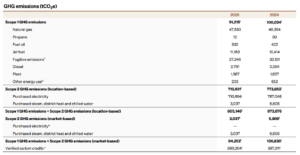
JPMorgan GHG emissions 2025
Sources: JPMorganChase

New Center Will Focus on Energy and Climate Challenges

Alongside the target changes, JPMorganChase launched its Center for Energy and the Environment (CE&E). The new center brings together the bank’s Center for Carbon Transition and its Corporate Sustainability functions. It aims to combine energy and climate expertise with policy knowledge and financial services.

The bank says this approach will help it identify barriers that money alone cannot solve. These include slow permit approvals, delays in connecting projects to electricity grids, worker shortages, supply chain problems, and uncertainty about future rules.

The center plans to work across businesses, policymakers and investors to help address these challenges. The bank has also placed greater emphasis on what it calls four forces: affordability, security, reliability and sustainability. It argues that energy investment must consider all four to support lasting progress.

This wider focus comes as power demand rises from data centers, artificial intelligence, manufacturing and electrification. JPMorganChase says it facilitates nearly $100 billion a year to help add new energy supply from different sources.

Emissions Targets Will Not Limit Lending

A major part of the updated strategy is the bank’s view that financed-emissions figures cannot tell the whole story. Financed emissions are greenhouse gas emissions linked to the activities of companies that a bank lends to or supports. These figures can track changes in a portfolio. However, the bank notes that gaps in data and different measurement methods can limit their usefulness for decisions on individual loans.
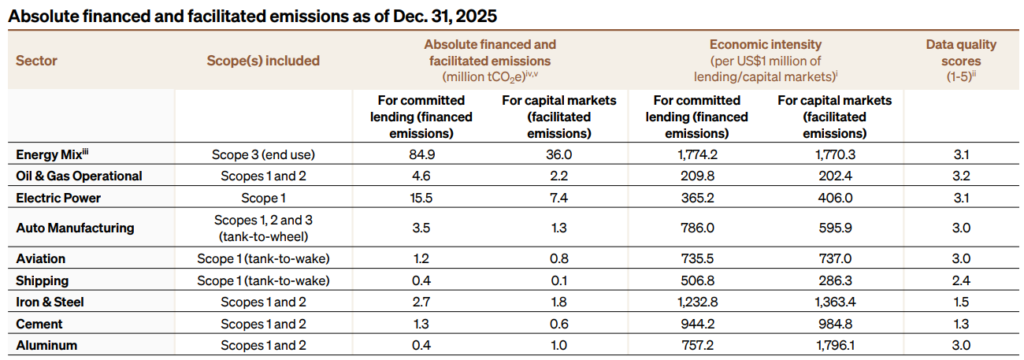
Absolute financed and facilitated emissions
Sources: JPMorganChase

JPMorganChase will continue using its climate targets to monitor trends and guide discussions with clients. However, it says the targets are not designed to restrict financing. This means the bank may continue to finance companies across different energy sectors while tracking how its portfolio’s carbon intensity changes.

The approach also reflects the bank’s focus on energy security and affordability. Nuclear power and grid upgrades might qualify for green finance rules. The bank sees them as key to a reliable, lower-carbon energy system.

The wider definition does not mean every activity at a company that uses fossil fuels automatically qualifies as green. Eligible activities must still meet the bank’s own criteria.

Will Broader Green Finance Deliver Measurable Climate Gains?

JPMorgan Chase’s new strategy focuses more on the capital it directs to energy projects. It also tracks emissions intensity closely.

The changes also make its green finance figures broader. This can help capture more low-carbon infrastructure types. However, readers need to tell the difference between new financing and amounts that qualify due to rule changes.

The bank’s approach also leaves open questions about how quickly its clients will cut emissions and how much the financing will contribute to real-world climate progress. Its updated targets provide a way to track portfolio trends through 2035, while the new center aims to address practical barriers to energy investment.

For investors and climate-market observers, the key measures to watch will be future financing totals, progress against the revised emissions-intensity targets, and evidence of actual emissions reductions. These will help show whether the broader strategy leads to changes beyond the way the bank reports its activities.

The post JPMorganChase Extends Climate Targets to 2035 and Expands Green Finance Rules appeared first on Carbon Credits.
TeraWulf (WULF) Stock: Can Low-Carbon Power Fuel Its AI Data Center Boom?

TeraWulf (WULF) Stock: Can Low-Carbon Power Fuel Its AI Data Center Boom?

TeraWulf Inc. (NASDAQ: WULF) is moving beyond Bitcoin mining to become a major provider of data center infrastructure for artificial intelligence (AI). A growing deal pipeline, including a long-term agreement with AI company Anthropic, has put the company in the spotlight as demand for computing power rises.

However, TeraWulf’s growth story is about more than AI. It also depends on access to electricity, the cost of running data centers, and the environmental impact of powering thousands of computer servers.

The company says its access to low- and zero-carbon power gives it an advantage as demand for AI infrastructure grows. Its reported energy mix supports that claim, but questions remain about future power needs, emissions, and the impact of new data centers on local communities.

For investors, the key question is whether TeraWulf can turn its energy strategy into a lasting business advantage while meeting its growth targets.

Anthropic Deal Puts TeraWulf’s AI Growth in Focus

TeraWulf’s move into AI infrastructure gained momentum in July 2026, when it announced a 20-year data center lease with Anthropic. The agreement covers about 401 megawatts (MW) of computing capacity at TeraWulf’s Justified Data Campus in Kentucky.

The company expects the first lease term to generate around $19 billion in contracted revenue. It could go up to about $33 billion if Anthropic chooses to extend for two five-year options.

  • Initial delivery is expected in the second half of 2027, with full delivery planned for early 2028.

The deal is a big step for TeraWulf. It shows their move from Bitcoin mining to high-performance computing (HPC). This shift includes systems used for AI and other tough tasks.

CEO Paul Prager has described the Anthropic agreement as only the beginning of a much larger market. In comments reported by Stocktwits, he pointed to rising demand for AI computing and limited access to ready-to-use power infrastructure.

This matters because building an AI data center requires more than computer chips. Operators also need reliable electricity, cooling systems, grid connections, and suitable sites.

TeraWulf is betting that its existing energy infrastructure and development experience will help it meet this demand. However, the $19 billion figure represents expected revenue over the lease term, not profit or cash already received. The company must still build and deliver the planned capacity.

Low-Carbon Power Could Support Its Competitive Position

Power is one of the highest costs and challenges for large data centers. As AI systems grow, operators need more electricity to run servers and cooling equipment. TeraWulf’s 2025 corporate sustainability report provides a useful look at its energy strategy.

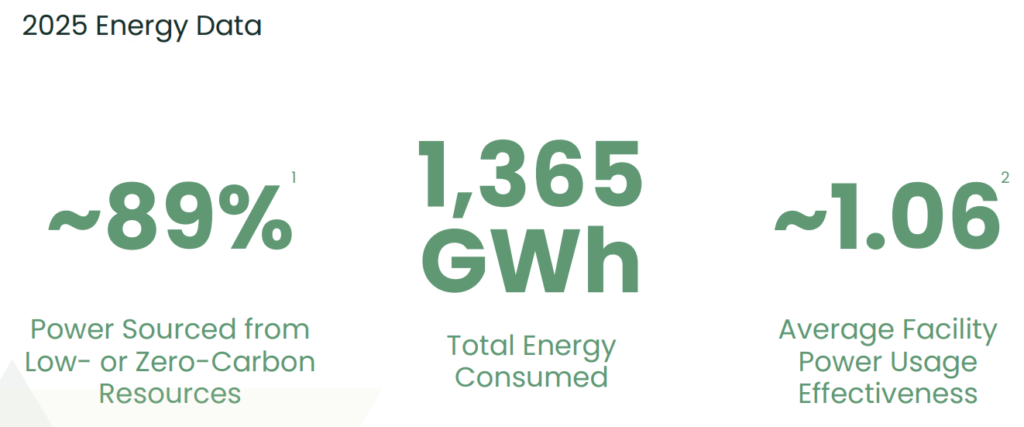
  • The company reported that about 89% of its power came from low- or zero-carbon resources in 2025. It also reported an average power usage effectiveness (PUE) of about 1.06 across its operations.
terawulf energy data
Source: TeraWulf

PUE measures how much total energy a data center uses compared with the energy delivered to its computing equipment. A score closer to 1.0 generally means less energy is spent on supporting systems, such as cooling and power distribution. These figures suggest that TeraWulf has access to relatively low-carbon electricity and operates its facilities with a focus on energy efficiency.

Its Lake Mariner campus in New York benefits from a grid with a large share of nuclear, hydropower, and wind generation. The site is on a former coal-fired power plant. This lets the company use existing industrial land and electrical systems.

This approach could help TeraWulf limit the need for new land development and reduce some of the challenges involved in connecting large facilities to the grid. Still, access to low-carbon electricity does not mean that data centers have no environmental impact.

Construction, equipment, backup power, and rising electricity demand all matter. The company’s reported power mix also does not, by itself, show its total greenhouse gas emissions.

AI Growth Brings New Energy and Emissions Questions

AI can help businesses improve efficiency, but running AI systems also requires large amounts of electricity. As more companies use advanced AI models, the demand for data center capacity is expected to grow.

  • This creates an important challenge for the industry: how to expand computing power without placing too much pressure on electricity supplies or increasing emissions.

The climate impact of an AI data center depends partly on where its electricity comes from. A facility powered mainly by low-carbon sources can have a lower electricity-related emissions footprint than one relying heavily on coal or natural gas.

However, even a relatively low-carbon data center can add pressure to the grid if it uses large amounts of electricity. More demand may require new generation, transmission lines, and other infrastructure.

TeraWulf’s energy strategy may ease some concerns. However, its future impact depends on the power sources available as its facilities grow.

Investors should also look at how the company reports energy use and emissions as it shifts from Bitcoin mining to AI computing. More detailed, comparable data would help show whether its environmental performance improves as the business grows.

WULF Stock Shows Signs of a Rebound, But What Should Investors Watch?

Terawulf WULF stock

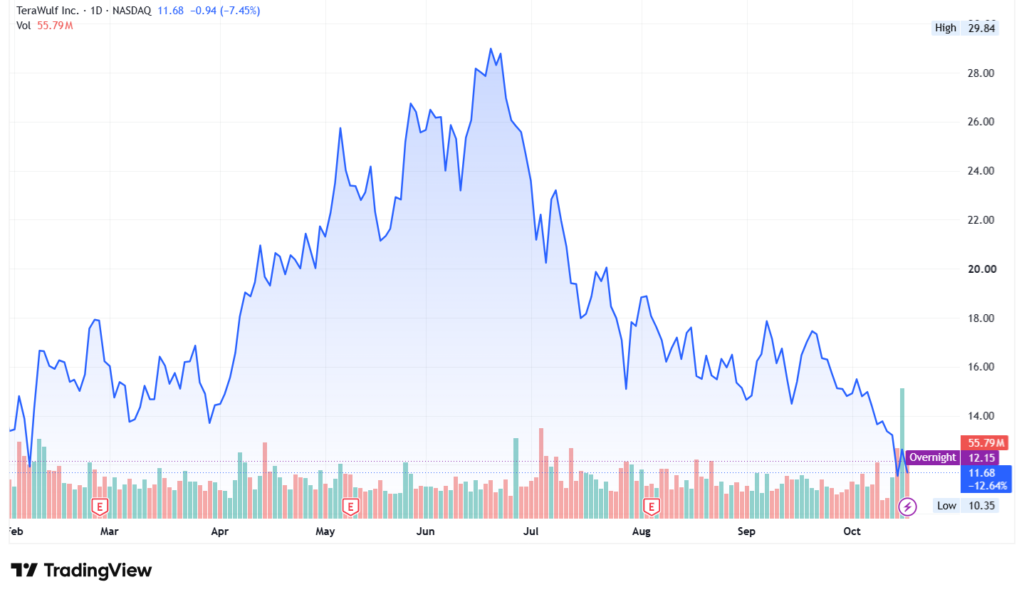
TeraWulf (WULF) stock closed down 7.45% at $11.68 on October 16, but rose 3.25% to $12.06 in overnight trading on October 18. The move offers a potential rebound after recent losses, though investors remain focused on the costs and execution risks of the company’s AI data center expansion.

The company’s AI strategy offers significant growth potential, but investors need to look beyond large contract values. TeraWulf reported second-quarter 2026 revenue of $44.8 million, including $31.9 million from HPC leases. That means HPC leasing accounted for about 71% of total revenue during the quarter.

As the business grows, investors will want to monitor:

  • How much new capacity is operational.
  • Whether projects stay on budget.
  • How quickly contracted revenue turns into cash flow.

Other important factors include financing costs, construction spending, customer commitments, and the risk of raising additional capital. Long-term leases can provide revenue visibility, but they do not remove the costs and execution risks involved in building large data centers.

The company’s energy strategy also deserves close attention. Low-carbon electricity and efficient cooling may help control operating costs and support customer demand. Investors should see if these benefits last as the company grows into new areas. Different power sources and grid conditions may affect this.

TeraWulf’s sustainability disclosures help investors see progress. Still, it’s important to look at the energy mix and efficiency figures along with total energy use, emissions, water use, and community impacts.

TeraWulf stock AI growth strategy

Can TeraWulf Combine AI Growth With Lower-Carbon Infrastructure?

TeraWulf is positioning itself to benefit from rising demand for AI computing. The Anthropic lease provides the company with a strong long-term commitment. Also, access to low-carbon power may help it compete in the energy-intensive industry.

But the opportunity comes with challenges. Building new capacity requires significant investment, and data centers face growing scrutiny over electricity demand, environmental impacts, and local costs.

For WULF shareholders, the key question is whether TeraWulf can achieve its expansion plans. They also want to know if the company can control costs and keep its energy advantages.

Low-carbon power could be a competitive strength, but long-term success will depend on execution, reliable energy supplies, and clear evidence that the company’s growth can be managed responsibly.

The post TeraWulf (WULF) Stock: Can Low-Carbon Power Fuel Its AI Data Center Boom? appeared first on Carbon Credits.

Global CO₂ Transport Industry to Reach $211 Billion by 2060, Wood Mackenzie Says

The global CO₂ transport industry could attract $211 billion in investment by 2060 as countries build more infrastructure to capture and store carbon emissions. A new analysis from Wood Mackenzie, published on October 14, estimates that the industry could transport 3 billion tonnes of carbon dioxide (CO₂) each year, including 200 million tonnes across international borders.

The forecast highlights the growing role of transport infrastructure in carbon capture, utilisation and storage (CCUS). Companies must do more than capture CO₂ from factories and industrial facilities. They also need pipelines or specialised ships to move the gas to locations where they can use it or store it underground.

As more carbon capture projects emerge, pipelines and CO₂ shipping networks could create investment opportunities across the energy and industrial sectors. However, transport costs, storage availability and government policies will shape the industry’s growth.

Asia Pacific to Drive CO₂ Transport Investment

Wood Mackenzie expects Asia Pacific to attract nearly 60% of global CO₂ transport investment through 2060, followed by North America and Europe.

The region faces a mismatch between industrial emissions and available storage sites. Japan, South Korea, Singapore and Taiwan could generate significant demand for CO₂ transport, while Australia, Indonesia and Malaysia could provide storage capacity.

  • By 2060, demand for cross-border CO₂ transport from Japan, South Korea, Singapore and Taiwan could reach 164 million tonnes per annum (Mtpa).
  • Australia and Southeast Asia could offer 187 Mtpa of storage capacity to meet this demand.

Japan illustrates the challenge. The country aims to store 120 million to 240 million tonnes of CO₂ annually by 2050. However, limited domestic storage options could force it to rely more heavily on overseas facilities.

Wood Mackenzie estimates that Japan may need to ship nearly 50 Mtpa of CO₂ to other countries. For comparison, Japan imports around 65 million tonnes of liquefied natural gas (LNG) annually.

Transporting CO₂ across borders could add about $40 per tonne, accounting for nearly 30% of the total levelised cost of carbon capture and storage (CCS) in some cases. These additional costs could influence project returns and determine which transport routes companies choose.

Pipelines to Account for More Than 80% of Investment

Wood Mackenzie expects pipelines to attract more than 80% of global CO₂ transport investment. Pipelines can connect industrial facilities to onshore and offshore storage sites and move large volumes of captured CO₂ through shared networks.

However, developers must spend heavily on pipeline construction, steel, and supporting facilities. Operators also need a steady supply of CO₂ to recover these costs. Permitting delays, land acquisition, and regulatory uncertainty can further increase expenses.

Companies could reduce these costs by converting suitable natural gas pipelines to transport CO₂. Wood Mackenzie estimates these conversions could cut capital expenditure by more than 60% and halve total transport costs.

However, developers cannot convert every existing gas pipeline. They must assess each pipeline’s technical condition, suitability and safety requirements before repurposing it.

Specialised ships offer another option, particularly when industrial facilities sit far from storage sites or across international waters. These vessels carry liquefied CO₂ between export terminals and storage hubs.

Wood Mackenzie highlights several factors that could influence transport costs:

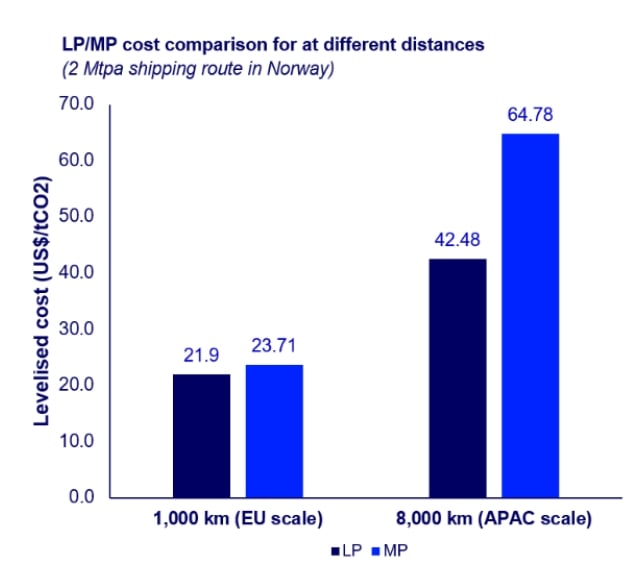
  • Pipeline and shipping costs can be comparable over distances of up to 1,000 kilometres, depending on project conditions and existing infrastructure.
  • Low-pressure CO₂ vessels could cut long-distance shipping costs by up to 34% compared with medium-pressure alternatives.
  • Fuel and electricity account for more than 50% of the levelised cost of CO₂ shipping.
  • In Japan, shipping could become more cost-effective than offshore pipelines for distances exceeding 400 kilometres at a transport volume of 5 Mtpa.

These figures show that companies must weigh transport distance, CO₂ volumes and infrastructure costs when selecting the most economical option.

global co2 transport
Source: Wood Mackenzie

Carbon Capture Needs Reliable Transport Networks

CCUS projects need an integrated system that connects industrial facilities, transport networks and storage sites.

Cement, steel and chemical producers could use carbon capture to reduce emissions from processes that are difficult to decarbonise. Companies can transport captured CO₂ to suitable geological formations and inject it underground for long-term storage.

However, building capture facilities alone will not guarantee that companies can transport and store CO₂ at the required scale. Limited pipeline capacity, insufficient shipping infrastructure, and delays in developing storage sites could restrict project operations.

This challenge could create opportunities for investors across several areas:

  • Pipeline construction and conversion
  • CO₂ liquefaction equipment and export terminals
  • Specialised CO₂ carriers and shipping services
  • Geological storage development and monitoring

Companies could also lower costs by connecting several industrial emitters to shared transport and storage networks. These hubs can spread infrastructure expenses across multiple customers and improve utilisation.

The climate benefits depend on how much CO₂ companies capture, the emissions generated during capture and transport, and the security of long-term storage. Transporting fossil-derived CO₂ for permanent storage can prevent emissions from entering the atmosphere, but it does not automatically qualify as carbon removal.

Policy Will Shape the Industry’s Growth

Governments must establish clear rules to support cross-border CO₂ transport. International projects need agreements that define transport standards, storage permits, long-term liability, and responsibility for monitoring stored carbon.

Wood Mackenzie identifies gaps in bilateral agreements, liability frameworks, and economic incentives as barriers to cross-border CCUS development. These issues matter particularly in Asia Pacific, where several countries could depend on international transport networks and overseas storage sites.

Governments will need to coordinate infrastructure planning and establish clear regulatory frameworks. Developers must also secure reliable access to storage facilities and enough committed CO₂ volumes before investing in large transport projects.

The projected $211 billion investment opportunity highlights the potential scale of the global CO₂ transport industry. Asia Pacific’s growing demand, the expected dominance of pipelines and the expansion of specialised shipping could shape the market over the coming decades.

Here’s another data from the IEA that highlights funding prospects:

IEA CCUS
Source: IEA

However, the forecast does not guarantee future investment. The industry will need commercially viable projects, sufficient storage capacity and supportive policies to move captured CO₂ efficiently from industrial facilities to permanent storage sites.

The post Global CO₂ Transport Industry to Reach $211 Billion by 2060, Wood Mackenzie Says appeared first on Carbon Credits.

COP31 Handbook Targets $20 Billion in Climate Finance for Vulnerable Countries

COP31 Handbook Targets $20 Billion in Climate Finance for Vulnerable Countries

Climate-vulnerable countries could gain access to US$20 billion in additional annual financing by 2030 through carbon markets. A new handbook aims to help them attract this climate funding ahead of the United Nations climate summit COP31.

Released on October 14, 2026, the Article 6 Senior Officials’ Handbook explains how governments can take part in international carbon markets. The Climate Vulnerable Forum and V20 Finance Ministers (CVF-V20) developed it with the Voluntary Carbon Markets Integrity Initiative (VCMI).

The initiative addresses a major funding gap. The 77 countries represented by the CVF-V20 face an estimated US$490 billion annual shortfall in financing for their climate plans. Carbon markets could provide another source of funding. But countries need clear rules, strong public institutions, and reliable safeguards to benefit.

The handbook offers practical advice to help governments make informed choices and attract investment. However, the US$20 billion figure is a potential opportunity, not guaranteed funding.

New Handbook Puts Carbon Finance on the COP31 Agenda

The handbook was released in Bangkok during the 2026 Annual Meetings of the World Bank Group and the International Monetary Fund. Its launch came about a month before COP31, which is scheduled for November 9–20 in Antalya, Türkiye.

The timing highlights a key challenge for climate action: countries need money to turn their climate plans into real projects. The United Nations Environment Programme has also stressed the need to improve access to climate finance and help communities facing serious climate risks.

Many developing countries struggle to attract investment, even when they have clear climate goals. They may lack the laws, technical skills, or project plans needed to secure funding.

Carbon markets could help close part of this gap. Countries can earn money by supporting projects that reduce or remove greenhouse gas emissions. These projects may include forest protection, renewable energy, and methane reduction.

However, governments must first decide which projects to support and how to manage carbon credit sales. The new handbook aims to help officials understand these choices before making deals.

How Article 6 Can Help Countries Raise Money

The handbook focuses on Article 6 of the Paris Agreement, which allows countries to work together to cut greenhouse gas emissions.

Article 6.2 allows countries to trade authorized emissions reductions through agreements with other countries. Article 6.4 sets up a United Nations-supervised system for issuing carbon credits under an international framework.

HOW A CARBON CREDIT REACHES DIFFERENT MARKETS
Source: CVF-V20 and VCMI Handbook

These rules can help countries attract foreign investment into climate projects. For example, a government can approve a project that cuts emissions. It can let some verified reductions be sold to a buyer in another country.

However, these transfers require careful accounting. Countries must follow approval and reporting rules and must also apply corresponding adjustments where required. These adjustments help prevent the same emissions reduction from being counted toward two countries’ climate targets.

Governments must also consider how selling carbon credits affects their own climate commitments, known as nationally determined contributions (NDCs). The handbook explains these choices and covers both Article 6.2 agreements and the Article 6.4 mechanism.

Sara Jane Ahmed, Managing Director and Finance Advisor of CVF-V20 Secretariat, remarked:

“This new handbook specifically responds to the needs of climate-vulnerable countries for specialised and tailored support and guidance on participating in carbon markets. By empowering climate-vulnerable member countries with informed leadership and institutional decision-making, this handbook can help build the policy environment needed to attract much-needed investments through Article 6 of the Paris Agreement.”

Eight Modules Guide Governments Through Carbon Market Rules

The handbook contains eight modules for senior government officials involved in carbon markets. It covers several important areas:

  • Project approval: Deciding which projects and emissions reductions can be approved for international transfer.
  • Revenue: Assessing how carbon markets could raise money for national climate plans.
  • Benefit-sharing: Deciding how project income and other benefits should be shared.
  • Environmental and social safeguards: Protecting communities and ensuring projects deliver real climate benefits.
  • Private investment: Creating conditions that encourage companies and investors to take part.
  • Laws and oversight: Setting rules and assigning responsibility for managing carbon markets.

The handbook also provides country examples and explains common challenges. Governments can use it as a checklist to identify missing rules, skills, or systems before entering the market.

This guidance matters because carbon markets involve more than selling credits. Governments must decide who can approve projects, how money will be managed, and how results will be measured. They also need clear rules to protect communities and ensure that projects deliver the benefits they promise.

UN handbook climate finance for vulnerable countries

Why Poor Countries Have Had Limited Access to Carbon Market Investment

The handbook addresses a long-standing problem: many climate-vulnerable countries have struggled to attract carbon market investment.

Forty-five least developed countries made up just 1.5% of projects registered under the Kyoto Protocol’s Clean Development Mechanism, according to the CVF-V20 and VCMI. This figure relates to an earlier carbon market system, not the entire market today. However, it shows how limited participation has been for many poorer countries.

Several barriers help explain this gap. Some countries lack the technical skills to develop projects or the laws needed to manage carbon credit sales. Others face high project costs or struggle to attract buyers.

The handbook aims to help governments address these problems. It encourages them to link carbon market plans with national development goals. This way, they won’t see credit sales as just a separate income source.

This could help direct investment toward clean energy, forest protection, and stronger local economies. But the guidance alone cannot guarantee funding. Countries still need credible projects that buyers are willing to support.

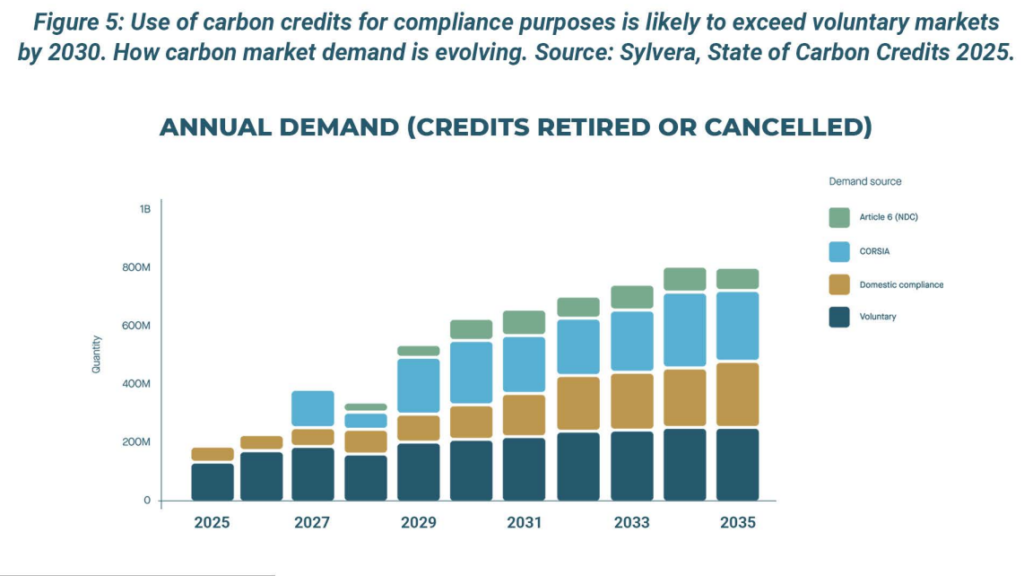
Figure 5 shows that market projections expect compliance demand to outpace voluntary markets over the next decade, a trend sparked first by CORSIA.

ANNUAL DEMAND (CREDITS RETIRED OR CANCELLED)
Source: CVF-V20 and VCMI Handbook

Ghana and the Philippines Show How Deals Can Work

The handbook highlights countries that are already exploring international carbon market cooperation. Ghana and Switzerland will work together to create 8 million tonnes of carbon credits. This effort is expected to bring in about US$300 million in carbon revenue and lead to US$1.1 billion in total investment.

These figures are projected outcomes. They do not mean that all the credits have been issued or that the revenue and investment have already been delivered.

The Philippines has also entered into bilateral carbon market agreements with Japan and Singapore, according to the handbook. These agreements can set the rules for transferring approved emissions reductions and support cooperation between governments.

Bhutan offers another example. It has established the Bhutan Climate Fund and a Carbon Market Information Platform. These tools aim to support funding for climate action and give stakeholders information about carbon market opportunities.

The examples show that countries can take different paths to enter international carbon markets, but results will vary. The amount of funding raised depends on the projects available, buyer demand, government approval rules, and the quality of the emissions reductions.

Can Stronger Rules Turn Carbon Credits Into Reliable Climate Funding?

Carbon markets could bring more money to vulnerable countries, but they also carry risks. Some projects may overstate how much carbon they prevent or remove. Others may fail to deliver promised benefits to local communities. Poor rules can also lead to disputes over who receives the money.

Moreover, governments must weigh the benefits of selling carbon credits against their own climate goals. Transferring emissions reductions to another country can attract investment, but it may also affect how the host country counts progress toward its NDC.

For host countries, fair benefit-sharing and public oversight can help ensure that carbon market income supports national priorities and local communities. The handbook gives officials a framework for managing these issues. However, it cannot replace strong laws, project checks, or long-term investment.

As COP31 approaches, the challenge is to turn better guidance into funded climate projects. The new handbook offers a starting point. Yet, its real value will depend on whether governments can use it to attract funding and deliver clear, measurable benefits for people and the climate.

The post COP31 Handbook Targets $20 Billion in Climate Finance for Vulnerable Countries appeared first on Carbon Credits.
China’s Farmland Could Remove 350 Million Tonnes of CO₂ a Year, Study Finds

China’s Farmland Could Remove 350 Million Tonnes of CO₂ a Year, Study Finds

New research suggests China’s farmland could become a major source of carbon removal using crushed rock. The technique, known as enhanced rock weathering (ERW), speeds up a natural process that removes carbon dioxide (CO₂) from the atmosphere.

A study published on October 10, 2026, examined the potential to spread basalt across Chinese croplands. The researchers estimated that a single year of application could remove 440 million to 790 million tonnes of CO₂ by 2100, depending on the modeled conditions.

Separately, another news report stated that sustained deployment could remove up to 350 million tonnes annually. These figures represent modeled potential, not carbon removal already being achieved at scale. 

The findings point to a possible new tool for China’s climate strategy. However, large-scale deployment will depend on costs, suitable farmland, environmental safeguards, and reliable measurement of the carbon removed.

How Basalt Speeds Up Nature’s Carbon Removal Process

ERW speeds up the natural weathering of rocks. Rainwater absorbs CO₂ and reacts with minerals as rocks break down. This process can turn carbon into dissolved bicarbonate, which may flow through rivers toward the ocean.

For ERW projects, developers grind rocks such as basalt into smaller particles and spread them over farmland. The extra surface area helps the minerals react faster with water and CO₂.

The method may also improve soil conditions. Basalt contains minerals that can supply nutrients, and weathering may help reduce soil acidity in suitable fields. But the amount of rock spread on farmland does not equal the amount of carbon removed.

Projects must account for emissions from mining, grinding, transport, and application. They must also measure how much carbon stays stored rather than returning to the atmosphere.

What the China Study Found

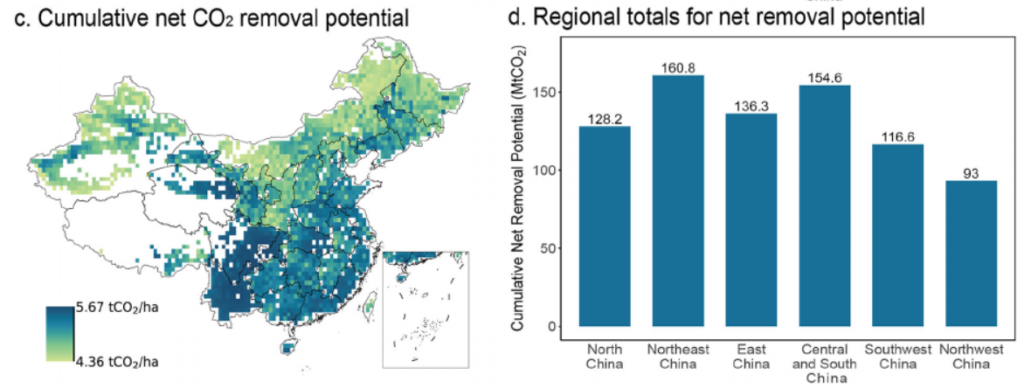
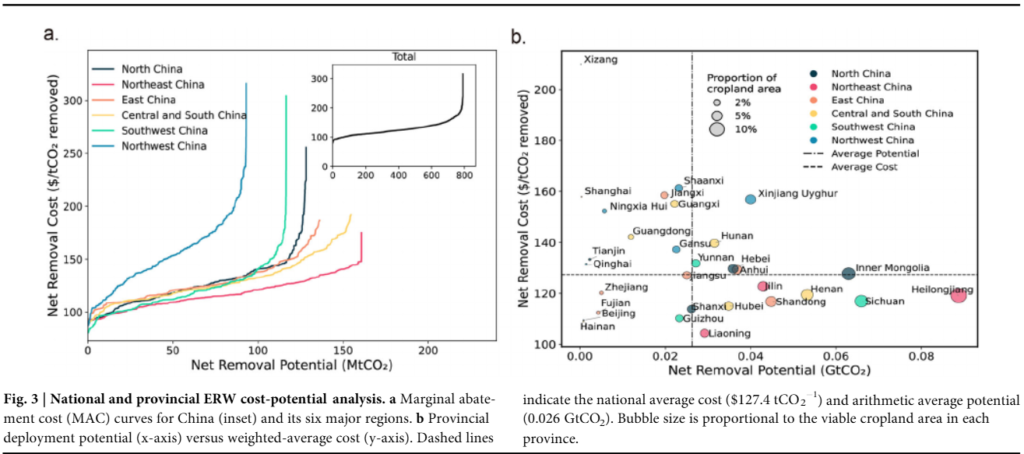
The research, by Zeyu Wang and Fei Teng of Tsinghua University and David M. Reiner of the University of Cambridge, assessed ERW potential and costs across China’s croplands.  The study estimated that a single year of basalt application could remove 440 million to 790 million tonnes of CO₂ by 2100. Its modeled net lifecycle cost ranged from US127 to US226 per tonne of CO₂ removed.

The researchers also assessed ERW’s possible contribution to China’s long-term climate goals. Under their modeled scenarios, the approach could meet 5% to 30% of the country’s negative-emissions needs by 2060.

Optimal ERW deployment in China under a basalt only scenario
Source: DOI:10.1038/s43247-026-04136-0

Northeast, Central-South, and East China emerged as priority areas for potential deployment. However, local conditions matter. Weathering rates depend on rainfall, temperature, soil chemistry, and rock type. The study therefore provides an initial national assessment, not a guarantee that every region can achieve the same results. 

China’s Agricultural Land Offers Scale

China has a large agricultural base on which to test the technology. Its official 2025 statistical communiqué reported 119.41 million hectares of sown grain area. This is not the same as the area suitable for ERW, but it illustrates the scale of the country’s farming system. 

Applying basalt to existing farmland could allow carbon removal to work alongside agricultural production. If the material improves soil quality or crop yields, those benefits could help make the process more attractive to farmers.

A 2023 study of farmland ERW in China reported an average crop-yield increase of 13.5%, with an uncertainty range of plus or minus 5.2%. It also modeled an annual national carbon removal potential of 280 million to 400 million tonnes. These are research findings, not guaranteed results for every crop or region. 

Field trials will be important for establishing where basalt works best, how much to apply, and whether the agricultural benefits justify the added costs.

High Costs Could Slow Deployment

ERW requires suitable rock to be sourced, crushed, and transported to farms. Grinding rock into smaller particles uses energy, while moving heavy material over long distances can increase costs and emissions.

The new study’s estimated cost of US$127–US$226 per tonne of CO₂ removed highlights a major challenge for commercial projects. Lower-emission electricity, efficient transport, and access to suitable rock could improve the economics.

National and provincial ERW cost potential analysis
Source: DOI:10.1038/s43247-026-04136-0

Using suitable industrial by-products may also reduce the need for new mining. However, materials must be screened carefully to ensure they contain appropriate minerals and do not introduce harmful contaminants into farmland.

Carbon accounting presents another challenge. Buyers need credible evidence that projects remove additional CO₂ and that the reported removals reflect the full supply chain. Because weathering rates vary, projects also need robust monitoring to estimate how much carbon is captured and retained.

Heavy Metals and Water Quality Require Careful Monitoring

Large-scale basalt application requires safeguards for soil, crops, and water. Some rocks contain potentially harmful elements, including chromium, nickel, zinc, or cadmium. Their presence and availability depend on the material and local conditions.

A 2026 study assessing rock resources in South China identified potential materials for ERW but emphasized the need to monitor environmental risks. It highlighted Fujian as a promising location for initial field trials. 

Researchers also need to track what happens after dissolved carbon leaves the soil. Some carbon may reach rivers and oceans, but the amount that remains stored depends on downstream chemical processes.

Careful selection of rock, appropriate application rates, and long-term monitoring will therefore be essential. These measures can help protect agricultural land while improving confidence in reported carbon removals.

Global ERW Market Shows Promise, But Costs Remain High

The global enhanced rock weathering market is growing as companies explore ways to remove CO₂ from the atmosphere. A September 2025 review in Nature Reviews Earth & Environment estimated that enhanced weathering could remove 0.5 billion to 2 billion tonnes of CO₂ annually by 2050. This is a technical potential estimate, not a forecast of confirmed removals.

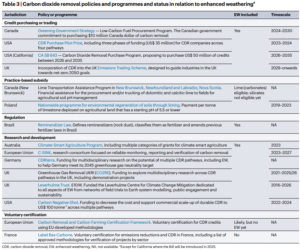
Corporate buyers are already signing deals with ERW developers. Frontier, a buyer group that funds carbon removal projects, reports 333,000 tonnes of enhanced-weathering removals contracted, worth US$121 million, across seven companies. Its listed average purchase price is US$362 per tonne, with prices ranging from US$270 to US$500. These figures cover contracted purchases, not removals already delivered.

Carbon dioxide removal policies and programmes
Source: https://doi.org/10.1038/s43017-025-00713-7

High prices and the difficulty of measuring carbon removal remain key barriers. Projects must prove how much CO₂ they remove, account for emissions from crushing and transporting rock, and monitor possible environmental risks. Lower costs and stronger measurement methods will be essential for ERW to grow from an emerging carbon-removal approach into a larger global market.

Can ERW Become a Scalable Carbon Removal Market?

China’s ERW potential adds another option to the growing range of carbon-removal approaches. The technology could interest buyers seeking measurable removals, particularly if projects can demonstrate strong monitoring and reliable net climate benefits.

However, the market opportunity remains tied to cost and proof. The headline figure of 350 million tonnes of CO₂ per year is a potential scenario, not a current supply estimate. Projects would need to show how much carbon they remove after accounting for emissions from rock processing and transport.

For China, the next steps include field testing, identifying suitable regions, improving measurement methods, and assessing environmental impacts. These efforts could help establish where ERW offers the strongest combination of carbon removal, agricultural value, and cost efficiency.

If those challenges can be addressed, enhanced rock weathering could support China’s wider climate strategy. It would still complement—not replace—direct reductions in fossil-fuel emissions.

The post China’s Farmland Could Remove 350 Million Tonnes of CO₂ a Year, Study Finds appeared first on Carbon Credits.
Indonesia Sets New Rules for Farm Carbon Credits and Farmer Benefits

Indonesia Sets New Rules for Farm Carbon Credits and Farmer Benefits

Indonesia has introduced new rules for carbon credit projects in farming. The regulation requires businesses to work with farmer groups and agree on how to share the benefits from these projects. It covers rice farming, livestock and plantations.

The new rule explains how agricultural projects can earn carbon credits, how emissions cuts must be checked, and how farmers should take part. The Indonesian Ministry of Agriculture issued Minister of Agriculture Regulation No. 18 of 2026 on October 6. It was published on October 12 and is set to take effect three months later.

The rules come as Indonesia builds its wider carbon market. Its national carbon exchange had recorded more than 1.6 million tonnes of carbon credits traded by July 2025, with a total transaction value of about US$4.7 million. More than 100 organizations had registered to use the exchange.

The new agricultural rules aim to give farming projects a clearer path into this market while setting conditions for farmer participation and benefit-sharing.

Opening Carbon Trading for Rice, Livestock and Plantations

The new regulation covers three main parts of agriculture: rice farming, livestock and plantations. Projects can earn carbon credits by cutting greenhouse gas emissions or storing more carbon in soil and plants.

Possible activities include changing how rice fields are watered, using lower-emission crop varieties, applying the right amount of fertilizer and improving the handling of crop waste and animal waste.

Other options include improving soil health, planting trees and other long-living crops, restoring damaged farmland and using farming methods that protect the soil. These activities can help reduce emissions or store more carbon. For example, changing how rice fields are watered can lower methane emissions. Better soil management can also help keep carbon in the ground.

Businesses, government agencies and farmer groups may take part in these projects. The rules explain how they can work together to reduce emissions and support Indonesia’s climate goals.

Businesses Must Agree to Share Benefits With Farmers

One of the most important parts of the regulation is its requirement for businesses to work with farmer groups.

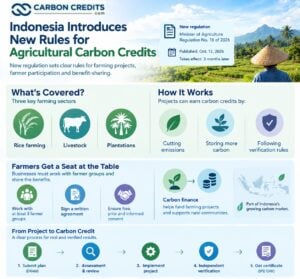
Under Article 4, businesses involved in agricultural carbon trading must work with at least three farmer organizations near the project site. The number and choice of groups must consider factors such as the size of the business’s land area and its operations.

The business and the farmer groups must sign a written agreement. It must explain what each side will do, how benefits will be shared and how long the agreement will last. Farmers must also give free, prior and informed consent. In simple terms, they must receive clear information and agree to take part without pressure.

The regulation does not set one fixed percentage of carbon revenue for farmers. Instead, the share must consider several factors, including:

  • Cost of technology,
  • Size of the land or business,
  • Amount of emissions reduced, and
  • Number of carbon credits generated.

This means the benefit-sharing arrangement can differ from one project to another.

Farmer groups can also run carbon credit projects themselves through a cooperative or another business. They may also work with outside partners that provide funding, as long as the parties agree on how to share the benefits.

The rules give farmer groups a formal role in carbon projects. They are not simply expected to provide land or help carry out farming activities.Indonesia’s Agricultural Carbon Credits Guide

Projects Must Prove Their Emissions Cuts

The regulation sets out steps that projects must follow before they can receive carbon credit approval.

Businesses using Indonesia’s national certification system must first submit a project plan called a Climate Change Mitigation Action Design Document, or DRAM. This document explains what the project will do, how it will reduce emissions and how the results will be measured.

The plan must go through an assessment and independent review. Once the project has carried out its activities, an independent verifier must check the reported results. The business can then apply for a recommendation for an Indonesian Greenhouse Gas Emissions Reduction Certificate, known as SPE GRK.

These steps are designed to make sure that carbon credits are based on real, documented and verified results. Projects using other carbon credit standards may also qualify, subject to the relevant approval process.

Projects must also follow rules on social and environmental protection, public participation and legal compliance.

The regulation also seeks to prevent double counting. This happens when the same emissions reduction is claimed more than once by different parties or programs. Preventing this is important because buyers need to know that a credit represents a real emissions cut or carbon removal that has not already been counted elsewhere.

National Carbon Registry Sets the Path for Tracking Farm Credits

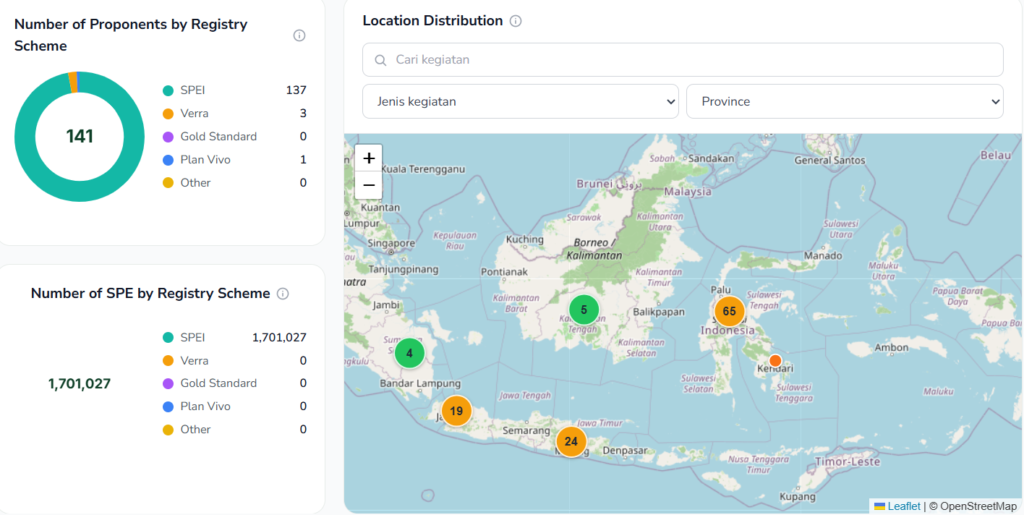
Agricultural carbon projects will use Indonesia’s national carbon registry, known as the Sistem Registri Unit Karbon, or SRUK. The registry records carbon units and helps track projects and transactions. It is part of the government’s wider effort to organize the country’s carbon market.

Indonesia’s national carbon registry summary
Source: Sistem Registri Unit Karbon (SRUK)

Project developers must submit the required documents and follow the rules for project review, independent checks and approval. Moreover, projects that want to transfer carbon credits for use by another country or for international purposes may need additional approval from the environment minister. This follows a recommendation from the agriculture minister.

  • Approval to run a project does not automatically allow its credits to be transferred internationally. Projects must meet the separate requirements that apply to those transfers.

The rules also cover projects that combine agriculture with other activities, such as planting trees among crops, making biochar or producing biogas from waste. Any government charges must follow Indonesia’s rules on non-tax state revenue. The regulation does not set one fee that applies to every project.

Indonesia’s Wider Carbon Market Is Expanding

The new agricultural rules are part of Indonesia’s wider effort to build a carbon market for both domestic and international trading.

Indonesia launched its national carbon exchange, IDXCarbon, in September 2023. By July 2025, it had recorded more than 1.6 million tonnes traded, worth about US$4.7 million. These figures show that a market is already operating, although they do not represent agricultural credits alone.

The country is also preparing for more international carbon trading under Article 6 of the Paris Agreement. Article 6 allows countries to trade verified emissions reductions under rules designed to prevent the same reduction from being counted twice.

As of October 13, 2026, the UN Environment Programme Copenhagen Climate Centre’s Article 6 database listed four bilateral agreements and 40 Article 6.2 activities for Indonesia. It reported no internationally transferred or received mitigation outcomes yet. This suggests the country has a growing project pipeline, but international transfers remain at an early stage.

Indonesia also has major natural resources that could support its wider carbon market. The country has about 95.5 million hectares of forest and around 3.44 million hectares of mangroves, equal to roughly 20% of the world’s mangrove area. Its FOLU Net Sink 2030 program aims for the forestry and land-use sector to absorb a net 140 million tonnes of CO₂ equivalent by 2030.

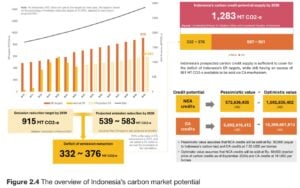
Indonesia’s carbon market potential
Source:

Forestry and land-use projects are different from farm carbon projects, but they show why Indonesia is working to strengthen its rules for carbon trading across several sectors.

In July 2026, Verra announced it would issue at least 20 million tonnes of emissions reductions. This comes from three Indonesian forestry projects under new carbon market rules. This was an expected issuance, not a report that all 20 million tonnes had already been issued.

Will Indonesia’s New Rules Expand Farm Carbon Investment?

Indonesia’s new rules create a clearer process for agricultural carbon projects, including credit approval and benefit-sharing with farmers.

Businesses must meet project requirements and agree with farmer groups on how to share benefits. However, farmers are not guaranteed a fixed income, as payments will depend on project results and agreed terms.

The rules add to Indonesia’s wider carbon market framework under Presidential Regulation No. 110 of 2025. Their impact will depend on how well projects follow the requirements and turn verified emissions cuts into approved carbon credits.

The post Indonesia Sets New Rules for Farm Carbon Credits and Farmer Benefits appeared first on Carbon Credits.
Frontier Signs $11.7M Carbon Removal Deal With 44.01’s Rock-Mineralization Technology

44.01, a carbon removal company founded in Oman and headquartered in London, has signed an $11.7 million carbon removal purchase agreement with Frontier to permanently store carbon dioxide (CO₂) underground by converting it into rock. The deal will support the company’s efforts to move its technology from short-term field trials to continuous commercial operations.

Under the agreement, Frontier buyers will purchase the removal of 20,932 tonnes of CO₂ between 2028 and 2031. The project marks Frontier’s first offtake agreement for in-situ mineralization (ISM), a process that accelerates natural reactions between dissolved CO₂ and underground rocks to lock carbon away for geological timescales.

How 44.01 Converts CO₂ Into Rock

44.01 uses peridotite, a magnesium-rich rock that reacts with dissolved carbon dioxide to form stable carbonate minerals. The company has demonstrated its approach in Oman and the United Arab Emirates (UAE), where extensive peridotite formations provide potential sites for underground mineralization.

The process involves five main steps:

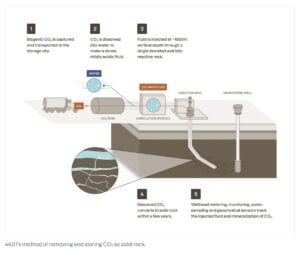
  • Capture: The project separates biogenic CO₂ during biogas upgrading at a wastewater treatment plant and transports it to the storage site.
  • Dissolution: The company mixes the captured CO₂ with water to create a mildly acidic solution.
  • Injection: A deviated well, drilled to approximately 1,000 meters underground, distributes the carbonated water through naturally fractured peridotite.
  • Mineralization: The dissolved CO₂ reacts with magnesium-rich minerals and forms solid carbonates. 44.01 says this process can take one to three years.
  • Monitoring: Mass-flow meters, fluid samples, and geophysical sensors help track the injected CO₂, verify mineralization and monitor underground fluid movement and potential induced seismicity.

Once the CO₂ becomes solid carbonate, the risk of reversal becomes extremely low, allowing the carbon to remain stored over geological timescales.

Why In-Situ Mineralization Could Expand Carbon Storage

Permanent storage remains a major challenge for carbon removal projects. Technologies such as direct air capture and bioenergy with carbon capture and storage can generate concentrated CO₂ streams, but developers still need suitable locations and infrastructure to store the gas.

Conventional geological storage typically involves compressing CO₂ and injecting it into deep sedimentary formations. Although this approach works for large projects, it can be expensive for smaller facilities that produce limited volumes of CO₂. Pipelines, transportation infrastructure, and lengthy permitting processes can make these projects difficult to develop.

44.01’s technology could help address this problem by allowing developers to store CO₂ in reactive rock formations closer to where emissions originate.

For example, industrial sources near the company’s existing UAE site are within 50 kilometers of suitable peridotite formations but more than 300 kilometers from viable conventional storage in the Gulf. Similar opportunities may exist in Japan, Oman, Finland, inland Norway, and along the US Pacific coast.

The potential benefits include:

  • Lower transportation needs: Projects could avoid expensive pipelines or shipping when suitable rock formations are located near CO₂ sources.
  • Permanent storage: Mineralization converts dissolved CO₂ into stable solid minerals.
  • Access for smaller facilities: Wastewater treatment plants, biogas facilities and smaller industrial sites could gain additional storage options.
  • Broader industrial applications: The technology could store concentrated CO₂ captured from cement, steel and other hard-to-abate industries.

Frontier estimates that suitable reactive rock formations could support more than 5 billion tonnes of CO₂ storage annually worldwide. It also identifies more than 50 million tonnes of industrial emissions in the UAE that could potentially be captured and stored through in-situ mineralization. These figures represent estimated potential, not existing operational capacity.

carbon removal
Source: McKinsey

Project Targets Commercial-Scale Operations

44.01 has conducted five field pilots and short-duration CO₂ injection programs since 2023. The Frontier agreement will help the company test whether it can maintain target injection rates over multiple years and determine how much water continuous operations require.

The company has designed its deviated wells to expose injected fluids to a larger volume of reactive rock. Drawing on drilling techniques used in enhanced geothermal energy and the oil and gas industries, this approach could improve injection rates and reduce costs.

44.01 also says that dissolving CO₂ in water before injection adds a containment layer. The company monitors underground fluid movement and relies on geological barriers to provide additional safeguards. TÜV SÜD and the XPRIZE Carbon Removal board have conducted third-party safety reviews of its approach.

Talal Hasan, founder and CEO of 44.01, said the agreement would help move in-situ mineralization toward commercialization. The company plans to improve operating performance, reduce costs, and make permanent storage accessible to more customers.

Hannah Bebbington Valori, Frontier’s head, said the technology could expand the range of locations where permanent CO₂ storage becomes economically practical.

CCS: Total Operational Capacity and Growth

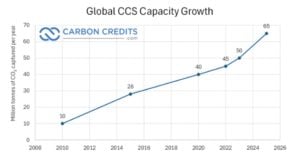
As of 2024, global CCS facilities in operation had a combined capture capacity of just over 50 million tonnes of CO₂ per year. This shows steady growth, up from about 40 Mt a few years ago. However, it still accounts for just a small part of the over 40 billion tonnes of CO₂ emitted worldwide each year.

CCS

Carbon Removal Market Sees Rising Demand

The deal comes as companies increase their purchases of carbon dioxide removal (CDR) to address residual emissions that remain after direct emission reductions.

Carbon capture and storage (CCS) and carbon removal serve related but different purposes. CCS generally prevents CO₂ from industrial sources from entering the atmosphere, while carbon removal takes CO₂ already in the atmosphere and stores it durably. In-situ mineralization can support both applications, depending on the source of the captured carbon.

Recent market activity points to stronger demand for durable carbon removal:

  • Corporate demand is growing: Buyers committed to 2.1 million tonnes of carbon removal in Q2 2026, up 136% year over year, across 14 deals.
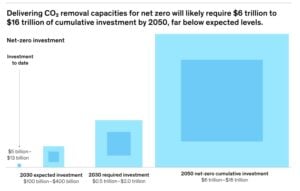
  • Supply may fall short: McKinsey estimates durable carbon removal demand could reach 100 million tonnes annually by 2030, double the 50 million tonnes of announced supply.
  • Financing supports growth: Advance purchase agreements help early-stage developers fund projects, test technologies and prepare for commercial expansion.

The World Economic Forum’s 2026 analysis, developed with Oliver Wyman and ClimeFi, also highlights limited access to capital, fragmented standards, and unclear accounting rules as barriers to scaling carbon removal technologies.

Frontier Deal Could Open a New Storage Pathway

The agreement allows 44.01 to demonstrate whether in-situ mineralization can operate continuously, store CO₂ permanently, and deliver reliable performance at a commercially viable cost.

If the project succeeds, the technology could expand permanent storage options for industrial facilities and carbon removal developers that cannot economically access conventional geological storage.

However, scaling the technology will depend on the results of multi-year trials, the availability of suitable rock formations, water requirements, and project economics.

For the wider carbon removal market, the deal highlights the importance of financing early-stage technologies that could increase long-term storage capacity. As demand grows, approaches such as in-situ mineralization could help developers build the infrastructure needed to deliver durable carbon removal at a larger scale.

The post Frontier Signs $11.7M Carbon Removal Deal With 44.01’s Rock-Mineralization Technology appeared first on Carbon Credits.
TotalEnergies and KKR Add $1.2 Billion Solar Portfolio to U.S. Renewables Venture

TotalEnergies and KKR Add $1.2 Billion Solar Portfolio to U.S. Renewables Venture

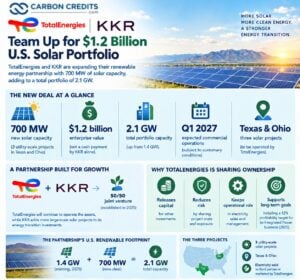
TotalEnergies and investment firm KKR are expanding their U.S. renewable energy partnership with a solar portfolio valued at $1.2 billion. The deal adds 700 megawatts (MW) of solar capacity to their joint venture, increasing its total renewable energy portfolio from 1.4 gigawatts (GW) to 2.1 GW.

Announced on October 12, 2026, the agreement covers three large solar projects in Texas and Ohio. The assets are expected to begin commercial operations by the first quarter of 2027. TotalEnergies will continue to operate them after the deal closes, which is expected in 2026, subject to customary conditions.

The agreement builds on a partnership formed in 2025. TotalEnergies’ strategy focuses on sharing renewable energy assets with financial investors. They still manage operations and sell the electricity produced.

For KKR, the deal adds more large-scale solar assets to its energy transition investments. For TotalEnergies, it provides another way to expand its electricity business while sharing the cost and financial risks of owning renewable projects.

A $1.2 Billion Deal Adds 700 MW of Solar Power

The new portfolio includes three utility-scale solar projects in Texas and Ohio. Utility-scale projects are large facilities that generate electricity for the power grid or major customers.

The portfolio has an enterprise value of $1.2 billion. Enterprise value measures the value of a business or asset portfolio, taking debt and cash into account. It should not be treated as the cash payment made by KKR alone.

The new assets will join the 50/50 joint venture that TotalEnergies and KKR established in 2025. Before this latest agreement, the venture held 1.4 GW of renewable energy capacity. The additional 700 MW will bring its total to 2.1 GW.

The electricity produced by the three projects is already sold to third parties or will be marketed by TotalEnergies. These arrangements can help connect the projects’ output with customers and provide a route to market for the electricity.

TotalEnergies will continue operating the assets after the transaction closes. The companies have not disclosed the full payment structure for the latest deal.

The projects are expected to reach commercial operation by the first quarter of 2027. This means the assets are moving toward the stage when they can supply electricity as planned, rather than simply being part of a future development pipeline.

Why TotalEnergies Is Sharing Ownership

The latest agreement comes after a deal from September 2025. At that time, TotalEnergies sold a 50% stake in a North American solar portfolio to KKR-managed investment vehicles and accounts.

That earlier portfolio had an enterprise value of $1.25 billion. It included six large solar projects with a combined capacity of 1.3 GW and 41 smaller distributed-generation assets totaling 140 MW.

TotalEnergies said the earlier transaction, together with planned refinancing, was expected to bring it about $950 million at closing. The company retained a 50% stake and continued operating the assets.

This approach is part of the company’s wider business model. TotalEnergies can develop renewable projects, bring in a financial partner, and sell part of its ownership once the assets reach operation and their risks are lower.

Selling a stake can release capital for other investments. Keeping ownership and operating roles lets the company stay connected to the assets and their electricity sales.

In its 2025 announcement, TotalEnergies said it aims for a 12% profitability target for its Integrated Power business. Its strategy includes selling up to 50% of renewable assets after they begin operating and their risks have been reduced.

The latest deal continues that approach. It gives KKR a larger share of U.S. renewable infrastructure while allowing TotalEnergies to remain involved in day-to-day operations.

U.S. Solar Capacity Set for a Major Expansion in 2026

The agreement comes as the United States prepares to add more electricity generation capacity, with solar power expected to account for a large share of new projects.

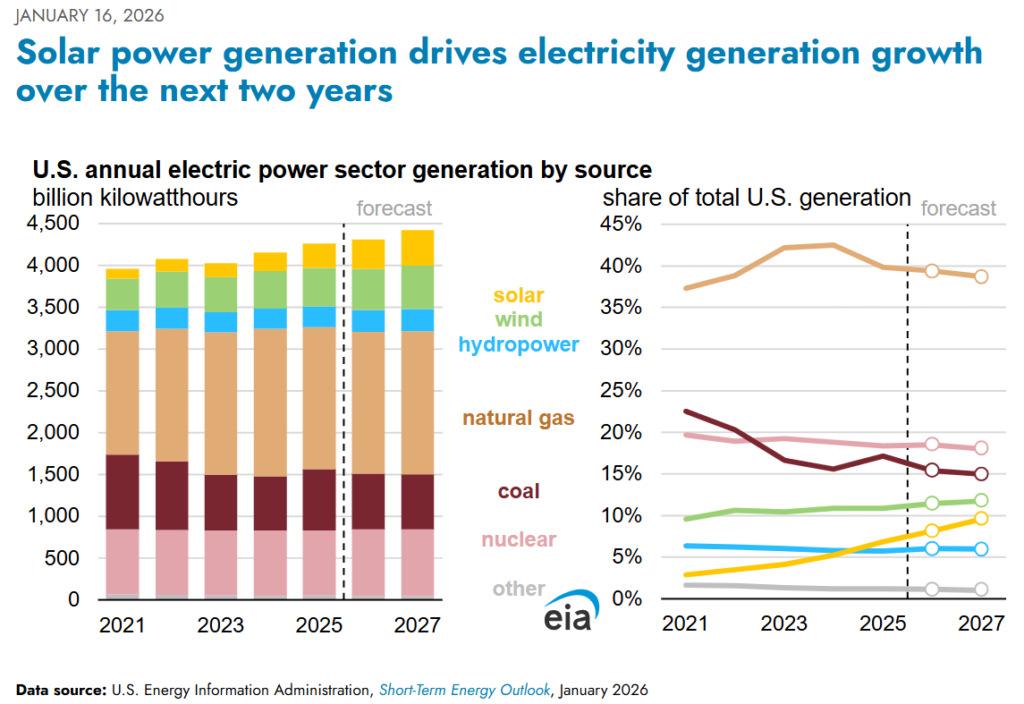
The U.S. Energy Information Administration (EIA) reported in February 2026 that developers aimed to add 86 GW of new utility-scale electricity capacity this year. Solar was expected to account for 51% of those planned additions, followed by battery storage at 28% and wind at 14%.

Solar power generation

The EIA projected 43.4 GW of new utility-scale solar capacity for 2026, which would be a 60% increase from 2025 if all planned projects were completed. Texas was expected to account for 40% of the planned solar additions. These are forecasts, not confirmed final installations.

The agency also expects electricity demand to keep growing. In its September 2026 outlook, the EIA forecast U.S. electricity sales of 4,135 billion kilowatt-hours in 2026 and 4,211 billion kilowatt-hours in 2027. It pointed to data center development and increased manufacturing activity as factors behind rising demand.

This creates an important market for new generation projects. Solar can supply electricity during daylight hours, while battery storage can help shift some power to later periods. However, the value of each project depends on local grid conditions, customer contracts, financing costs, and the timing of electricity supply.

The TotalEnergies-KKR portfolio boosts this growing market. However, the companies haven’t shared the expected yearly electricity output for the three projects.

TotalEnergies Builds Its Electricity Business

TotalEnergies is a global energy company with operations in oil, natural gas, biofuels, low-carbon hydrogen, renewable power, and electricity.

Its renewable energy portfolio has grown as the company seeks to build a larger electricity business alongside its traditional energy operations. By the end of June 2026, TotalEnergies reported more than 37 GW of gross renewable power generation capacity worldwide. It aims to produce more than 100 terawatt-hours (TWh) of net electricity annually by 2030.

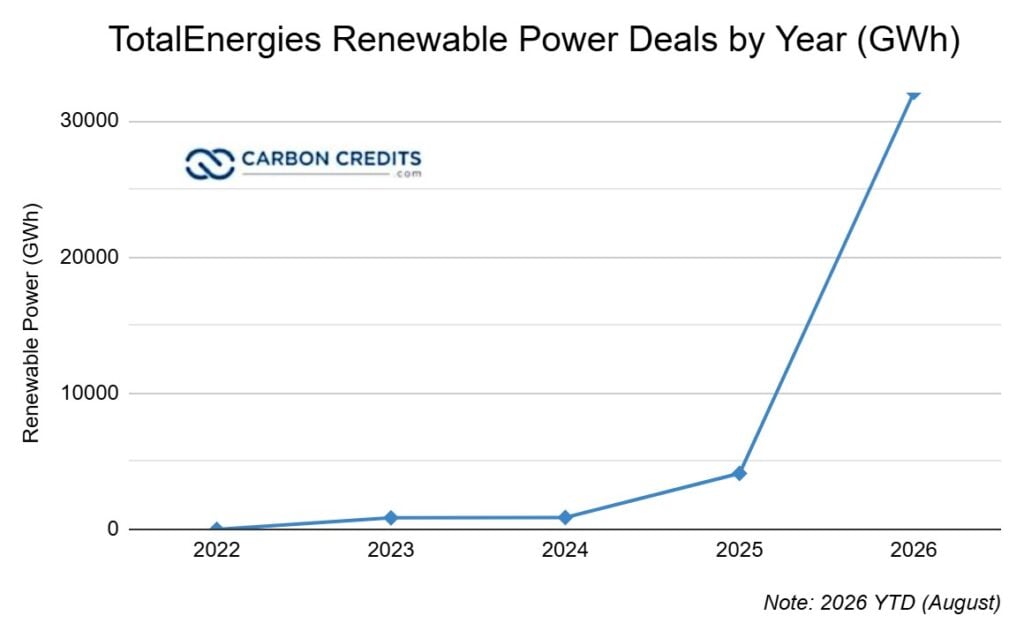
TotalEnergies Renewable Power Deals by Year (GWh)

In the United States, the company reported about 10 GW of installed renewable power capacity at the end of 2025, including solar, wind, and battery storage. Around 5 GW of that portfolio was in Texas. It also operates flexible power generation assets that can help balance changes in renewable output.

The company’s strategy is not limited to building solar farms. It aims to mix renewable energy with flexible power and trading. This way, it can provide customers with power when and where they need it.

The KKR partnership supports this approach by allowing TotalEnergies to keep operating assets while sharing ownership with an investor. It also gives the company a way to manage the capital needed for its wider portfolio.

What the Deal Means for KKR and the Energy Market

KKR is a global investment firm that invests across areas including private equity, credit, infrastructure, and real assets. Its investment in the joint venture gives it exposure to large-scale renewable energy projects with existing or planned routes to sell electricity.

The latest agreement increases the venture’s portfolio to 2.1 GW, strengthening its position in the U.S. solar market. For investors like KKR, owning renewable assets offers a way to tap into long-term electricity demand. However, returns rely on costs, contracts, project performance, and market conditions.

For TotalEnergies, the deal helps balance growth with capital discipline. The company can retain operational responsibility without keeping full ownership of every asset it develops or acquires.

TotalEnergies and KKR Solar Partnership

The climate benefits will depend on how much electricity the solar projects deliver and which power sources that electricity replaces. Solar panels produce electricity without burning fossil fuels. However, their total lifecycle emissions come from manufacturing, construction, and transporting equipment.

The transaction itself does not guarantee a specific amount of emissions reduction. The companies have not announced a project-level emissions forecast for the three assets.

A Growing Partnership in U.S. Clean Power

The $1.2 billion portfolio deal marks another step in the expansion of the TotalEnergies-KKR joint venture. Adding 700 MW will lift its renewable capacity to 2.1 GW, with the three solar projects expected to reach commercial operation by early 2027.

The agreement also shows how energy companies and financial investors can work together to fund large renewable assets. TotalEnergies retains an operating role and can market electricity, while KKR shares ownership and investment exposure.

As U.S. electricity demand grows and more solar capacity enters the market, such partnerships could remain an important way to finance renewable power. Their long-term success will depend on project delivery, reliable electricity sales, and returns that justify the capital invested.

The post TotalEnergies and KKR Add $1.2 Billion Solar Portfolio to U.S. Renewables Venture appeared first on Carbon Credits.
Electricity Generation to Hit 84,000 TWh by 2060: Can Renewables Deliver?

Global electricity generation is set to more than double over the next 35 years as renewable energy expands, electric vehicles replace gasoline-powered cars, and demand from artificial intelligence (AI) and data centers increases. However, building enough power generation, transmission lines, and energy storage to support this growth will be a major challenge.

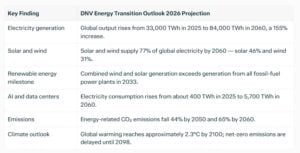
According to DNV’s Energy Transition Outlook 2026, global electricity generation will rise from 33,000 terawatt-hours (TWh) in 2025 to 84,000 TWh by 2060, an increase of 155%. Solar and wind power will drive much of this expansion, gradually replacing fossil fuels in electricity generation.

Yet the transition will not automatically deliver the emissions cuts needed to meet global climate goals. DNV forecasts that the world will experience 2.3°C of warming by 2100 under its most likely energy transition pathway.

The report highlights a central challenge for the global energy market: the world must generate far more electricity while making the energy system cleaner, more reliable and affordable.

Key Findings From DNV’s Energy Transition Outlook 2026

Energy transition
Source: DNV

Electricity Demand Will Surge as Economies Electrify

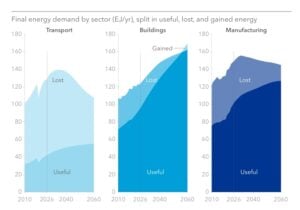
Electricity is becoming central to the global energy transition. Transport, buildings and industrial facilities are increasingly switching from direct fossil-fuel use to electric alternatives.

DNV forecasts that electricity demand will grow by 80% by 2050.

  • The increase will come from several sources, including electric vehicle charging, space cooling, data centers, and the production of low-carbon fuels such as hydrogen.
  • Buildings will also contribute significantly to this growth. Rising populations, urbanization, and higher living standards will increase building electricity consumption by 75% by 2060, excluding data centers.
  • Meanwhile, the global vehicle fleet is projected to be 84% electric by 2060. As more cars and commercial vehicles use electricity instead of gasoline or diesel, transport will become increasingly dependent on reliable power supplies.

Electricity generation must grow even faster than demand alone might suggest. DNV explains that a power system with a larger share of variable renewable energy also needs additional generation to support storage, system flexibility, and transmission losses.

As a result, the expansion of electricity supply will require investment not only in new power plants but also in the infrastructure needed to deliver electricity reliably.

renewable electricity demand
Source: DNV

Solar and Wind Will Dominate Global Power Generation

Solar and wind are expected to account for most of the growth in electricity generation through 2060.

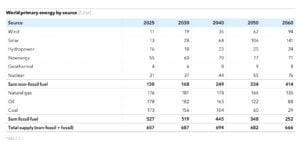
DNV forecasts that solar power will supply 46% of global electricity by 2060, while wind will contribute 31%. Together, they will generate more than three-quarters of the world’s electricity.

The shift is expected to accelerate during the next decade. DNV projects that combined solar and wind generation will exceed output from all fossil-fuel power plants in 2033.

The forecast reflects the growing competitiveness of renewable energy and the increasing importance of energy security. Countries that depend on imported oil and gas are expanding domestic renewable power to reduce exposure to fuel price swings and supply disruptions.

GRID MIX RENEWABLE S
Source: DNV

Grid Investment Must Keep Pace

DNV reports that annual global spending on renewables increased from $860 billion in 2021 to $1.77 trillion in 2026. The report expects investment in renewable power, electricity grids and storage to triple by 2040.

However, adding renewable capacity is only part of the challenge. Solar and wind output changes with weather conditions and time of day, making grid flexibility and storage increasingly important.

Battery Storage Gains Momentum

Battery storage is expanding rapidly. DNV says installed utility-scale battery storage capacity increased 14-fold over the five years covered by its latest assessment, while twice as much utility battery storage was installed in 2026 as in 2025.

Even so, the report warns that transmission capacity and demand flexibility are not growing fast enough. Without faster infrastructure development, electricity networks could struggle to accommodate the growing volume of renewable power.

AI and Data Centers Add to Power Demand

The rapid expansion of AI is creating another source of electricity demand. Data centers need substantial amounts of power to operate servers, cooling systems, and computing equipment.

DNV estimates that global data centers consumed approximately 400 TWh of electricity in 2025, equivalent to 1.2% of global electricity supply.

The report forecasts that consumption will increase to:

  • 1,100 TWh in 2030.
  • 2,700 TWh in 2040.
  • 5,700 TWh in 2060.

By 2060, data centers will account for 6.8% of global electricity consumption, according to DNV.

AI Data center power demand
Source: DNV

The growth creates opportunities for renewable energy developers, battery storage providers and electricity infrastructure companies. Technology companies will also need reliable power supplies to support expanding computing operations.

However, DNV cautions that access to dependable electricity could become a constraint on data center development. Grid connections, cooling infrastructure, and the availability of firm power will influence how quickly new facilities can be built.

AI demand also remains uncertain. Improvements in computing efficiency could reduce electricity use per task, while greater AI adoption and more intensive computing could push consumption higher.

Fossil Fuels Will Decline, but Emissions Remain a Challenge

The shift toward renewable electricity will reduce the role of fossil fuels, but it will not eliminate them quickly.

DNV forecasts that fossil fuels will account for 51% of global primary energy supply in 2050, down from around 80% historically. Oil demand is expected to decline over the longer term, while natural gas demand is projected to peak around 2035. Coal demand will resume its decline in 2027 and fall by 82% to 2060.

The power sector will deliver substantial emissions reductions as renewable generation replaces fossil-fuel plants. DNV forecasts that energy-related CO₂ emissions will decline 44% from approximately 39 gigatonnes today to 22 gigatonnes in 2050.

  • By 2060, energy-related emissions are projected to fall 65% to 12 gigatonnes annually.
energy related emissions
Source: DNV

However, some industries will be harder to decarbonize. Cement manufacturing, for example, releases CO₂ through chemical reactions involved in production. Switching to renewable electricity cannot eliminate these process emissions on its own.

DNV expects process emissions to decline by only 14% by 2060, compared with a 65% reduction in energy-related emissions. Carbon capture and storage, alternative industrial processes and carbon dioxide removal could help address some of these remaining emissions.

The report forecasts that direct air capture will remove 0.4 gigatonnes of CO₂ annually by 2060, increasing to 3 gigatonnes by 2100. However, the technology must scale considerably to play this role.

Can the Energy Transition Meet Climate Goals?

  • DNV expects global net-zero emissions to be reached around 2098, with warming reaching 2.3°C by 2100. Its forecast suggests that the world will exceed the remaining carbon budget for limiting warming to 2°C by approximately 420 gigatonnes of CO₂.

For investors, the outlook points to long-term opportunities in renewable generation, battery storage, transmission infrastructure, electrification and industrial decarbonization. It also highlights the need for carbon capture and removal technologies to address emissions that are difficult to eliminate.

Ultimately, generating 84,000 TWh of electricity will require a major expansion of the global power system. The challenge is ensuring that this growth comes with cleaner generation, stronger grids and faster emissions reductions.

The energy transition is gaining momentum, but DNV’s forecast shows that expanding clean electricity alone will not be enough to meet global climate targets.

The post Electricity Generation to Hit 84,000 TWh by 2060: Can Renewables Deliver? appeared first on Carbon Credits.