Apple (AAPL) Stock Climbs as iPhone 18 Pro Goes Greener. Can 40% Recycled Content Reduce Its Carbon Footprint?
Apple’s newest iPhone arrives with more than a new camera and faster performance. Behind the glossy launch of the iPhone 18 Pro and iPhone 18 Pro Max is another story: how much carbon it takes to make, ship, and use a smartphone.

At the same time, Apple is pushing recycled materials deeper into the device, using renewable electricity across manufacturing and eliminating landfill waste at established final assembly supplier sites.

Let’s take a closer look at the emissions footprint of its latest gadget.

iPhone 18 Pro’s Carbon Footprint Starts at 63 kg

Apple calculates the iPhone 18 Pro’s footprint using a life-cycle assessment covering the device, components, packaging, and in-box accessories.

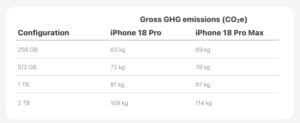
Its latest product environmental report puts a number on that footprint. Depending on the storage configuration, an iPhone 18 Pro generates between 63 kg and 109 kg of gross greenhouse gas emissions over its modeled life. For the Pro Max, the range is 69 kg to 114 kg.

The footprint rises with storage capacity.

They say production is the biggest source of emissions, accounting for 46% of the 256GB iPhone 18 Pro footprint. Non-electricity-related production, including materials and processes, accounts for 17%, while electricity contributes 29%.

Transportation represents 3%, customer use 13%, infrastructure for renewable energy generation 1%, and end-of-life processing less than 1%.

That breakdown shows why Apple is focusing so heavily on materials and supplier electricity rather than just making the phone itself more energy efficient.
iphone 18 carbon footprint
Source: Apple

40% Recycled Content Goes Inside the New iPhone

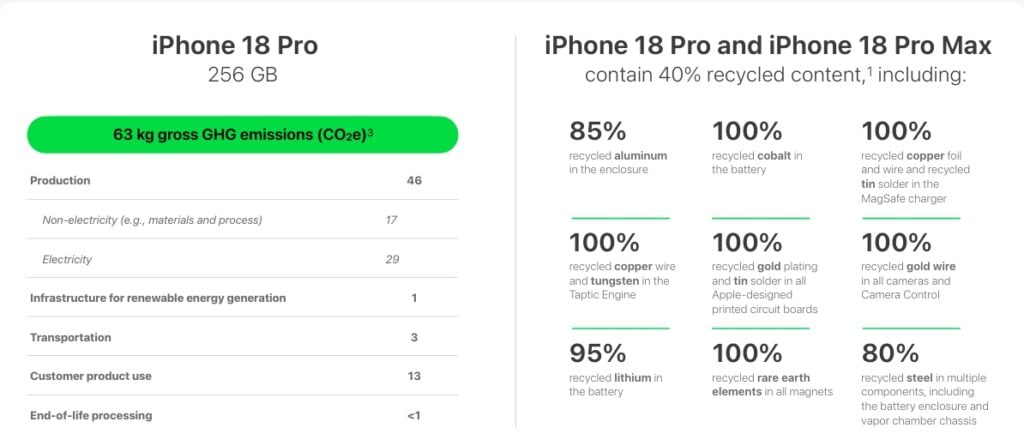
The iPhone 18 Pro and Pro Max contain 40% recycled content by mass, excluding packaging and accessories. This time, the company has also increased the use of recycled materials across individual components:

Apple says recycled materials generally have a lower carbon footprint than newly mined materials, making material recovery an important part of its product decarbonization strategy. Here’s the snapshot of the sustainable materials packed inside its latest gadget:
apple sustainability iphone 18
Source: Apple

50% of Manufacturing Electricity Comes From Renewables

Apple says 50% of the manufacturing electricity allocated to the iPhone 18 Pro and Pro Max comes from renewable energy.

That includes electricity procured by Apple or its suppliers through Apple’s Supplier Clean Energy Program. The company is ultimately working toward moving suppliers to 100% renewable electricity.

  • The phones also use 60% less energy than the applicable U.S. Department of Energy efficiency standard, according to Apple.

The 20W USB-C power adapter used for the models has measured efficiency of 87.4% at 100V, 88.0% at 115V and 87.8% at 230V. Its no-load power consumption is 0.04W across all three voltage levels.

Less Waste, More Fiber

Apple says all established final assembly supplier sites for the iPhone 18 Pro and Pro Max have been independently validated as Zero Waste to Landfill.

Under UL’s standard, suppliers need to divert at least 90% of waste away from landfill, with higher diversion rates qualifying for Gold and Platinum designations.

Packaging is also 100% fiber-based and uses recycled or responsibly sourced fibers.

The company is pairing that with stricter chemical controls. Final assembly suppliers must use safer cleaners and degreasers based on methodologies such as ChemFORWARD, GreenScreen and the U.S. EPA Safer Choice program.

Apple also says its materials, accessories and packaging are covered by its Regulated Substances Specification and that it conducts toxicological assessments of materials that have prolonged skin contact.

Apple’s Bigger Emissions Problem

The iPhone footprint is only one piece of Apple’s climate story.

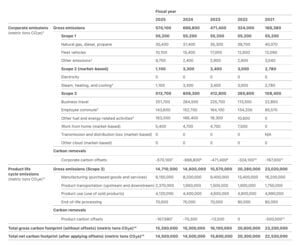
According to Apple’s 2026 Environmental Progress Report, the company’s 2025 gross greenhouse gas emissions were about 15.3 million metric tons of CO2e, while net emissions after offsets were 14.5 million tons. It estimated that its environmental programs avoided 43 million metric tons of emissions in 2025.

Notably, product manufacturing accounted for 53% of Apple’s gross footprint

Apple says its gross emissions are down more than 60% from 2015, even though revenue has increased 78% over the same period. Its 2030 goal is to reduce value-chain emissions by 75% from the 2015 baseline before addressing the remaining emissions.

The company’s environmental programs avoided an estimated 43 million tons of emissions in 2025, including:

  • 26 million tons from supplier clean energy
  • 7 million tons from direct emissions abatement
  • 6 million tons from low-carbon materials
  • 2 million tons from supplier energy efficiency.

                                          Apple’s Emissions Data
apple sustainability emissions
Source: Apple

Apple Stock (AAPL) Rises as the iPhone 18 Pro Hits Stores

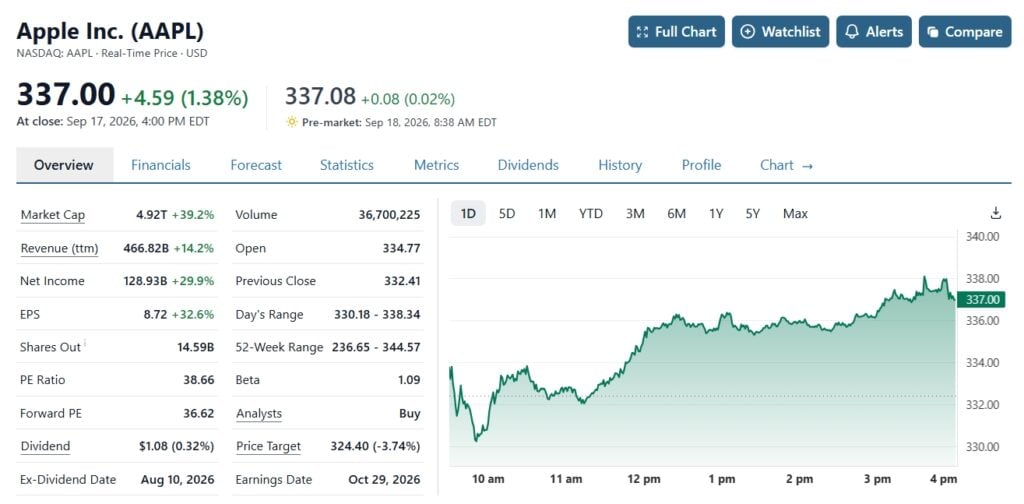
Apple shares closed at about $315.34 on September 9, according to market data reported after the launch. By September 11, shares had reached $332.27, representing a roughly 5.4% increase from the September 9 close.

On September 17, Apple shares closed at $337, according to market reporting, after gaining 1.4% that day as the phones approached their retail launch.

As trading began on September 18, AAPL was around $337, putting the stock roughly 7% above its September 9 closing level.

The market reaction, however, is being driven primarily by expectations around demand, pricing, and the premium iPhone mix rather than Apple’s environmental credentials. Early reports said carrier trade-in offers of as much as $1,200 were helping support demand for the new Pro models.
apple stock
Source: Stock Analysis

The Bigger Sustainability Test Is the Supply Chain

Apple’s iPhone 18 Pro shows how sustainability is becoming embedded in product design rather than treated as a separate corporate initiative.

More recycled metals, renewable electricity, fiber packaging, lower energy use, and supplier waste controls can all reduce the footprint of each device.

But Apple’s own numbers also show the scale of the challenge. Manufacturing remains the largest part of the iPhone’s carbon footprint, while product manufacturing and product use together account for 80% of Apple’s broader gross footprint.

The iPhone 18 Pro may therefore be greener by design, but Apple’s bigger climate challenge is making those improvements meaningful across hundreds of millions of devices and a global supply chain.

That is where the company’s 2030 target will ultimately be tested.

The post Apple (AAPL) Stock Climbs as iPhone 18 Pro Goes Greener. Can 40% Recycled Content Reduce Its Carbon Footprint? appeared first on Carbon Credits.
GSK Signs 8-Year Carbon Removal Deal With Varaha to Scale Regenerative Farming in India

GSK Signs 8-Year Carbon Removal Deal With Varaha to Scale Regenerative Farming in India

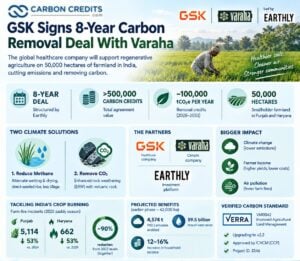
Global healthcare company GSK has signed an eight-year deal with Indian climate company Varaha to cut emissions and enhance carbon removal. It will support regenerative agriculture on 50,000 hectares of smallholder farmland in Punjab and Haryana.

The deal was structured by climate investment platform Earthly and covers more than 500,000 carbon credits. The project is expected to deliver about 100,000 tonnes of removal credits a year between 2028 and 2033. The wider agreement runs for eight years.

The project will help farmers move away from crop residue burning, intensive tillage and flood-irrigated rice farming. Instead, farmers will use practices such as direct-seeded rice, reduced tillage and crop-residue incorporation.

The deal is notable because it links carbon finance with three major issues in northern India: climate change, farm income and air pollution.

Adele Cheli, VP Environmental Sustainability at GSK, said:

“For GSK, environmental sustainability is core to business resilience and human health. This investment demonstrates how we’re progressing in our net-zero journey, whilst also delivering co-benefits for human health, nature and local communities.”

Carbon Finance Targets India’s Crop Burning Problem

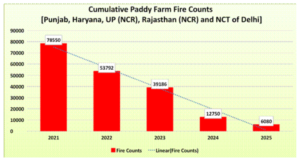
Farmers in Punjab and Haryana often burn rice residue after harvest because they have only a short period to prepare fields for the next crop. India has been working to reduce the practice, and the number of farm fires has fallen sharply.

During the 2025 paddy season, Punjab recorded 5,114 farm-fire incidents, down 53% from 2024. Haryana recorded 662, also a 53% fall. Together, the two states recorded about a 90% reduction from 2022 levels.

farm-fire incidents india

Despite that progress, the government continues to identify crop-residue burning as an important source of seasonal air pollution in northern India.                                                                                            

The carbon project aims to address the economic reasons farmers burn the residue. Farmers will receive subsidized access to machinery and a share of carbon credit revenue.

That can help cover the extra cost and labour needed to manage crop residues without burning them. This makes the carbon market part of the solution rather than simply paying for an emissions calculation after the fact.

Regenerative Farming Targets Carbon, Water and Farm Income

The Varaha project is designed to generate both emissions reductions and soil carbon removals.

Reduced tillage can lower fuel use and soil disturbance. Direct-seeded rice can reduce the need for intensive field preparation and flooding. Incorporating crop residues into the soil can also return organic matter to farmland.

Varaha’s project has already reported results from an earlier monitoring period covering 42,000 hectares. The project estimated it avoided about 4,574 tonnes of PM2.5 emissions from crop burning. It also saved around 59.5 billion litres of water.

Moreover, participating households saw an average 12% to 16% increase in income. This rise came from higher yields, lower fertilizer costs, and carbon revenue.

The water figure is particularly notable. Across the 42,000-hectare monitoring area, the reported savings work out to roughly 1.4 million litres per hectare.

These figures are project results, not a guarantee for the full 50,000-hectare expansion. Future performance will depend on farmer adoption, weather, crop yields and verification.

The Project Uses Verra’s Agricultural Carbon Methodology

The project is registered under the Verra Verified Carbon Standard, using VM0042 Improved Agricultural Land Management. Earthly says it is also upgrading the project to version 2.2 of the methodology. The project is listed on the Verra system as Project 3346.

VM0042 covers greenhouse gas reductions and soil organic carbon removals from improved farming practices. These include reduced tillage, better fertilizer use, and residue and water management.

The updated VM0042 v2.2 is approved by the Integrity Council for the Voluntary Carbon Market as meeting its Core Carbon Principles (CCP) requirements. However, that does not automatically give every project or credit a CCP label. Projects must meet additional conditions at verification.

Those rules are important for agricultural carbon because soil carbon can be difficult to measure and can change over time. The updated methodology includes stronger requirements around baselines, additionality, leakage, and soil carbon measurement.

GSK Is Building a Larger Carbon Removal Portfolio

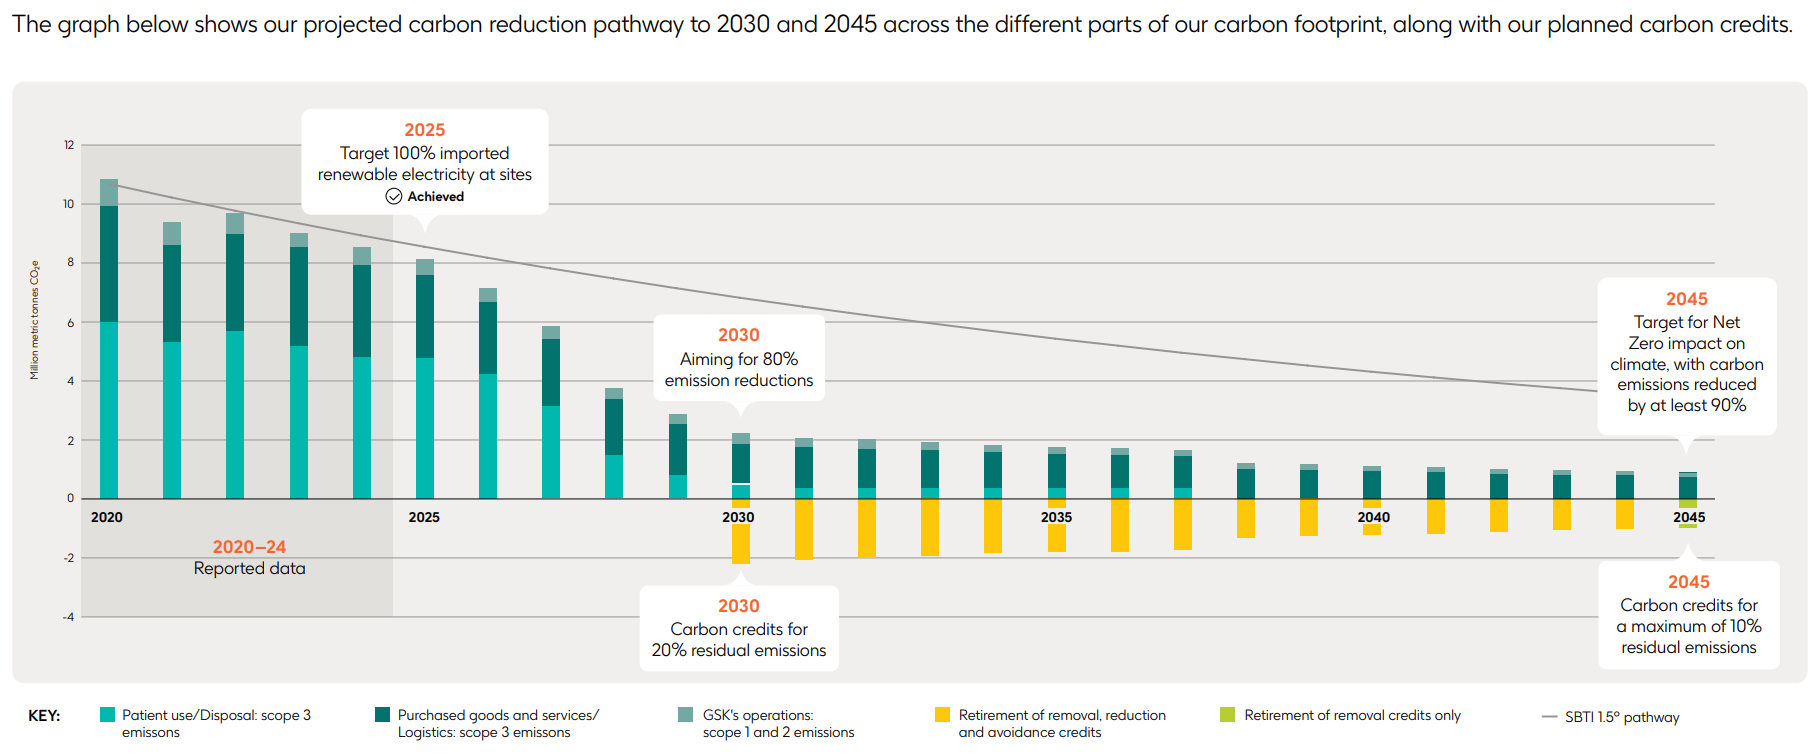
The Varaha deal fits directly into GSK’s broader climate strategy. The pharma giant plans to reduce 80% of greenhouse gas emissions from all scopes by 2030, using a 2020 baseline. Nature-based solutions will address the final 20%.

GSK net zero pathway
Source: GSK

It also targets net zero across its full value chain by 2045, including a 90% absolute emissions reduction and neutralization of residual emissions. GSK says it prioritizes carbon removals for its 2030 target and plans to use only carbon removals for its 2045 net-zero target.

The company announced that by the end of 2025, it had secured carbon credits for 8% of its expected residual emissions. This is 40% of the credits it anticipates needing.

GSK value chain carbon footprint
Source: GSK

The Varaha agreement, therefore, adds to a growing pipeline of nature-based carbon projects that GSK is developing ahead of its future residual emissions needs. Importantly, GSK says carbon credits are being used alongside direct emissions cuts, rather than as a replacement for them.

Agriculture Is Becoming a Larger Carbon Market

The deal also shows why agriculture is becoming an important part of the carbon removal market. Verra said in 2025 that around 200 projects were listed under earlier versions of VM0042. Together, those projects had the potential to issue an estimated 126 million tonnes of emissions reductions and removals annually.

That is potential supply, not actual issuance. Still, it shows the size of the pipeline being developed around improved farming practices.

Agricultural projects can also offer benefits that are difficult to obtain from some industrial carbon removal technologies. These include improved soil health, lower water use, better farm resilience, and additional income for farmers.

At the same time, they face measurement challenges. Soil carbon changes slowly and can vary between fields. Weather and farming practices can also affect results. That makes strong measurement and independent verification essential for buyers such as GSK.

GSK varaha carbon removal

A Long-Term Deal Gives Farmers More Certainty

One of the most important parts of the agreement is its length. Many voluntary carbon transactions are relatively short-term purchases. An eight-year commitment helps Varaha see future demand better. This can support investments in farm equipment, field support, and measurement systems.

That matters because farmers need to change practices before carbon benefits can be measured.

The project also includes ongoing reporting. Earthly says the agreement includes quarterly reporting covering carbon, water, farmer income, and community engagement through the project period. This wider reporting is becoming more important as buyers look beyond the number of tonnes generated.

The Deal Is a Test for High-Quality Farm Carbon

The GSK-Varaha agreement is significant because it moves beyond a small demonstration project. The planned 50,000 hectares represent a large expansion of regenerative farming in a region where crop burning, water use, and soil management remain major challenges.

However, the more important test will be delivery. The project must show that farmers maintain the new practices, that soil carbon gains are measured accurately, and that the claimed emissions reductions are independently verified.

For GSK, the deal adds a significant source of future removals as it works toward its 2030 and 2045 climate targets. For Varaha, it provides long-term demand to scale regenerative agriculture. And for India’s farmers, the model could create another source of income while reducing burning and improving soil management.

For the carbon market, long-term corporate commitments can help turn agricultural carbon projects into real investments in climate, farming, and public health.

The post GSK Signs 8-Year Carbon Removal Deal With Varaha to Scale Regenerative Farming in India appeared first on Carbon Credits.

Factorial Energy (FAC) Teams Up With Mitsui Kinzoku to Scale Solid-State Batteries

The top U.S. battery developer Factorial Energy (Nasdaq: FAC) is bringing in a major Japanese materials company as it works to take its solid-state battery technology from advanced testing to commercial production.

It recently announced a strategic partnership with Japan’s Mitsui Kinzoku Company to support industrializing its Solstice™ all-solid-state battery platform.

The deal brings together two different pieces of the battery puzzle. Factorial focuses on cell design and manufacturing processes, while Mitsui Kinzoku brings its experience in sulfide-based solid electrolytes.

Siyu Huang, CEO of Factorial, noted:

“Battery innovation can’t be done by one single company. It’s driven by the entire supply chain and, increasingly, by an entire industry coalition. Mitsui Kinzoku’s foundational electrolyte technology brings critical materials expertise to our work to move Solstice™ toward commercial deployment. We’re not just building a battery. We’re building the connective thread that helps the whole industry move forward together.”

Mitsui Kinzoku Brings Materials Expertise

Factorial will continue to lead the Solstice platform as a fabless battery technology company. Its work covers cell design, process development, supply-chain qualification, production-line integration, and manufacturing validation.

Mitsui Kinzoku will contribute its expertise in advanced battery materials.

The Japanese company is one of the few major producers of sulfide-based solid electrolytes, an important component in all-solid-state batteries. Its A-SOLiD™ technology has been under development since 2016, and the company is working toward mass production at a dedicated facility in Saitama, Japan.

A Major Player in Semiconductor Materials

Mitsui Kinzoku also has a major position in semiconductor materials. It is a leading producer of ultra-thin copper foil and estimates that it holds about 90% of the global semiconductor market for that type of foil.

The partnership gives Factorial access to an established materials supplier while allowing Mitsui Kinzoku to work with a U.S. developer that is already testing solid-state cells in vehicles and other applications.

Dr. Kiyotaka Yasuda, Senior Executive Officer, General Manager, Business Creation Division of Mitsui Kinzoku Company, Limited, says:

“I am very pleased that we have been able to enter into this joint development agreement with Factorial. Batteries are a key technology for realizing an electrified society, but significant technical challenges still remain. That is precisely why we believe it is necessary to go beyond the extension of existing technologies and take on the challenge of creating new value.”

“By leveraging Mitsui Kinzoku’s long-established expertise in materials and manufacturing technologies and combining it with Factorial’s advanced technological capabilities, we aim to accelerate the realization of next-generation batteries.”

Why sulfide electrolytes matter

Traditional lithium-ion batteries use a liquid electrolyte to move lithium ions between the electrodes. Solid-state batteries replace that liquid with a solid material.

But sulfide-based electrolytes are attracting attention because they can provide high ionic conductivity while supporting the thin battery designs needed for high energy density.

However, they also bring manufacturing challenges. Producing consistent layers, managing moisture sensitivity, and integrating the materials into existing battery production lines can be difficult.

This makes manufacturing know-how just as important as the chemistry itself.

Solstice Targets More Energy With Less Weight

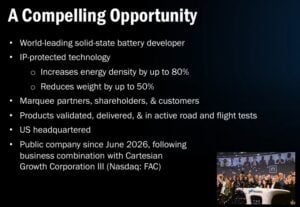
Factorial says its Solstice platform can reach up to 450 Wh/kg and deliver up to 80% higher energy density than traditional lithium-ion batteries.

Higher energy density could allow automakers and other customers to choose between longer range and lighter battery packs.

The company is also working on the manufacturing side. Solstice uses proprietary dry-cathode processing, which Factorial says can reduce manufacturing costs and energy use compared with conventional wet-coating methods.

The platform is designed around several potential advantages:

  • Energy density of up to 450 Wh/kg, according to Factorial
  • Operation at temperatures up to 90°C
  • A sulfide-based all-solid-state electrolyte
  • Dry-cathode processing designed to simplify production
  • Compatibility with parts of existing lithium-ion manufacturing infrastructure

The last point could be particularly important. Battery companies have already invested billions of dollars in lithium-ion factories, so a solid-state technology that can use some existing equipment could potentially reduce the cost and time required to scale.

factorial solid state battery

Factorial Has Already Put Its Batteries to the Test

The company is not starting from a laboratory bench.

Testing with Stellantis

Factorial and Stellantis have been testing FEST® solid-state battery cells in North America. The technology was integrated into a Dodge Charger Daytona prototype as part of the development program.

Stellantis previously reported that Factorial’s 77 Ah FEST cells reached an energy density of 375 Wh/kg over more than 600 cycles.

The cells also demonstrated:

  • Charging from 15% to 90% in 18 minutes
  • Discharge rates of up to 4C
  • Operation from -30°C to 45°C

These results are from testing programs rather than mass-market production, but they show the stage the technology has reached.

Mercedes-Benz pushes range

Mercedes-Benz has also tested Factorial’s technology. A modified EQS equipped with Factorial’s solid-state cells traveled more than 1,200 kilometers, or about 745 miles, on a single charge during a road test.

The test showed why solid-state batteries continue to attract interest from premium automakers. More energy packed into a smaller and lighter battery could make long-range EVs easier to build without simply adding more battery cells.

The U.S. Solid-State Battery Market Is Still Young

Solid-state batteries remain a small commercial market in the U.S., but market researchers expect the sector to expand quickly as automakers move toward pilot production and early commercial applications.

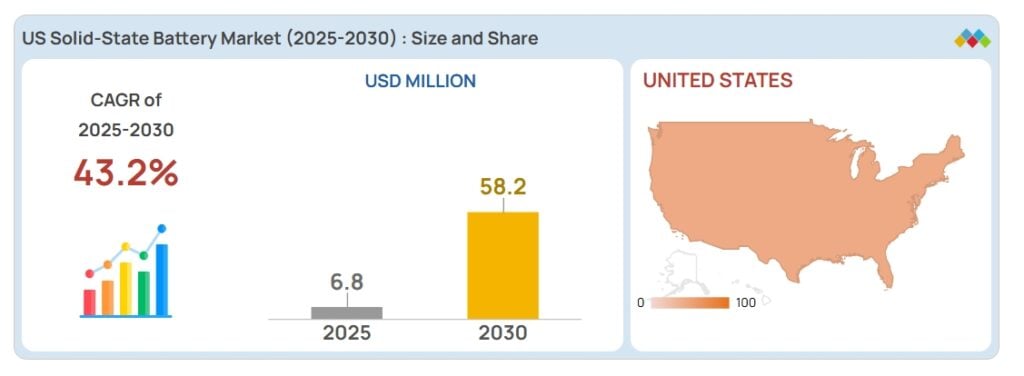
  • According to Market Research Future, the U.S. solid-state battery market was valued at $147.83 billion in 2024. The market is expected to grow from $154.04 billion in 2025 to $232.44 billion by 2035. It represents a 4% CAGR during the period.

    us solid state battery
    Source: Market Research Future

Other forecasts, like Grand View Research, estimate that the U.S. solid-state battery market could reach $4.13 billion by 2033, with a 40.7% CAGR between 2026 and 2033.

The difference between these estimates is significant. It also shows how early the industry is and how much future growth depends on commercialization.

Factorial’s Ecosystem is helping move the market forward

The U.S. is becoming an important testing ground for solid-state batteries because the country has major automakers, battery manufacturers, and government-backed efforts supporting domestic battery production.

Factorial is building its own network around that ecosystem. The company has worked with Mercedes-Benz, Stellantis, Hyundai, and Kia. It also has strategic backing from In-Q-Tel and POSCO Future M.

In July, it signed an MOU with SK On to explore bringing its solid-state battery technology into SK On’s global manufacturing network. This approach could help Factorial avoid building an entirely new manufacturing footprint from scratch.

Solid-State Batteries Could Go Beyond EVs

Electric vehicles remain one of the biggest potential markets for solid-state batteries, but Factorial is looking beyond cars. The company announced its first commercial aerospace order in July and is also developing applications for drones, defense, and robotics.

These markets have different battery requirements from passenger vehicles.

For an electric car, a lighter battery can improve range and efficiency. For a drone or aircraft, reducing battery weight can directly affect how long the vehicle can stay in the air.

Robotics could also become an important market as AI moves from software into physical machines.

Factorial describes this broader opportunity as an emerging “energy layer,” where batteries become a critical part of the infrastructure needed for electric mobility, aerospace and physical AI.

Factorial Moves Into Its Next Phase

Factorial’s Nasdaq debut in June 2026 under the ticker FAC marked another step in its commercialization strategy.

SOLID STATE BATTERY FAC stock factor energy

The partnership does not mean solid-state batteries are ready to replace lithium-ion cells across the market. Manufacturing scale, cost, durability, and supply-chain development remain major hurdles for the industry.

But the direction is becoming clearer.

Factorial has moved from developing battery chemistry toward testing cells in vehicles and other real-world applications. Its latest deal with Mitsui Kinzoku focuses on the next challenge: building a materials and manufacturing system that can support larger-scale production.

Last but not least, for FAC investors, that shift from laboratory performance to manufacturing execution could become one of the most important parts of Factorial’s next stage of growth.

The post Factorial Energy (FAC) Teams Up With Mitsui Kinzoku to Scale Solid-State Batteries appeared first on Carbon Credits.

Biochar Carbon Removal Is Heating Up. Exomad Green and Carbonfuture Lock In 1.1M Tonnes Through 2035

The biochar carbon removal market is moving toward larger, longer-term deals as corporate buyers look for supply they can actually verify and receive. Exomad Green and Carbonfuture are now expanding their partnership to more than 1.1 million tonnes of biochar carbon removal supply.

The additional volume, which includes an allocation already secured for 2026, will be available to corporate buyers through Carbonfuture through 2035. The companies also reaffirmed more than 1.2 million tonnes already contracted for delivery under existing multi-year agreements.

The agreement comes as buyers increasingly focus on delivery records, traceability and independently verified tonnes rather than simply future production promises.

Exomad Green Adds More Biochar Supply

Bolivia-based Exomad Green produces biochar by converting sustainably sourced forestry and sawmill residues through industrial pyrolysis. The company operates facilities in Concepción and Riberalta and is developing another large-scale facility in Guarayos.

  • Its longer-term goal is to reach 1 million tonnes of annual carbon removal capacity. Its biochar carbon removal activity is certified under the Puro Standard’s Biochar Methodology, while Carbonfuture provides digital tracking for selected major agreements.

Exomad Green has also built a substantial delivery record.

The companies began working together in mid-2023, when Carbonfuture facilitated two Exomad Green transactions totaling 30,000 tonnes and 32,000 tonnes. At the time, both deals ranked among the largest biochar carbon removal agreements announced.

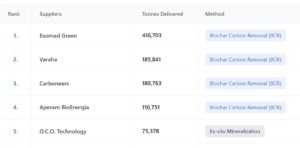
Since then, Exomad Green has delivered more than 400,000 tonnes of durable carbon removal. CDR.fyi data as of August 2026 placed it as the global leader by cumulative delivered durable carbon removal volume.

exomad green
Source: CDR.Fyi

Carbonfuture Connects Buyers With Carbon Removal Projects

Carbonfuture provides digital infrastructure for the carbon removal market. Its digital tools are capable of doing the following tasks:

  • tracks projects and tonnes across the removal lifecycle,
  • supports data transparency
  • third-party verification and credit issuance
  • connecting suppliers with corporate buyers.

The company works with suppliers across five continents and covers several carbon removal methods, including biochar, bioenergy with carbon capture and storage (BECCS), direct air carbon capture and storage (DACCS), and mineralization.

Some of its customers and partners include major climate-focused organizations such as Microsoft, Swiss Re and the World Economic Forum’s First Movers Coalition.

Exomad Green CEO Diego Justiniano said 2026 is putting greater focus on execution in carbon removal. He noted that buyers need reliable, verified tonnes delivered on schedule, not just ambitious capacity plans.

Biochar Demand Is Surging

The timing of the agreement reflects a broader shift in the biochar market.

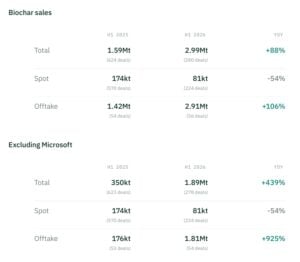
Supercritical data shows that global biochar sales nearly doubled year over year in the first half of 2026, rising from 1.59 million tonnes across 624 deals in H1 2025 to 2.99 million tonnes across 280 deals in H1 2026.

The headline numbers hide an even sharper shift toward long-term procurement:

  • Total biochar sales rose 88% year over year to 2.99 million tonnes.
  • Offtake volume jumped 106% to 2.91 million tonnes.
  • Spot-market volume fell 54% to 81,000 tonnes.
  • Excluding Microsoft, total purchases climbed from 350,000 tonnes to 1.89 million tonnes.
  • Non-Microsoft offtake volume surged from 176,000 tonnes to 1.81 million tonnes, a 925% increase.

The result is a market where buyers are securing supply earlier instead of waiting for spot availability later in the year.

biochar
Source: Supercritical

By July 2026, 81% of high-quality biochar supply had already been committed through offtakes and exclusive agreements. The same threshold was not reached until October 2025. Supercritical also estimates that active enterprise RFPs could claim as much as 70% of the remaining unsold high-quality supply.

This does not mean the world lacks biochar projects. Hundreds of projects are developing capacity, but the amount of supply that meets stringent quality and delivery requirements is considerably smaller.

The research firm said its climate science team has evaluated more than 400 biochar projects, with only 13 passing its assessment.

Biochar Dominates Durable Carbon Removal

Biochar’s position in the broader carbon removal market has strengthened sharply in 2026.

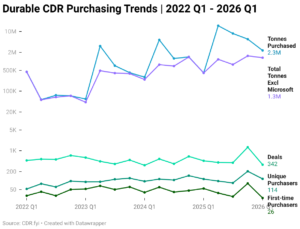
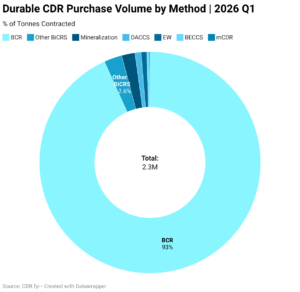
CDR.fyi reported that the durable carbon removal market contracted 2.3 million tonnes in the first quarter, making it the largest Q1 on record. Biochar accounted for 93% of those contracted tonnes.

More than 113 buyers other than Microsoft contracted 1.3 million tonnes, while 145,000 tonnes of durable carbon removal were delivered during the quarter and just over 100,000 tonnes were retired.

durable CDR

Exomad Green was among the leading suppliers. In Q1, it secured a 500,000-tonne agreement with Supercritical and another 105,000 tonnes with undisclosed buyers through Senken, taking its total tonnes sold to just over 2.35 million tonnes at the time.

Production Is Scaling, Too…

Physical biochar production is also expanding rapidly.

  • The International Biochar Initiative’s 2025 Global Biochar Market Report estimates that global biochar production reached 520,810 metric tonnes in 2025, up from 180,150 tonnes in 2023. That represents an approximate 70% compound annual growth rate.
  • The report, based on responses from 930 stakeholders across 96 countries, projects global production could reach 3.5 million tonnes by 2027 and nearly 9.3 million tonnes by 2030.

Asia became the largest producing region in 2025, overtaking North America, while Africa recorded the fastest regional growth among the surveyed markets. South America ranked as the third-largest producing region.

Still, production growth and carbon removal supply are not the same thing. Buyers increasingly want projects with reliable feedstock, consistent production, strong monitoring and verification, and an established record of delivering credits.

That distinction is becoming increasingly important as corporate demand moves toward multi-year contracts.

Why The Deal Matters for Carbon Removal Investors

Exomad Green’s business is about more than selling carbon credits. It turns sawmill waste into biochar and gives it to local farmers and communities for free. The biochar can improve soil while also reducing open burning, air pollution, and fire risk.

For investors, the key point is growth. Exomad Green has already delivered more than 400,000 tonnes of carbon removal. It now has another 1.1 million tonnes available through 2035, on top of more than 1.2 million tonnes already covered by long-term deals.

The deal also shows how the biochar market is changing. Buyers want projects that can produce and deliver carbon removal, not just promise future supply. As demand grows, companies with proven production and long-term contracts could become increasingly important in the carbon removal market.

The post Biochar Carbon Removal Is Heating Up. Exomad Green and Carbonfuture Lock In 1.1M Tonnes Through 2035 appeared first on Carbon Credits.

Can Verra’s New Scope 3 Standard Program Turn Supply Chain Emissions Into Climate Finance?

Can Verra’s New Scope 3 Standard Program Turn Supply Chain Emissions Into Climate Finance?

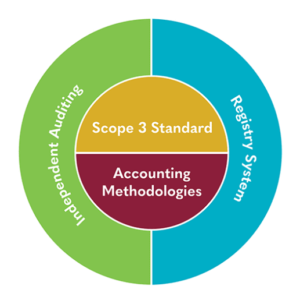
Verra has launched a new Scope 3 Standard (S3S) Program that allows project developers to list climate projects linked to corporate value chains. The program, which started on September 15, helps companies measure, verify, and report emissions reductions.

This is important for projects that impact their supply chains or products. It also creates a new system for issuing Scope 3 Units (S3Us) tied to those outcomes.

The launch happens as companies feel more pressure to cut Scope 3 emissions. These emissions come from activities beyond their direct control. They include suppliers, purchased materials, product use, and other value chain activities.

Verra says Scope 3 emissions typically account for more than 75% of a company’s total carbon footprint. More than 40% of the world’s largest public companies have net-zero targets that include Scope 3 emissions. The new program aims to turn that large emissions challenge into a more structured market for investment in value chain projects.

Project Developers Can Now Join the Program

The first version of the S3S Program is now live, but it is being introduced in stages. At launch, project developers can pipeline-list projects on the Verra Registry using two approved methodologies:

  • S3S-VM0042 Improved Agricultural Land Management
  • S3S-VM0043 CO2 Utilization in Concrete Production

Future updates will allow projects to move through full registration, validation, and verification, after which Verra will issue S3Us.

This phased approach is important. Projects entering the program today are not automatically receiving Scope 3 Units.

Instead, Verra is first creating a pipeline of projects that meet the new framework. The next stages will add the systems needed to verify project results and issue units.

Project proponents can include project developers, companies reporting Scope 3 targets, government entities, and financial institutions. They must demonstrate the right to operate the project and the right to the resulting greenhouse gas reductions or removals.

What Are Scope 3 Units?

Under the new system, an S3U represents one tonne of carbon dioxide equivalent reduced or removed compared with a baseline scenario. Verra writes:

“S3Us represent the climate impact of projects’ emission reduction and removal activities. Companies that can demonstrate a credible value chain connection to the goods or services affected by the project can then request reportable S3Us that are designed for use toward their Scope 3 net zero claims.”

Each unit will also carry information about the project and its climate outcome. This can include the affected product, baseline type, leakage emissions, and reversal risk. The outcomes must be checked by an independent third-party validation and verification body.

This creates an important difference from a conventional carbon credit.

S3Us are designed around a specific company value chain rather than simply representing a tonne of emissions reduced somewhere in the economy. In the future version of the program, a company will need to show a verified connection to the good or service affected by the project. Verra will then use a verified allocation method to issue reportable S3Us to that company.

Those reportable units will be non-transferable between companies. That structure is designed to reduce the risk that several companies claim the same emissions reduction.

Agriculture and Concrete Get First-Mover Status

The two methodologies available at launch target areas with significant emissions reduction potential.

S3S-VM0042 covers improved agricultural land management. The methodology measures emissions reductions and soil carbon removals. It considers practices like reduced tillage, improved fertilizer use, residue management, water management, and cover crops.

Agriculture is key to corporate Scope 3 emissions. Food, agricultural goods, and raw materials often produce significant emissions in supply chains.

The second methodology, S3S-VM0043, covers the use of CO2 in concrete production.

The method can account for projects that use captured or waste CO2 in concrete and permanently embed it in the material. It can also recognize emissions reductions from using less cement, which is important because cement production is highly carbon-intensive.

The two methodologies, therefore, target very different value chains while using the same broader framework.

Why Scope 3 Is So Difficult to Cut

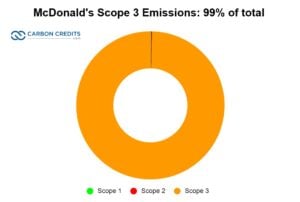
Scope 3 emissions are difficult because companies often have limited direct control over them. A manufacturer can improve the efficiency of its own factories, for example, but it cannot directly control how its suppliers produce raw materials. That makes supply chain projects important. And the fact that these emissions are often the largest, as the case with w2xw below.

McDonald's scope 3 emissions

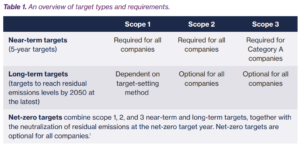
The Science Based Targets initiative (SBTi) requires companies with significant Scope 3 emissions to set targets covering their value chains. Companies with Scope 3 emissions over 40% of total Scope 1, 2, and 3 emissions must set Scope 3 targets. These targets should cover at least 67% of those emissions using supplier engagement or reduction goals.

SBTi’s new Corporate Net-Zero Standard Version 2.0, released in June 2026, focuses more on how companies implement it. This includes operations, value chains, and capital allocation. It requires companies to apply integrity criteria to actions and market instruments used to support target implementation.

SBTi net zero standard v2 requirements

That creates a growing need for tools that can show whether investments in suppliers and value chain projects actually deliver measurable emissions reductions.

Verra Wants to Connect Climate Action With Finance

Verra says the new program is intended to help unlock investment in projects inside corporate value chains. The idea is simple: a company must reduce its Scope 3 emissions. At the same time, project developers need funding to carry out emissions reduction efforts.

A common measurement and verification system can help connect the two.

For example, a food company could support improved farming practices that reduce emissions linked to the agricultural products it purchases. A construction company could invest in a process that uses captured CO2 in materials that enter its supply chain.

The S3S framework aims to measure those results and provide a transparent record of the climate impact. That could create a stronger business case for projects that directly reduce a company’s own value chain emissions.

Verra Scope 3 Standard (S3S) Program
Source: Verra

S3Us Are Not Your Typical Carbon Credits

The launch also comes with an important limitation. An S3U is not simply a standard voluntary carbon credit that any company can buy and use for any purpose.

The program is built around a verified value chain connection. Verra says Version 2 will establish the process for companies to prove that connection and receive reportable S3Us for Scope 3 reporting.

This distinction is important as companies face growing scrutiny over climate claims.

The SBTi’s 2026 net-zero standard stresses that companies should focus on cutting direct emissions. They should use market tools as part of a broader strategy, not as a substitute for reducing their own emissions.

A Digital System Could Lower Project Costs

Verra is also taking a digital-first approach. Project processes will be managed through the Verra Project Hub and Registry.

The organization says streamlined requirements and, where appropriate, more focused verification could allow faster reviews and more frequent issuance at lower cost.

Lower verification costs could make small projects easier. Also, digital records help companies track projects and climate outcomes over time.

Scope 3 Enters a New Market Phase

Verra’s launch comes as companies face growing pressure to reduce and report Scope 3 emissions, which often make up most of their total carbon footprint. The new program gives developers a structured way to finance projects tied directly to corporate supply chains.

The launch is still an early step. Only two methodologies are available, while full registration, verification, and S3U issuance will be added through later updates. The program’s success will depend on whether companies use it at scale and whether projects deliver measurable emissions cuts.

For now, the Scope 3 Standard offers new infrastructure for value-chain climate action. Its long-term value will depend on strong measurement, clear links between companies and projects, and safeguards against double counting or overstated climate claims.

The post Can Verra’s New Scope 3 Standard Program Turn Supply Chain Emissions Into Climate Finance? appeared first on Carbon Credits.
Morgan Stanley Finds Sustainable Funds Beat Traditional Peers With 4.9% Returns in H1 2026

Sustainable funds have become a growing part of the global asset-management market. These funds combine financial investments with environmental, social, and governance (ESG) factors. Their performance can vary widely based on the assets they hold, where they invest, and how fund managers define sustainability.

On September 10, Morgan Stanley said sustainable investment funds delivered higher median returns than traditional funds in the first half of 2026. Their assets under management also reached a record $4.24 trillion.

Sustainable Funds Outperformed Traditional Peers in H1 2026, But Investor Flows Remain Weak

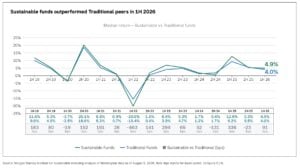
Morgan Stanley Institute for Sustainable Investing’s latest “Sustainable Reality” report, based on Morningstar data covering about 99,000 global funds, found that sustainable funds returned a median of 4.9% in the first six months of 2026. Traditional funds returned 4.0% over the same period.

Sustainable fund assets also grew during the period, reaching a new record. However, the data show that the market still faces challenges. Investor inflows recovered after a difficult 2025, but traditional funds attracted new money at a faster pace.

This means sustainable funds are growing in dollar terms, but their share of the overall fund market has continued to decline.

sustainable funds

AUM Hits Record $4.24 Trillion

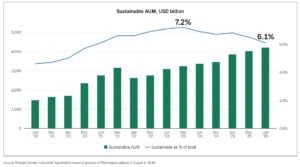
Global sustainable fund AUM increased 4.8% from the end of 2025 to $4.24 trillion at June 30, 2026. Most of that increase came from investment performance rather than new money flowing into the funds.

Sustainable funds now represent 6.1% of total fund assets, down from a peak of 7.2% in December 2023. Morgan Stanley said sustainable AUM has continued to grow steadily since 2022, but traditional funds have consistently recorded stronger net inflows in recent periods.

Some of the key figures from the report include:

  • $4.24 trillion: Sustainable fund AUM at the end of June 2026.
  • 4.8%: Increase in sustainable AUM from December 2025.
  • 6.1%: Sustainable funds’ share of total fund AUM.
  • 4.9%: Median sustainable fund return in H1 2026.
  • 4.0%: Median return for traditional funds.
  • $37.7 billion: Net inflows into sustainable funds during H1.
  • 2.5% vs. 0.9%: Traditional and sustainable fund inflows, respectively, as a percentage of prior year-end AUM.

sustainable funds morgan stanley

Equity Exposure Drove the Performance Gap

The performance advantage was closely linked to asset allocation.

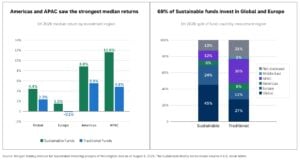
Sustainable funds have a significantly higher allocation to equities, which were the strongest-performing major asset class during the first half. Equities accounted for 56% of sustainable funds, compared with 41% of traditional funds.

  • Sustainable equity funds generated a median return of 9.0%, slightly ahead of the 8.6% return for traditional equity funds. But the picture was very different in fixed income.
  • Sustainable fixed-income funds posted a median return of -1.3%, compared with +1.3% for traditional fixed-income funds.

Morgan Stanley said geography also played a role. About 80% of sustainable fixed-income funds invest globally or in Europe, where both sustainable and traditional fixed-income funds posted negative median returns.

Other asset classes also lagged traditional funds, with sustainable funds delivering a median return of 2.5% compared with 3.0%.

So, the overall outperformance does not necessarily mean that sustainability factors alone drove the higher returns. Morgan Stanley pointed to the mix of assets in sustainable funds, especially their higher exposure to equities, as an important factor.

EARLIER: Morgan Stanley, Citi and Bank of America Exit Net-Zero Alliance: What’s Next for Sustainable Finance?

Americas and APAC Lead Sustainable Fund Outperformance

Sustainable funds also recorded higher median returns than traditional peers across all four major investment regions in H1 2026.

The strongest relative performance came from the Americas and Asia-Pacific, helping offset weaker results from funds focused on Europe and global markets. They nevertheless outperformed their traditional counterparts in those areas as well.

Geographic exposure remains important because sustainable funds are more concentrated in global and European investment mandates. About 69% of sustainable funds invest in global or European markets, compared with roughly 39% of traditional funds.

Europe-domiciled sustainable funds were particularly notable. They generated a median return of 3.9% in H1 2026, compared with 1.8% for traditional funds domiciled in Europe.

Inflows Rebounded, But Momentum Faded in Q2

Investor demand improved substantially from 2025, when sustainable funds experienced $75 billion of net outflows.

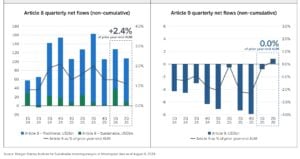
Sustainable funds attracted $37.7 billion in net inflows during H1 2026. But almost all of the recovery came during the first quarter.

Inflows reached $33.5 billion in Q1, before slowing sharply to only $4.2 billion in Q2. Traditional funds, meanwhile, attracted inflows equal to 2.5% of their prior year-end AUM, compared with 0.9% for sustainable funds.

The regional data show an uneven recovery:

  • Europe-domiciled sustainable funds attracted $43.9 billion in H1 inflows, equal to 1.2% of prior year-end AUM.
  • North American sustainable funds attracted $3.1 billion in Q2, ending more than three years of outflows.
  • Asia-domiciled sustainable funds recorded $7.5 billion of outflows, equivalent to 5.5% of prior year-end AUM.

Article 9 Funds Stabilize After Years of Outflows

The report also provides a look at Europe’s SFDR fund classifications.

Article 8 funds recorded $242.2 billion in inflows during H1 2026. However, funds classified as sustainable by Morningstar accounted for only $45.8 billion, or 19%, of those flows.

  • Article 9 funds, meanwhile, recorded a small $0.8 billion inflow in Q2. That followed 10 quarters of outflows dating back to Q4 2023, leaving Article 9 flows roughly flat for the first half of 2026.

article 6

The data suggests that sustainable investing is not disappearing from global markets, but the growth story is becoming more nuanced. Assets continue to rise, performance has been competitive, and flows have returned to positive territory. At the same time, traditional funds are attracting capital at a faster rate, reducing sustainable funds’ share of the overall market.

The first half of 2026 therefore points to a sustainable investment market that is growing in dollar terms while facing a tougher test on investor demand and relative market share.

The post Morgan Stanley Finds Sustainable Funds Beat Traditional Peers With 4.9% Returns in H1 2026 appeared first on Carbon Credits.
Google Signs Record Carbon Removal Deal With Terradot for Brazil Rice Project

Google Signs Record Carbon Removal Deal With Terradot for Brazil Rice Project

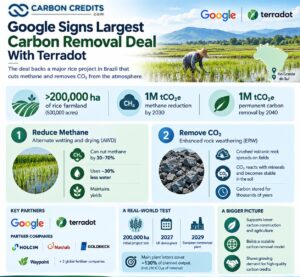
Google has signed its largest carbon removal purchase to date with climate company Terradot, backing a major project in southern Brazil that combines methane reduction from rice farming with permanent carbon removal.

The project will cover more than 200,000 hectares or 500,000 acres of rice farmland in Rio Grande do Sul. It will use two different climate solutions:

  • Alternate wetting and drying (AWD) to reduce methane from rice fields and
  • Enhanced rock weathering (ERW) to remove CO2 from the atmosphere.

Google will purchase 1 million tonnes of CO2e of methane elimination by 2030 and another 1 million tonnes of permanent carbon removal by 2040. The two volumes should not be treated as 2 million tonnes of permanent carbon removal. Methane reduction and carbon dioxide removal have different climate effects and time scales.

Still, the agreement is significant. It is the largest ERW project publicly announced so far and the first project at this scale to combine near-term methane cuts with long-term carbon removal. 

Randy Spock, Head of Carbon Removal, noted:

“We hope this agreement will serve as a template to other buyers, suppliers, and governments aiming to maximize their climate impact. We look forward to continuing to help scale superpollutant elimination and carbon removal in tandem — so we can put an immediate and lasting dent in warming with the urgency the planet demands.”

One Rice Project, Two Climate Solutions

Rice farming is a major source of methane because fields are often kept flooded. Waterlogged soils create conditions that allow methane-producing microbes to thrive.

The first part of the Terradot project uses alternate wetting and drying, which periodically drains rice fields before they are flooded again.

The approach can cut methane emissions by about 30% to 70% without reducing yields, according to the International Rice Research Institute. It can also reduce water use by about 30%. That makes AWD attractive for farmers as well as carbon buyers.

The approach also targets an important source of global methane. The Food and Agriculture Organization estimates that rice cultivation makes up about 8% of methane emissions from humans. In total, agriculture contributes around 40%.

Methane remains in the atmosphere for much less time than CO2, but it has a much stronger warming effect over shorter periods. Google is therefore treating methane reduction as a way to slow near-term warming while the second part of the project builds more permanent climate benefits.

Turning Volcanic Rock Into Carbon Removal

Terradot will also spread crushed volcanic rock across the same rice fields.

Over time, rainwater and soil moisture react with the rock’s minerals. This speeds up a natural process known as enhanced rock weathering, which removes CO2 from the atmosphere and stores the carbon in stable forms. This carbon removal is designed to last for thousands of years.

The approach is attractive because it does not require underground CO2 storage or large industrial capture equipment. Instead, it uses agricultural land as the setting for a natural mineral reaction.

However, ERW still faces challenges. Developers must measure the CO2 removed. They also need to consider emissions from mining and transporting rock. Finally, they must ensure that the carbon stays stored for the required time.

That makes measurement, reporting, and verification especially important as ERW projects become larger.

Brazil Offers ERW a Massive Testing Ground

Southern Brazil is well suited to Terradot’s model. Google says the region has warm and wet conditions that can help speed up rock weathering. Basalt quarries are also located relatively close to the rice-growing areas.

The scale of the project is significant. Brazil has about 1.5 million hectares of rice under cultivation, according to Google. That means the project’s more than 200,000 hectares could eventually cover about 13% of the country’s rice area if the approach is expanded.

Rio Grande do Sul is Brazil’s main rice-producing state. IBGE estimated about 932,870 hectares of rice area for the 2025 crop. The project’s 200,000-plus hectares would, therefore, equal roughly 21% of the state’s rice area, highlighting its potential scale.

The model could eventually be tested in other major rice-producing countries. Google says it is supporting research into how AWD could work across different rice systems worldwide, while Terradot sees Brazil as the first step toward wider expansion.

Google Is Increasing Its Carbon Removal Buying

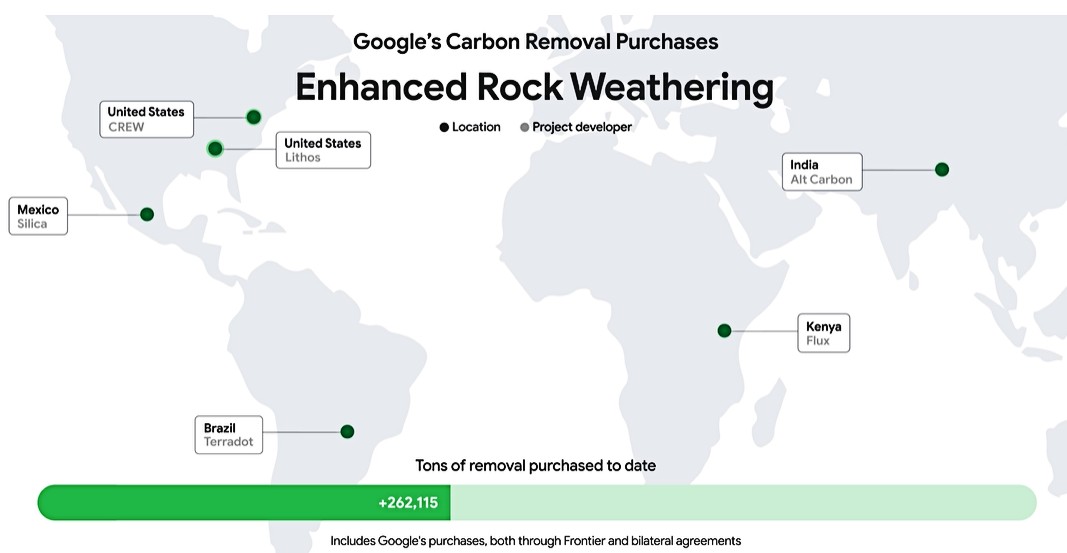
The Terradot agreement builds on Google’s earlier support for ERW. In December 2024, Google agreed to purchase 200,000 tonnes of carbon removal credits from Terradot, to be delivered by the early 2030s. At the time, Google called it the largest ERW deal announced.

The new agreement is five times larger on the permanent carbon removal side, at 1 million tonnes.

Google has also expanded its focus beyond CO2 removal. In March 2026, the company pledged to spend at least $50 million through 2030 on projects targeting methane and other short-lived superpollutants.

Google carbon removal purchases ERW
Source: Google

The Terradot deal brings those two strategies together.

AI Emissions Raise the Stakes for Google

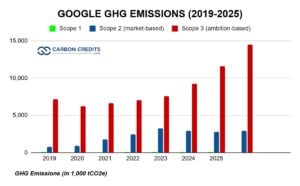
The purchase also comes as Google’s environmental footprint is changing quickly because of AI. Google’s 2026 Environmental Report says its electricity demand rose 37% in 2025, the largest annual increase in the company’s history. At the same time, its supply chain increased 25%, while operational emissions fell 2%.

Google ghg emissions 2019 to 2025

The company also signed agreements for more than 12 GW of new clean energy in 2025, bringing its cumulative clean energy procurement since 2010 to nearly 35 GW.

Google has a goal of reaching net-zero emissions across its operations and value chain by 2030. The company says carbon removal is one part of that strategy, alongside direct emissions reductions, clean energy procurement, and efficiency improvements.

This distinction matters. The Terradot purchase does not remove the need for Google to reduce its own emissions. Instead, durable carbon removal is intended to address residual emissions that remain difficult to eliminate.

Carbon Removal Demand Is Growing, But Delivery Matters

The Google deal arrives as the durable carbon removal market becomes more mature and more selective.

CDR.fyi says durable CDR purchases grew at a 151% compound annual rate between 2021 and 2025, excluding purchases from Microsoft and Frontier. Deliveries have also grown rapidly, but the market remains far smaller than the scale needed for global climate goals.

durable-cdr-purchase-volume-by-method-2026-q1
Source: CDR.fyi

The gap is substantial. The IPCC says climate pathways consistent with limiting warming to 1.5°C or 2°C require large-scale carbon removal later this century. Its assessed pathways include several gigatonnes of annual removal by 2050.

That is far above today’s market. This creates a major opportunity for technologies such as ERW, but also raises the bar for proving that each tonne is real and measurable.

The Cost Challenge Remains

One of the biggest hurdles for ERW is cost. The technology requires mining or sourcing rock, crushing it, and transporting it to farms. Those activities consume energy and can create emissions that must be included in the project’s carbon accounting.

Reuters reported that the cost of Terradot’s removal remains above the $100-per-tonne level often viewed as important for wider market adoption, although the company expects costs to fall as operations scale.

Large purchase agreements can help solve part of this problem. Long-term commitments provide developers with demand visibility, which can support investment in equipment, project development and measurement systems.

Google Terradot carbon removal deal

Can Rice Fields Become the Next Carbon Removal Platform?

The Terradot agreement stands out because it combines short-term methane reduction with long-term carbon removal in the same farming system. AWD can reduce methane emissions quickly. ERW takes longer to remove CO2 but can store carbon for a much longer period.

Google says the model is designed to become a blueprint for other rice-growing regions. For the carbon removal market, however, the deal sends a strong signal.

Large corporate buyers are moving beyond small pilot purchases and backing larger projects designed to deliver millions of tonnes over time.

If Terradot can deliver at the planned scale, the project could help show how agricultural land can become a platform for both methane reduction and durable carbon removal—and provide a model that could be replicated across major rice markets worldwide.

The post Google Signs Record Carbon Removal Deal With Terradot for Brazil Rice Project appeared first on Carbon Credits.

U.S. CFTC Probes Voluntary Carbon Market as Scrutiny of Credit Quality Intensifies

U.S. CFTC Probes Voluntary Carbon Market as Scrutiny of Credit Quality Intensifies

The U.S. Commodity Futures Trading Commission (CFTC) is investigating parts of the voluntary carbon market, according to a Bloomberg report on September 15, 2026. The reported probe is looking at potentially problematic carbon projects and has reached beyond individual developers.

Investigators are seeking information from major U.S.-based carbon registries, validation and certification bodies, and third-party carbon rating firms, according to a person familiar with the matter cited by Bloomberg. The review is also expected to seek information through international channels.

The reported investigation comes as the voluntary carbon market faces continued questions over credit quality, project claims and weak demand.

BloombergNEF data cited in recent Bloomberg reporting shows annual voluntary carbon credit issuance fell 12% in 2025 from its 2021 peak. At the same time, the market is becoming more selective, with buyers increasingly focused on newer and higher-quality credits.

The CFTC has not publicly announced this new investigation. Its previous actions, however, show that the agency already has an enforcement role in voluntary carbon markets.

Probe Covers Projects and Market Gatekeepers

According to Bloomberg, the CFTC’s current review includes credits linked to orphan-well cleanup and projects designed to reduce emissions from deforestation and forest degradation. The focus on registries, validators, certifiers, and ratings firms is also significant.

These organizations play a key role in the voluntary carbon market. Registries record and issue credits. Validation and verification bodies check whether projects follow approved rules and whether claimed emissions reductions have been properly measured. Rating firms then assess the expected quality or risk of credits.

A problem at any point in this chain can affect the credibility of the resulting credit.

The investigation therefore appears broader than checking whether a single project made a false claim. It could look at how project information flows in the market. It can also check if the systems for creating, verifying, and assessing credits are functioning well.

Bloomberg reported that investigators are also considering information obtained under previous administrations, suggesting that the review may draw on earlier regulatory concerns.

CFTC Already Has a Carbon Market Enforcement Record

The CFTC is not new to voluntary carbon markets. In October 2024, it brought its first fraud cases involving voluntary carbon credits. The agency charged former carbon credit developer CEO Kenneth Newcombe with fraud and false or misleading reporting.

The CFTC also settled charges against CQC Impact Investors and its former chief operating officer. The agency found that CQC submitted false and misleading information. This led to the issuance of millions more credits than it should have received. CQC agreed to pay a $1 million civil monetary penalty and cancel or retire credits linked to the misconduct.

The case showed why regulators might step in. Most voluntary carbon credits are traded outside regular exchanges.

The CFTC has anti-fraud authority over the spot voluntary carbon market and broader oversight of derivatives based on carbon credits. CFTC officials have said that fraud in the underlying market can hurt the integrity of carbon credit futures and other derivatives.

Carbon Credit Derivatives Put Regulators on Guard

The CFTC’s role became clearer in 2024 when it issued guidance for exchanges listing voluntary carbon credit derivative contracts.

The guidance covered issues such as whether contracts could be manipulated and whether the underlying credits were sufficiently transparent and verifiable. The agency said high-integrity derivatives depend on credible underlying carbon credits.

However, the CFTC withdrew that guidance in September 2025.

The agency stated that current Commodity Exchange Act rules already cover voluntary carbon credit derivatives. They believe the separate guidance focuses too much on these products. The withdrawal did not remove the CFTC’s underlying regulatory authority over carbon derivatives.

The latest reported probe, therefore, comes after a significant change in how the CFTC approached its carbon market guidance.

The Voluntary Market Has Been Under Pressure

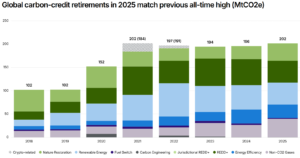
The investigation arrives during a difficult period for the VCM. MSCI estimates that 202 million tonnes of carbon credits were retired in 2025, roughly matching the record level reached in 2021. But demand has been relatively flat for several years, even as the market has shifted toward higher-quality credits.

Global carbon credit retirements
Source: MSCI

The primary carbon credit market was worth about $1.4 billion in 2025, according to MSCI. That value has stayed around the same level for four consecutive years. Yet, investment in future carbon supply is growing.

MSCI estimates that global capital in the carbon credit market hit a record $22 billion in 2025. This is a 72% increase from 2024 and over five times the amount in 2021. Much of that money is being directed toward future credit supply rather than immediate spot market demand.

This split is important. Investors may be willing to finance future projects, but buyers are increasingly selective about which existing credits they retire. That makes confidence in project quality even more important.

The market is also changing in terms of what buyers want.

MSCI found that about 10% of credits retired in 2025 were associated with carbon removals, while around 90% came from emissions reduction projects. Nature-based removals accounted for most removal retirements. Meanwhile, demand for renewable energy credits continued to weaken.

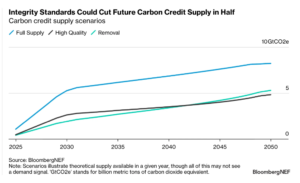
BloombergNEF also expects the market to shift toward higher-quality projects. Its 2025 long-term outlook predicts that global carbon credit supply might increase 20 to 35 times by 2050 from today’s levels.

future carbon credit supply

This growth depends on a market reset toward higher integrity. Its high-quality scenario projects theoretical supply of 2.6 billion tonnes in 2030 and 4.8 billion tonnes in 2050. 

That potential growth depends on trust. A broader regulatory review could affect which project types, methods, and market players can attract capital.

Registries Could Face Deeper Regulatory Scrutiny

Registries are central to the voluntary market because they track project records, credit issuance, ownership, and retirement. If regulators identify weaknesses in the information submitted to registries, the impact could extend beyond individual credits.

Projects may face additional scrutiny, while buyers could demand stronger evidence before purchasing credits. Validation and verification bodies could also face more pressure to show that their processes are consistent and reliable.

That could raise costs for some developers in the short term. But stronger checks could also make it easier for buyers to distinguish credible credits from projects with weak claims.

This matters a lot since the market is still split. It has different standards, methods, registries, and rating systems. CFTC officials have pointed out that fragmentation and missing information hurt price discovery and market trust.

Stronger Oversight Could Reshape Market Trust

A broader regulatory review could raise costs for developers, registries, validators, and ratings firms as they face stronger documentation and verification requirements.

Smaller projects may struggle with the added costs. But tighter oversight could also reduce low-quality credits and increase the value of projects with strong additionality, accurate measurement, and durable climate benefits.

The investigation comes as the voluntary carbon market faces flat demand and growing scrutiny. It does not suggest that all projects or credits in the categories being examined are problematic.

Ultimately, the impact may depend on whether stronger oversight improves data, verification, and transparency. For developers and buyers, the direction is clear: carbon credits will need stronger evidence behind the climate benefits they claim.

The post U.S. CFTC Probes Voluntary Carbon Market as Scrutiny of Credit Quality Intensifies appeared first on Carbon Credits.

Oracle (ORCL) Bets on AI While its Project Jupiter Redefines the Data Center Sustainability Playbook

Oracle (NYSE: ORCL)) latest earnings show how fast AI is changing its cloud business. They also point to a growing challenge. The company needs to build more data centers to meet AI demand. At the same time, it must manage the emissions, electricity, and water that come with that growth. The growth creates a major opportunity for Oracle.

But it also raises a key question: how much power and water will the company need to support the next phase of AI growth?

Oracle’s AI Cloud Surge Powers a Record Quarter

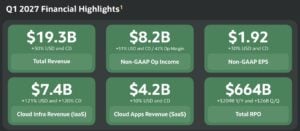
Oracle reported fiscal first-quarter 2027 revenue of $19.3 billion, up 30% from a year earlier. Cloud revenue rose 62% to $11.6 billion. Cloud infrastructure revenue more than doubled, rising 121% to $7.4 billion.

GAAP earnings per share increased 55% to $1.56. Adjusted EPS rose 30% to $1.92. Net income reached $4.76 billion, up 63%.

The company also added more than $30 billion in AI cloud contracts during the quarter. Its remaining performance obligations reached $664 billion.

Additionally, it delivered 850 megawatts of additional data center capacity during the quarter. It said demand for AI training and inference services still exceeds available supply.

oracle Q1 2027
Source: Oracle

ORCL Stock Faces the Cost of AI Expansion

The strong earnings came as Oracle continued to spend heavily on infrastructure. The company invested $28.5 billion in capital expenditures during the first quarter.

Oracle expects fiscal 2027 capital spending to reach about $90 billion to $95 billion. Free cash flow was negative $5 billion in the first quarter as the company continued to expand its cloud infrastructure.

This spending also has a sustainability impact.

Every new data center requires power, cooling systems, construction materials, and water. The efficiency of those systems will affect both Oracle’s environmental footprint and the cost of expanding its cloud business.

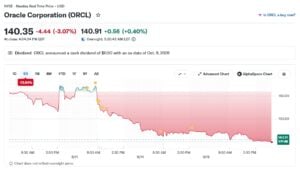
On September 15, ORCL closed at about $140.35, down 3.07% for the session. Oracle shares have gone down 16.5% over five sessions.

oracle stock
Source: Yahoo Finance

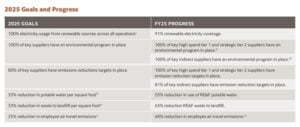
Oracle’s Net-Zero Plan Covers Its Supply Chain

Oracle has set a net-zero emissions target for 2050. It also plans to cut Scope 1, Scope 2, and Scope 3 emissions by 50% from a 2020 baseline by 2030.

The company says it will focus first on direct emissions cuts. It plans to use high-quality carbon offsets for no more than 10% of its base-year emissions that it cannot eliminate directly.

And the Exponential Roadmap Initiative has approved Oracle’s targets.

oracle net zero
Source: Oracle

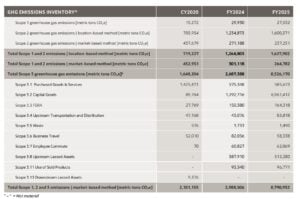
Scope 1, 2, and 3 Data

Oracle’s latest emissions data also shows the impact of its rapid infrastructure growth. It reported 27,532 metric tons of Scope 1 emissions in FY2025. That was down from 29,930 tons in FY2024.

Market-based Scope 2 emissions also fell. They declined to 237,251 tons from 271,188 tons.

However, Scope 3 emissions moved in the opposite direction. They were 8.53 million metric tons in FY2025. That compares with 2.69 million tons in FY2024.

Capital goods made up about 6.96 million tons of the FY2025 Scope 3 total. This category includes emissions linked to infrastructure and equipment purchases.

oracle emissions
Source: Oracle
  • Overall, Oracle reported 8.79 million metric tons of combined Scope 1, 2 and 3 emissions on a market-based basis in FY2025. The figure was 2.99 million tons in FY2024.

The increase shows how infrastructure spending can affect a cloud company’s wider carbon footprint.

Renewable Power Is Expanding

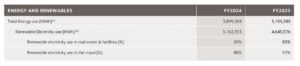
In the sustainability report, renewable electricity covered 92% of electricity used in its cloud operations in FY2025. That was up from 88% in FY2024.

Across its real estate and facilities, renewable electricity coverage reached 85%.

More importantly, Oracle has also set a target to reduce carbon emissions per megawatt of IT capacity by 20% by 2030. As AI workloads require more computing power, improving the emissions intensity of each megawatt will become more important.

oracle renewable
Source: Oracle

Water Is Becoming a Bigger Data Center Issue

Energy gets much of the attention surrounding AI data centers, but water is becoming another important constraint.

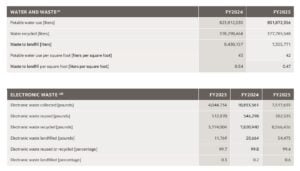
  • It used about 802 million liters of potable water in FY2025, down from approximately 824 million liters in FY2024. The company also recycled about 378 million liters of water during the same year.
  • Potable water use per square foot declined slightly to 42 liters from 43 liters.

Oracle’s sustainability strategy now includes a goal of reducing water use by 50% in water-stressed regions by 2035, relative to a 2025 baseline. The company also aims to reduce carbon emissions per megawatt of IT capacity by 20% by 2030.

The targets are becoming particularly relevant as Oracle develops larger AI-focused facilities.

oracle water
Source: Oracle

Project Jupiter Takes a Different Approach to Water

Oracle’s Project Jupiter in New Mexico provides a closer look at how the company is trying to address the environmental footprint of hyperscale computing.

The 1,400-acre campus in Doña Ana County is being developed as a large-scale AI and cloud data center. Oracle has shifted the project’s power strategy toward Bloom Energy fuel-cell technology, replacing an earlier design based on gas turbines and diesel generators.

It says the fuel-cell system will significantly reduce emissions and water use compared with conventional combustion-based generation.

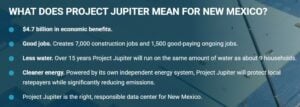
Water is especially important to the project because of conditions in southern New Mexico. Oracle says Project Jupiter will use non-potable water and that, averaged over 15 years including the initial fill, its water use will be equivalent to less than nine single-family homes.

The company is also trying to offset more water than the project itself consumes through local conservation.

oracle project jupiter
Source: Project Jupiter

Oracle Wants to Save More Water Than Jupiter Uses

In August, Oracle also announced a partnership with agricultural technology company Arable to improve irrigation efficiency in the Rio Grande-Bravo watershed.

  • The initiative is expected to conserve approximately 21 million gallons of water annually.
  • This amount is more than 20 times the water required to operate Project Jupiter’s cooling and power systems.

Arable will use field sensors, weather information, and crop data to help farmers make more precise irrigation decisions. Oracle says an independent third party will validate the water savings using a recognized methodology, with validation reports made public.

Oracle has also committed $50 million toward local water and wastewater infrastructure in Doña Ana County.

The approach moves beyond simply reducing data center water consumption. It combines operational efficiency with investment in watershed-level conservation, which could become increasingly relevant as data center construction expands into water-stressed regions.

Expanding a Cleaner Power Mix for Jupiter

Oracle’s sustainability strategy around Project Jupiter also extends to electricity.

Recently, the company issued a request for proposals for 2 gigawatts of new renewable energy capacity in New Mexico, including solar, wind, and geothermal projects. Oracle said the initiative is intended to support Project Jupiter’s goal of achieving 100% carbon-free energy matching by 2031.

As per reports, Oracle is also planning a public environmental dashboard for Project Jupiter. The dashboard is expected to provide information on water use, emissions, heat, air, noise and light once the facility is operational.

It also plans twice-yearly assessments by an independent third party comparing performance against baseline conditions and relevant standards.

For a company expanding its cloud infrastructure at triple-digit rates, greater transparency could become increasingly important.

The Bottom Line: AI Growth Is Raising the Sustainability Stakes

Oracle’s Q1 results demonstrate the scale of the AI infrastructure opportunity. Cloud infrastructure revenue more than doubled, the company’s backlog reached $664 billion, and hundreds of megawatts of additional data center capacity were brought online.

Yet the same expansion is increasing Oracle’s exposure to energy consumption, construction-related emissions, water availability and infrastructure costs.

The company’s sustainability targets therefore sit alongside a much larger business transformation. Oracle is attempting to grow its AI and cloud infrastructure while reducing the emissions intensity of its operations, expanding renewable power and addressing water use at the local watershed level.

For investors watching ORCL, the story is no longer simply about how fast Oracle can build data centers. It is also about how efficiently and sustainably the company can power them.

As AI demand continues to drive Oracle’s cloud growth, energy and water management could become increasingly important measures of how the company’s infrastructure expansion develops over the next decade.

The post Oracle (ORCL) Bets on AI While its Project Jupiter Redefines the Data Center Sustainability Playbook appeared first on Carbon Credits.