Can UK-US Fusion Partnership Turn AI-Powered Research Into Clean Energy?

Can UK-US Fusion Partnership Turn AI-Powered Research Into Clean Energy?
The UK and US are expanding their partnership on fusion energy, with a focus on artificial intelligence (AI), advanced computing and simpler rules for developing fusion plants. The agreements were announced at the Global Fusion Policy Summit in London on September 14, 2026.

The partnership links the UK Atomic Energy Authority (UKAEA) with the US Department of Energy’s Princeton Plasma Physics Laboratory (PPPL). The two countries will also work together on fusion safety and regulation.

The move comes as both countries step up spending on fusion and try to turn decades of research into working power plants.

The UK has committed more than £2.5 billion to fusion over five years. The US has set out a plan aimed at supporting pilot plants and commercial fusion power in the mid-2030s. 

AI Could Speed Up Fusion Research

One part of the partnership will link two advanced computers: the UKAEA’s SUNRISE supercomputer and PPPL’s STELLAR-AI system.

The planned SUNRISE–STELLAR-AI Federation will allow researchers in both countries to train AI models using data from fusion experiments. The goal is to improve reactor designs, better understand plasma, and speed up research.

The UK has committed £45 million to SUNRISE. The system is expected to use about 1.4 megawatts of power and become one of the world’s most powerful computers focused on fusion research. 
UKAEA supercomputing facility
Source: United Kingdom Atomic Energy Authority

Researchers could also use these systems to create digital twins of fusion plants. These virtual models allow engineers to test designs and changes before trying them on real equipment. This could save time and reduce the cost of testing.

The partnership also creates an interesting link between AI and fusion. AI needs large amounts of electricity, while fusion could eventually provide steady, low-carbon power for data centers and other energy-intensive industries.

Both Countries Want Clearer Fusion Rules

The UK and US also want closer cooperation on fusion regulation and safety standards. The two countries said they will work toward rules that reflect the different risks of fusion compared with traditional nuclear fission.

Clear rules matter because fusion plants will require billions of dollars in investment. Developers need to know how projects will be licensed and operated before they can commit large amounts of money.

The UK has already created a dedicated regulatory framework for fusion. It is also developing a Fusion National Policy Statement and a new market framework for future fusion plants.

Minister for Energy, Michael Shanks, stated:

“By strengthening our partnership with the US, we’re accelerating the race to commercial fusion, turning cutting-edge research into economic growth and cementing Britain’s position as a world leader in fusion energy.”

The US is also working to speed up its approval process as private fusion companies move closer to commercial projects. FCDO Minister for the Americas, Chris Elmore, said:

“By bringing together world-leading expertise in fusion, artificial intelligence and advanced computing, we’re helping British businesses and researchers access the investment, knowledge and international partnerships needed to succeed in the industries of the future.”

Britain Bets £1.3 Billion on Its 2040 Fusion Plant

The UK’s main project is STEP Fusion, a prototype power plant planned for West Burton in Nottinghamshire. The plant is expected to begin operating in 2040. It is designed to show that a fusion plant can produce net electricity for the grid and make its own tritium fuel. 

The UK has allocated £1.3 billion for the next stage of STEP. The wider five-year fusion programme also includes £180 million for the LIBRTI programme, which is working on tritium fuel, and £110 million for industry support and commercialization. 
fusion industry global
Source: Fusion Industry Association Report 2025

The UK government estimates the global fusion market could be worth between £3 trillion and £12 trillion by the end of the century.

US Targets Commercial Fusion in the 2030s

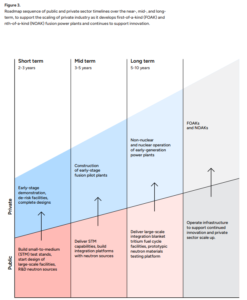
The US has set a faster target. The Department of Energy’s Fusion Science and Technology Roadmap, finalized in June 2026, aims to support pilot plants and commercial fusion power in the mid-2030s. It covers research, technology, infrastructure, skills, and commercial development.

The US plan is also designed to support the growing private fusion industry.

Private companies are developing several different fusion technologies, including magnetic and inertial fusion. The UK-US partnership could help these companies access more research, computing power, and technical expertise.
Department of Energy's Fusion Science and Technology Roadmap
Source: Department of Energy

Tritium Could Be Fusion’s Biggest Fuel Challenge

Fusion works by joining light atoms at extremely high temperatures. This releases energy without burning coal, oil, or gas.

That means fusion does not create CO2 from fuel combustion during operation. It also has a potential advantage over wind and solar: fusion plants could produce power continuously instead of depending on weather.

That makes fusion a possible source of firm, low-carbon electricity for future power grids. But commercial fusion power does not yet exist at scale.

Scientists and engineers still need to solve major challenges. These include keeping the plasma stable, protecting reactor parts from intense radiation, producing enough fuel, and operating reactors reliably for long periods.

  • One of the key problems is tritium, a radioactive form of hydrogen.

Many planned fusion systems will use a mixture of deuterium and tritium as fuel. Future plants therefore need a reliable way to produce and recover tritium during operation.

The UK’s LIBRTI programme is working on this challenge. Its goal is to develop systems that can produce enough tritium to support future fusion reactors. Solving this problem will be important before fusion can become a large commercial energy source.

A New Fusion Industry Is Taking Shape in Britain

The partnership comes as electricity demand is rising from data centers, manufacturing, electric vehicles and other technologies. Renewable energy could provide much of the new clean electricity, but power systems also need reliable generation, storage and stronger grids.

Fusion could eventually work alongside wind and solar by providing steady low-carbon power. It is not a replacement for renewable energy today.

The technology still needs to prove that it can produce electricity reliably and at a competitive cost. For now, the focus is on research, testing, and demonstration projects.

The UK is also working with companies and research groups on materials and other parts needed for future reactors. A separate £2.63 million project involving the University of Birmingham, the Electric Power Research Institute and industry partners will study fusion reactor shielding materials.

Japan’s Kyoto Fusioneering has also committed up to £3 million to Project ALBION, which supports materials development for STEP. These projects can help build a supply chain before commercial fusion plants are ready.

The Race Now Moves From the Lab to the Grid

Fusion has spent decades in the research stage. That is now starting to change. Fusion is moving from basic research toward commercial development.
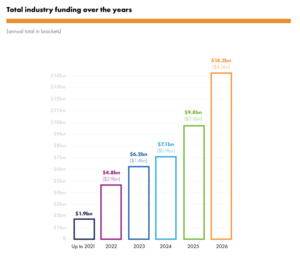
Total industry funding over the years
Source: Fusion Industry Association.

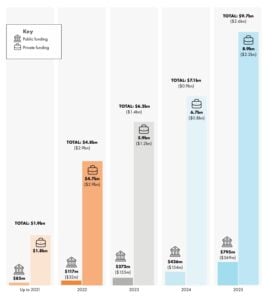
Private fusion companies have raised a cumulative total of $14.24 billion globally as of July 2026, according to the Fusion Industry Association. Private funding has grown sevenfold since 2021, showing how quickly investor interest is increasing.

Governments are also putting more money into pilot plants, while private companies are raising capital to develop commercial systems. 

The UK-US partnership tackles several of the main barriers at once. AI and supercomputers could speed up research. Shared rules could make future projects easier to approve. Cooperation could also help companies develop common technologies and standards.

For the energy transition, the potential is large: a reliable, low-carbon power source that could eventually help meet rising electricity demand from AI, industry, and electrification.

The next milestone will be turning these partnerships and research programmes into working pilot plants—and proving that fusion can move from the laboratory to the power grid. 

The post Can UK-US Fusion Partnership Turn AI-Powered Research Into Clean Energy? appeared first on Carbon Credits.
FedEx (FDX) Locks In 20 Million Gallons of SAF Across U.S. Air Network

FedEx is expanding its sustainable aviation fuel (SAF) procurement as the air-cargo company works to reduce emissions from the part of its business that produces the largest share of its direct carbon footprint.

The company announced on September 15 that new agreements are projected to secure more than 20 million gallons of neat SAF through 2027. The agreements cover five U.S. airports:

  • Newark Liberty International Airport
  • Oakland International Airport
  • Miami International Airport
  • John F. Kennedy International Airport
  • Dallas-Fort Worth International Airport

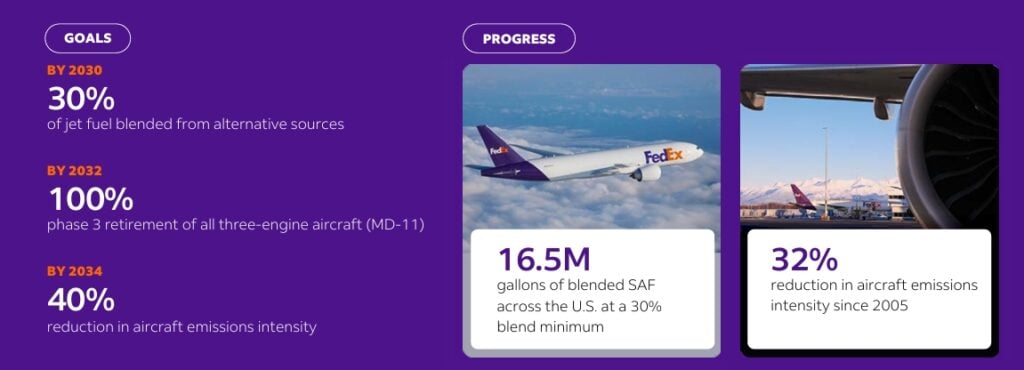
Depending on the airport, the fuel will be supplied at blend ratios ranging from 30% to 50%. FedEx said the agreements build on about 5 million gallons of neat SAF secured in 2025, which supported the deployment of 16.5 million gallons of blended SAF across five U.S. airports.

FedEx’s 2040 Climate Target

The expansion comes as FedEx works toward its goal of carbon-neutral operations by 2040. The target covers Scope 1 and Scope 2 emissions from its operations as well as Scope 3 emissions associated with contracted transportation.

It also includes SAF, aircraft modernization, and operational efficiency as part of its wider climate strategy.

Karen Blanks Ellis, chief sustainability officer and vice president of Environmental Affairs at FedEx, said:

“SAF is one of the most impactful decarbonization solutions available to aviation today and an important part of our approach to reducing emissions. For the market to grow, supply needs to be reliable, affordable, and sustainable. Expanding our procurement allows us to employ more SAF in our network while bolstering the demand for greater production and scale.”

Aviation Drives FedEx’s Emissions

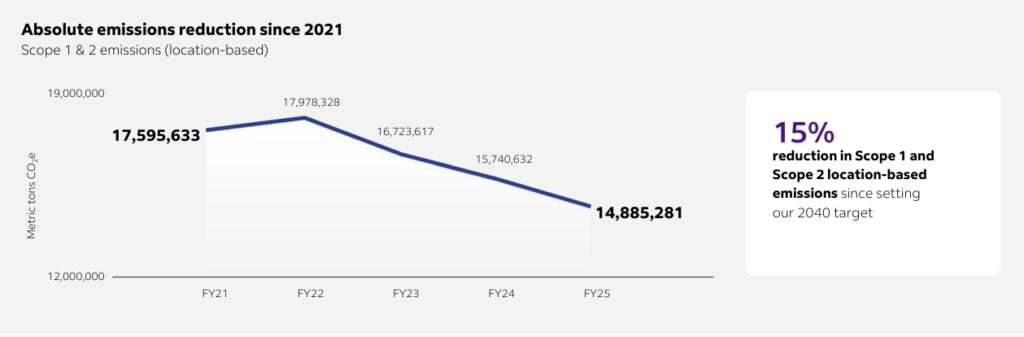
FedEx reported 13.93 million metric tons of CO2e in Scope 1 emissions for FY2025. These direct emissions come mainly from aircraft, vehicles, and facilities.

The company reported another 952,744 metric tons of Scope 2 emissions, primarily from purchased electricity. Its reported Scope 3 emissions totaled 14.88 million metric tons of CO2e.

  • Together, the three categories totaled 29.76 million metric tons of reported emissions in FY2025. FedEx notes that its Scope 3 inventory continues to expand, so the figure does not represent every possible Scope 3 category.
fedex emissions
Source: FedEx

Aviation remains the biggest contributor to direct emissions. Owned aircraft accounted for about 79% of FedEx’s Scope 1 footprint, while aviation fuel use generated roughly 11 million metric tons of CO2e during the year.

emissions
Source: FedEx

The company also reports emissions from conventional air pollutants. In 2025, its operations produced about 71,432 metric tons of nitrogen oxides (NOx), 10,773 metric tons of sulfur oxides (SOx), and 640 metric tons of particulate matter (PM10). These pollutants are separate from FedEx’s greenhouse-gas emissions inventory.

Fleet Modernization Cuts Fuel Use

FedEx is not relying on SAF alone to reduce aviation emissions. The company is replacing older aircraft with newer, more fuel-efficient models and optimizing fleet operations. It operates nearly 700 aircraft and is retiring less-efficient three-engine aircraft. The company plans to complete that retirement by 2032.

Aircraft modernization avoided approximately 1.15 million metric tons of CO2e in FY2025, according to FedEx’s 2026 Corporate Responsibility Report. The company also saved more than 120 million gallons of jet fuel through aircraft modernization and related efficiency measures.

Those savings have also reduced operating costs. FedEx estimates that its aircraft modernization program saved about $284 million in fuel costs during FY2025.

Its Fuel Sense program provides another source of efficiency. The program uses operational improvements, flight planning, and technology to reduce fuel consumption across the air network.

To sum up, FedEx has reduced aircraft emissions intensity by 32% from its 2005 baseline and now targets a 40% reduction by 2034.

SAF Takes a Larger Role

The latest agreements increase the scale of SAF in FedEx’s U.S. network while addressing one of the industry’s biggest challenges: supply.

As mentioned before, the new contracts will secure more than 20 million gallons of neat SAF through 2027. Because the fuel will be blended before use, more finished blended fuel will enter the network.

FedEx has set a target of sourcing 30% of its jet fuel as blended fuel from alternative sources by 2030.

SAF FedEX

The company has already expanded SAF use at several major hubs. Its 2025 agreements supported SAF deployment at airports including Los Angeles, Chicago O’Hare, Miami, Dallas Fort Worth, and New York-JFK. FedEx also secured more than 3 million gallons of blended SAF from Neste for Los Angeles.

The company says SAF supply needs to become more reliable, affordable, and sustainable for the market to scale. Its latest agreements increase demand while allowing FedEx to build SAF into regular network operations rather than treating it only as a pilot project.

For FedEx, the latest SAF agreements add another piece to a broader effort to decarbonize a logistics network that depends heavily on aviation. New aircraft can reduce fuel consumption, operational improvements can lower fuel demand, and SAF can replace part of the fossil jet fuel used across the network.

The challenge is scaling all three at the same time. FedEx’s latest agreements show that SAF is moving from limited deployments toward a more significant role in the company’s long-term aviation emissions strategy.

Now let’s look inside the SAF market in the content below:

In the U.S. SAF Market Is Growing, But Supply Still Trails Demand

FedEx’s latest agreements come as the sustainable aviation fuel market expands in the U.S. and globally, although production remains a small fraction of aviation fuel demand.

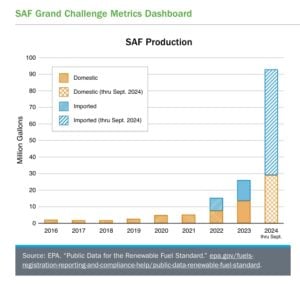
DOE data revealed that U.S. production has increased sharply, but actual output remains well below that target. Federal agencies reported that domestic SAF production reached 30 million gallons in the first three quarters of 2024, up from 5 million gallons in 2021.

US SAF production

The government is targeting 3 billion gallons of domestic SAF production a year by 2030 and 35 billion gallons by 2050. The 2030 target would equal about 10% of projected U.S. jet-fuel demand.

saf
Source: Source data for the future potential volumes will be available in a forthcoming ASCENT 01 publication. Brandt, K; Wolcott, M. (2024). RD data source: U.S. Energy Information Administration. SAF data source: EPA. “Public Data for the Renewable Fuel Standard.”

More recent EIA data also shows the U.S. is becoming an important supplier to international markets. In the second half of 2025, the U.S. exported nearly 50,000 barrels per day of renewable diesel and other biofuels, a category that includes SAF. Those exports represented about 20% of combined production in the category, with Canada and Europe taking most of the volumes.

Global SAF Supply Remains Small

Globally, SAF production is growing but has not kept pace with the industry’s ambitions.

The International Air Transport Association (IATA) estimates that global SAF production reached about 1.9 million metric tons in 2025, roughly double 2024 production. That still represented only about 0.6% of total jet-fuel consumption. IATA expects production to rise to approximately 2.4 million metric tons in 2026, but that would cover only about 0.8% of aviation fuel demand.

  • The gap between production and potential demand remains significant. IATA estimates that airlines will spend about $4.3 billion on SAF in 2026, even though the fuel will supply less than 1% of global aviation fuel needs.

IATA SAF

For FedEx, the latest commitment to secure more than 20 million gallons of neat SAF through 2027 fits into this broader market expansion. The company is effectively locking in a portion of future supply while SAF production capacity continues to scale.

The U.S. has the production targets and project pipeline to become a major SAF market, but the gap between announced capacity and actual production remains important. Globally, the same issue is even more pronounced: SAF output is growing rapidly from a small base, while aviation fuel demand remains measured in hundreds of millions of tonnes.

The post FedEx (FDX) Locks In 20 Million Gallons of SAF Across U.S. Air Network appeared first on Carbon Credits.
Vateris Secures €50M in Offtake Deals for Carbon-Negative Minerals

Vateris Secures €50M in Offtake Deals for Carbon-Negative Minerals

UK climate technology company Vateris has secured binding offtake agreements and letters of intent worth more than €50 million in annual turnover with six international construction and fertilizer companies. The deals include two products that turn industrial carbon dioxide (CO2) into minerals.

The first is GypCarb, a carbon-negative calcium carbonate used in construction. The second is sulphate of potash (SOP), a high-purity fertilizer. The partners include Holcim, Marshalls and Goldbeck for GypCarb, while Waypoint and two unnamed global fertilizer companies have committed to SOP.

The agreements connect binding volumes from a UK demonstration plant planned for 2027. They also include letters of intent for larger volumes from a European commercial plant planned for 2029.

The main plant letters cover about 130% of its planned output, according to Vateris. This deal is important because it gives a carbon utilization technology a potential customer base before full commercial-scale production begins.

Turning Industrial CO₂ Into Commercial Materials

Vateris, formerly known as Concrete4Change, uses a process designed to capture CO2 from industrial flue gas and convert it into useful mineral products. Its first product, GypCarb, is an engineered form of vaterite-based calcium carbonate.

The company says the product permanently locks 44% of CO2 by mass into the mineral and is designed as a drop-in additive for cement and concrete.

The process uses calcium from gypsum and converts it, along with captured CO2, into calcium carbonate. The remaining sulphate is used to make high-purity SOP fertilizer. This creates two products from the same process while storing captured carbon in minerals.

That is different from conventional carbon capture and storage, where CO2 is captured and then transported to an underground storage site. Vateris instead uses carbon capture and utilization (CCU) to turn the carbon into materials that can be used commercially.

Vateris carbon capture

GypCarb Targets One of Industry’s Biggest Emitters

The construction industry is a major target because cement and concrete have large carbon footprints. The International Energy Agency reports that CO2 emissions from cement production are still higher than in 2015. The sector must cut emissions faster to meet net-zero goals.

The IEA points to greater use of alternative materials, improved efficiency, and carbon capture among the solutions. GypCarb is designed to address two parts of this problem.

First, the product stores captured CO2 permanently in mineral form. Second, Vateris says its reactive calcium carbonate can improve concrete performance and reduce the amount of cement needed. 

The company reported strong results from testing with Heidelberg Materials. One trial showed a 40% increase in one-day compressive strength using a small amount of GypCarb. Further testing is aimed at reducing cement content while maintaining performance.

With cement production responsible for significant industrial emissions, materials that can reduce cement use while storing CO2 could offer a second source of emissions savings.

Construction Companies Are Already Signing Up

The new agreements provide early commercial validation for the technology. Holcim, Marshalls and Goldbeck have committed to GypCarb for cement, concrete and other construction applications.

Vateris partners
Source: Vateris

Goldbeck has been working with Vateris on integrating the product into its precast concrete operations. The companies say the technology has shown potential to reduce cement use while maintaining early strength.

First GypCarb deliveries to Goldbeck are targeted for late 2027. This matters because industrial climate technologies often struggle to move from pilot testing to commercial markets.

An offtake agreement can give a technology developer a clearer route to revenue while giving customers early access to a new material. However, the €50 million figure should be read carefully.

It represents annual turnover associated with the agreements and letters of intent, not cash already received by Vateris. The binding agreements cover demonstration-plant volumes, while the larger main-plant commitments are currently non-binding letters of intent.

Fertilizer Gives Captured CO₂ a Second Market

Vateris is also targeting agriculture through SOP. Sulfate of potash is a potassium and sulphur fertilizer used in higher-value crops. The company plans to produce a high-purity version using the sulphate left over from its carbon mineralization process.

This gives the company a second commercial market and reduces its reliance on construction materials. The timing could also be favorable for fertilizer supply chains.

The European Commission says the EU remains dependent on imports for mineral fertilizers and key raw materials. It estimates that the bloc imports about 40% of its potassium fertilizers.

That dependence has become more important as geopolitical disruptions have affected global fertilizer and energy markets. A European source of SOP made from industrial waste streams could thus offer both carbon benefits and greater supply resilience.

Europe’s Carbon Management Market Is Expanding

Vateris is also entering a wider European push to build carbon management infrastructure.

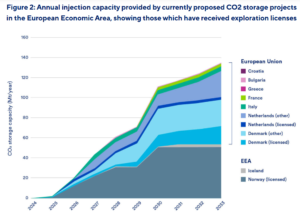
The EU has set a target of at least 50 million tonnes of annual CO2 injection capacity by 2030 for permanent geological storage. The European Commission expects around 280 million tonnes of CO2 to need capture by 2040 and around 450 million tonnes by 2050 to support climate neutrality.

EU Annual injection capacity
Source: Clean Air Task Force

Those targets focus mainly on carbon capture and storage, but they also support a broader market for carbon management, including technologies that use captured CO2.

The EU is funding carbon capture, utilization, and storage through its Innovation Fund, including projects in cement, chemicals, and other hard-to-abate industries. Vateris could benefit from that growing market if it can show that its process works at much larger industrial scale.

From Pilot Plant to Commercial Scale

Vateris raised its total funding to $10 million after a financing round involving Holcim Maqer Ventures and Kiilto Ventures in April 2026. The company has since shifted its focus from pilot validation toward industrial scale-up.

Its planned UK demonstration plant is expected to begin production in 2027. A larger European first-of-a-kind commercial plant is targeted for 2029. The current offtake agreements are designed to support this transition.

Vateris says the demo plant will show the technology works at a commercial scale. The main plant will supply larger volumes for construction and agricultural customers.

  • The new agreements show a strong signal: potential customer demand is already higher than the planned output for Vateris’ first full-scale European plant.

The letters of intent cover about 130% of the plant’s expected production, according to the company. That is encouraging, but it is not yet guaranteed revenue.

Letters of intent aren’t binding purchase agreements. The commercial plant still needs financing, construction, and a successful technical scale-up. The demonstration plant will, therefore, be a critical milestone.

Vateris Carbon Negative Minerals

If Vateris proves it can turn industrial CO2 into cost-effective construction and fertilizer products, it could build a new business model around carbon use.

The Next Test Is Turning CO₂ Into Revenue

The broader significance of Vateris is its attempt to change the role of captured CO2. The company isn’t just viewing industrial CO2 as waste to bury. Instead, it aims to convert it into a raw material for products that already have established markets.

The new agreements show that large industrial companies are willing to explore this model. The next test is scale.

A successful demonstration plant in 2027 could help turn the more than €50 million annual commercial pipeline into actual sales and support the larger European plant planned for 2029.

For the carbon market, the story is also a reminder that decarbonization will not rely on one solution. Permanent storage, carbon removals, carbon capture, and carbon utilization can each play different roles.

Vateris is betting that one of those roles will be to turn industrial emissions into materials that Europe already needs.

The post Vateris Secures €50M in Offtake Deals for Carbon-Negative Minerals appeared first on Carbon Credits.
BlackRock-Backed Skyborn Secures $2.4B for Major German Offshore Wind Farm

BlackRock-Backed Skyborn Secures $2.4B for Major German Offshore Wind Farm

Skyborn Renewables has reached financial close on the Gennaker offshore wind farm, securing a €2.1 billion financing package, or roughly $2.4 billion, for one of Germany’s largest new renewable energy projects. The project, located in the German Baltic Sea, will have up to 976.5 megawatts (MW) of capacity. More than €3 billion in total investment is expected to be mobilized.

Gennaker will start commercial operations by the end of 2028. It aims to generate enough electricity for about 1 million German households.

The financing comes from 16 commercial lenders and the European Investment Bank (EIB). The EIB previously approved up to €700 million for the project, whose total cost was estimated at about €3.1 billion.

Nicola Beer, Vice-President of the European Investment Bank (EIB), noted:

“Gennaker shows Europe turning its clean‑energy goals into real benefits for people. Built off the coast of Mecklenburg‑Western Pomerania, where winds are strong and reliable, this wind farm will help Germany produce more of its own power and lower dependence on imported energy. Once running, it will supply clean electricity to around one million homes and businesses across the country, helping to bring down energy bills from Schwerin to Munich.”

The deal is also significant for BlackRock. Skyborn is a portfolio company of Global Infrastructure Partners (GIP), which has been part of BlackRock since it completed its acquisition of GIP in October 2024.

Gennaker Secures €2.1B to Move Into Construction

Financial close means the major financing, supply, power sales, and ownership agreements are now in place. Skyborn developed Gennaker from the ground up and will lead construction management and long-term asset management.

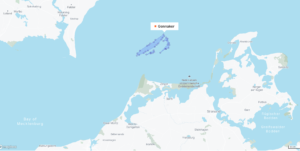
The project is located about 15 kilometers north of the Fischland-Darß-Zingst peninsula in Mecklenburg-Western Pomerania. Once complete, its nearly 1 GW capacity will make it the largest offshore wind farm in Germany’s Baltic Sea.

The wind project secured its construction and operations permit in December 2025. Major supply and installation contracts were also signed for foundations, cables, and wind turbines.

Siemens Gamesa is supplying the turbines, while other contractors include EEW, Seaway 7, Boskalis, and Fred. Olsen Windcarrier. Stadtwerke München, or SWM, is also now a 25% equity partner in the project, leaving Skyborn with a 75% stake.

Amazon and Uniper Lock In 700 MW of Power

Gennaker has also secured major buyers for its electricity. In June, Amazon signed a 600 MW power purchase agreement (PPA) covering about 61% of the project’s total capacity. Skyborn and Amazon described it as the largest single PPA ever signed in Germany.

The long-term contract was an important step because it gives the project predictable revenue from electricity sales.

Uniper also signed a 100 MW PPA with Skyborn. The agreement runs for an initial 10 years after commercial operation, with an option to extend. Together, the two contracts cover 700 MW, or roughly 72% of Gennaker’s maximum capacity.

These agreements illustrate how PPAs are becoming an important financing tool for large renewable projects. Long-term electricity contracts can provide revenue visibility that helps banks assess the project’s ability to repay debt.

Germany Needs Gennaker and Many More Like It

Gennaker arrives as Germany tries to expand offshore wind rapidly. The country has set a target of at least 30 GW of offshore wind capacity by 2030, 40 GW by 2035 and 70 GW by 2045.

Germany offshore wind capacity additions 2034

The country is also targeting 80% renewable electricity by 2030. Gennaker’s 976.5 MW would equal about 3.3% of Germany’s 2030 offshore wind target once fully operational.

The project will, therefore, make a meaningful contribution, but Germany will need many more large projects to reach its targets.

Moreover, offshore development remains challenging. Germany postponed offshore wind auctions originally planned for 2026 until 2027 as part of changes to its offshore wind development plan. The government said the delay would not affect the long-term 70 GW target for 2045.

offshore wind energy Germany map

A Large Bet on Energy Security

Offshore wind is also becoming part of Germany’s energy security strategy. The country is trying to reduce its dependence on imported fossil fuels while increasing domestic electricity production.

Gennaker will add nearly 1 GW of renewable capacity in the Baltic Sea and provide power to the German grid. That can help reduce the need for fossil fuel generation when wind conditions allow.

The project will also support Germany’s industrial base. It will involve European manufacturers, marine contractors, and others in the offshore wind supply chain. The EIB expects the project to create economic value in Mecklenburg-Western Pomerania, where Gennaker is being developed.

Gennaker location
Source: Skyborn

Europe’s Offshore Wind Investment Is Accelerating

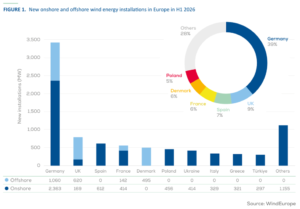
Gennaker is part of a broader recovery in European offshore wind investment. Europe had 40.9 GW of offshore wind capacity by the end of June 2026, after adding 2.3 GW in the first half of the year.

Governments also awarded 8.4 GW of offshore wind capacity through auctions during the period. Germany led additions with 3.4 GW.

Investment is picking up as well. Europe raised €9 billion for new wind projects in H1 2026, including about €0.6 billion for offshore wind. In 2025, six large offshore projects reached final investment decisions, representing 5.6 GW and €22 billion of investment.

European offshore wind installations H1 2026
Source: WindEurope

The longer-term opportunity is much larger. Nine North Sea countries signed a 2026 Investment Pact targeting 15 GW of new offshore wind each year from 2031 to 2040, with industry estimating up to €1 trillion in related economic activity.

However, investment still faces challenges. Grid capacity, permitting, supply chain constraints, and higher project costs remain major barriers. That makes successful financings such as Gennaker important signals that Europe’s offshore wind market can still attract large-scale capital.

Offshore Wind Has a Direct Climate Benefit

Wind power produces electricity without the direct CO2 emissions associated with coal and natural gas generation. Replacing fossil fuel generation with renewable electricity can therefore lower power sector emissions, depending on the generation it displaces.

However, Gennaker should not be described as a carbon credit project. The wind farm will generate renewable electricity rather than voluntary carbon credits. Its climate value comes from replacing carbon-heavy electricity. It also supplies low-carbon power to the grid and contracted customers.

This distinction is important as demand for renewable energy grows alongside carbon markets.

Companies such as Amazon are increasingly using long-term PPAs to secure renewable electricity for their operations and support their emissions goals. However, a renewable energy PPA is not the same as a carbon credit purchase.

BlackRock Expands Its Renewable Infrastructure Footprint

The project also fits into a larger trend in infrastructure investment. BlackRock completed its acquisition of GIP in October 2024, creating a much larger infrastructure investment platform. At completion, the combined platform had about $170 billion in assets under management and more than 300 active investments.

GIP invests across energy, transport, digital infrastructure, and other sectors. Offshore wind matches that strategy. Projects need a lot of upfront money, but they can bring in steady income from power sales over time.

Gennaker’s financing structure shows how public and private capital can work together. Commercial banks provide most of the debt, while the EIB supports the project as a major European climate and infrastructure investment.

A Nearly 1 GW Bet on Germany’s Clean Power Future

Gennaker is moving from development to construction. For Germany, the project adds a significant amount of new offshore wind capacity as the country works toward its 30 GW target for 2030.

Skyborn, backed by BlackRock, shows how to finance big renewable projects. They combine institutional capital, bank debt, equity, and long-term power contracts.

Gennaker points out an important fact for the energy transition: to decarbonize electricity, we need billions of dollars for infrastructure first. Only then will the emissions benefits reach the grid. Projects like Gennaker will become increasingly important to Germany’s effort to expand clean power while reducing its reliance on fossil fuels.

The post BlackRock-Backed Skyborn Secures $2.4B for Major German Offshore Wind Farm appeared first on Carbon Credits.
Google Targets Rice Methane Emissions in India with 1 Million Carbon Credits

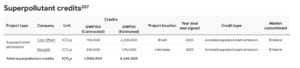
Google is expanding its focus on methane emissions with a new agreement to purchase 1 million carbon credits from Mitti Labs, a climate technology startup working with smallholder rice farmers in India.

The four-year agreement will support the rollout of water-saving irrigation practices across more than 100,000 hectares of rice farms by 2030. The program is expected to involve more than 70,000 farmers and reduce methane emissions from rice cultivation while cutting water use.

The deal is Google’s largest superpollutant elimination agreement to date. It also adds to the technology giant’s growing carbon removal strategy, which includes investments in durable carbon removal, nature-based projects and solutions targeting gases other than CO₂.

Why Methane Matters for Climate Action

Methane is particularly important because it has a much stronger warming effect than CO₂ over shorter time periods.

The gas remains in the atmosphere for roughly a decade before breaking down. As a result, reducing methane emissions can slow near-term warming more quickly than cutting emissions of longer-lived greenhouse gases alone.

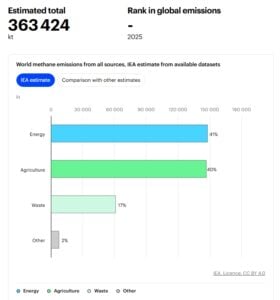
Agriculture is one of the largest sources of human-caused methane, with livestock and rice cultivation among the key contributors.

methane emissions

Rice Farming Adds to Water Stress

Rice cultivation is a major source of agricultural methane.

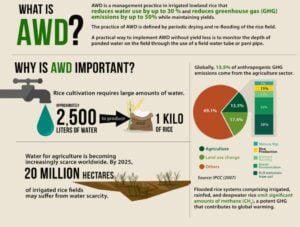
Much of the crop is grown in regions where water resources are already under pressure. Continuous flooding can require significant amounts of irrigation water, adding another challenge for farmers and local water systems.

methane emissions AWD RICE Emissions
Source: International Rice Research Institute

How Mitti Labs Is Reducing Rice Methane Emissions

Rice cultivation is a major source of human-caused methane emissions. Traditional rice farming often keeps fields continuously flooded. Under these oxygen-poor conditions, microbes in the soil produce methane, which then escapes into the atmosphere.

Mitti Labs is addressing this problem through a technique known as Alternate Wetting and Drying, or AWD.

Instead of keeping rice fields flooded throughout the growing season, farmers periodically drain the fields before reflooding them. This changes the conditions in the soil and limits methane production.

According to Mitti Labs, AWD can:

  • Cut methane emissions from rice fields by up to 50%.
  • Reduce irrigation water use by close to 40%.
  • Maintain rice yields when properly implemented.

The approach therefore offers two benefits at the same time. Farmers can reduce the amount of water needed to grow rice while also lowering emissions from their fields.

For Google, the project provides a way to address a potent greenhouse gas while supporting agricultural communities.

3 Million Tonnes of CO₂ Savings

Mitti Labs says its program could save about 1.5 trillion liters of water as AWD expands across the targeted farmland. The company compares the volume with roughly three years of Bengaluru’s annual water supply.

The climate impact is also significant. The company estimates that the program could eliminate the equivalent of 3 million tonnes of CO₂ over 20 years. Using the conventional 100-year global warming potential approach, the impact is equivalent to about 1 million tonnes of CO₂e.

The different figures reflect the way methane is measured over different time horizons rather than a change in the underlying emissions reduction.

Mitti Labs’ Satellite Technology Helps Verify Results

Scaling AWD across thousands of small farms presents a measurement challenge. Farmers operate individual plots, and field conditions can change throughout the growing season.

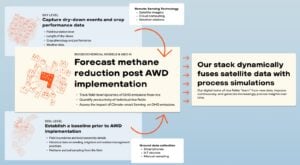
Mitti Labs uses satellite technology and field data to monitor these changes.

  • Its GeoAI platform combines satellite radar imagery with information collected directly from farms. The system can track factors such as flooding, soil moisture, and crop conditions at the individual field level.

The company developed the technology with support from NASA and uses remote sensing to monitor large agricultural areas without relying entirely on physical inspections.

This is important for carbon markets because buyers need evidence that projects are actually delivering the claimed emissions reductions.

Mitti Labs combines its satellite-based monitoring with on-the-ground data and farmer engagement. The approach is designed to verify whether farmers are adopting AWD and whether the changes are producing the expected environmental benefits.

                                             Mitti Labs next-gen dMRV

mitti labs dmrv
Source: Mitti Labs

Methane Credits Get Sylvera A Rating

The company says its methane credits have received an A rating from carbon ratings agency Sylvera, reflecting the strength of its implementation and measurement approach.

Google Builds a Broader Superpollutant Strategy

The Mitti Labs agreement is part of a wider shift in Google’s climate strategy.

  • The company has increasingly looked beyond conventional CO₂ removal to gases that can produce significant near-term warming. In 2025, Google contracted for 1 million tonnes of superpollutant credits
  • It also announced plans to spend at least $50 million through 2030 on projects targeting methane, fluorinated gases and other non-CO₂ greenhouse gases.

google carbon removal

Google has also worked on methane monitoring for more than a decade.

Its efforts have included partnerships focused on identifying methane leaks, supporting satellite-based monitoring and backing the development of artificial intelligence tools that can detect methane emissions.

The strategy reflects a broader recognition that climate action does not have to rely on one type of solution.

Reducing methane can deliver relatively rapid climate benefits, while removing CO₂ from the atmosphere can address the longer-term accumulation of carbon dioxide.

Carbon Removal Portfolio Tops 1.3 Million Tonnes

In 2025, the company signed 16 carbon removal agreements worth more than $100 million. Those contracts covered around 600,000 tonnes of CO₂ removal.

  • Combined with earlier commitments, Google’s contracted carbon removal portfolio exceeded 1.3 million tonnes of CO₂ by the end of 2025.
  • And its carbon reduction initiatives avoided over 58 million tCO2e in 2025.

The portfolio spans different approaches, including long-duration carbon removal and nature-based solutions. As explained before, targeting methane and other superpollutants is also a significant part of Google’s net zero plan.

google emissions carbon removal
Source: Google

This creates a broader climate strategy built around different timescales. Methane reductions can help limit near-term warming, while durable carbon removal aims to keep CO₂ out of the atmosphere for much longer periods.

Agriculture Could Become a Larger Climate Solution

The Google-Mitti Labs agreement also highlights agriculture’s growing role in carbon markets.

Rice farmers do not need to completely change how they grow the crop. Instead, AWD modifies how they manage water during cultivation.

It could make the approach easier to scale, particularly in regions where farmers already face water shortages and rising climate risks.

For carbon markets, however, scale will need to be matched with strong measurement. Projects involving thousands of smallholder farms must demonstrate that emission reductions are real, measurable, and sustained.

Mitti Labs is betting that satellite monitoring and field-level data can help solve that challenge.

If the program reaches its target of more than 100,000 hectares, it could become a major example of how digital technology can connect smallholder agriculture with climate finance.

For Google, the agreement adds another piece to a carbon strategy that is moving beyond traditional CO₂ removal. And for the carbon market, it shows how methane reduction, water conservation, and agricultural finance can increasingly overlap in a single project.

The post Google Targets Rice Methane Emissions in India with 1 Million Carbon Credits appeared first on Carbon Credits.
Pentagon Backs Nevada’s Springer Project to Boost US Tungsten Supply

The U.S. is backing an effort to rebuild its tungsten supply chain as China maintains a dominant position in the global market.

The U.S. Department of War, aka the Pentagon, has committed up to $450 million to The Elmet Group (NASDAQ: ELMT), a U.S.-owned tungsten and advanced materials company. About $150 million of that government-backed investment has been designated for a transaction involving Blue Moon Metals’ (TSXV: MOON; NASDAQ: BMM) Springer Tungsten Complex in Nevada.

Blue Moon, Elmet, and Australia-listed EQ Resources (ASX: EQR) have agreed to a US$150 million investment in the Springer project, with another US$25 million set aside by Elmet and EQ Resources for additional requirements, if needed, to restart the project’s ammonium paratungstate (APT) plant.

The deal comes as Washington tries to reduce exposure to China-dominated critical-mineral supply chains. Tungsten is particularly important because the U.S. has not mined the metal commercially since 2015, while domestic consumption remains heavily dependent on imports.

Department of War Backs Domestic Tungsten Capacity

Pentagon announced the $450 million investment in Elmet on September 14. The funding will take the form of redeemable preferred equity and is being provided through the department’s Industrial Base Analysis and Sustainment program.

The government says the investment will expand domestic tungsten capacity and strengthen the industrial base supporting U.S. defense programs. Elmet currently supplies materials and components for more than 100 Department of War programs, including the F-35, Patriot PAC-3, Trident D5, Next Generation Interceptor, PrSM and Virginia- and Columbia-class submarines.

A Bigger Role for Elmet

The government also says the investment will help establish North America’s only independent APT facility, addressing a major processing gap in the U.S. tungsten supply chain. China currently accounts for an estimated 85% of global tungsten supply, according to the Department of War.

Separately, Elmet said one of its subsidiaries secured a contract worth about $2 billion from the Defense Logistics Agency to help rebuild the National Defense Stockpile. The agreement includes a guaranteed funded commitment of $150 million and covers tungsten ores, concentrates and sodium tungstate.

The two announcements give Elmet a central role in Washington’s effort to rebuild domestic tungsten capacity, from raw material supply to processing and manufacturing.

U.S. Still Depends on Tungsten Imports

The supply-chain challenge is significant.

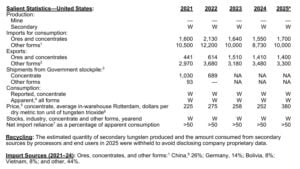
The latest U.S. Geological Survey data show that the U.S. has had no commercial tungsten mine production since 2015. Estimated 2025 imports reached:

  • 1,700 tonnes of tungsten contained in ores and concentrates
  • 10,000 tonnes in other tungsten forms
  • More than 50% net import reliance for apparent consumption
US Tungsten
Source: USGS

USGS also estimates that China represented 26% of U.S. tungsten import sources between 2021 and 2024, followed by Germany at 14%, Bolivia at 8% and Vietnam at 8%.

TUNGSTEN
Source: USGS

The figures show why Washington is focusing on more than simply reopening a mine. The U.S. needs additional capacity across mining, processing and manufacturing if it wants to reduce exposure to overseas supply disruptions.

The supply risk has become more urgent since China introduced export controls on selected tungsten products in February 2025. USGS reported that prices climbed sharply during 2025. The average Rotterdam price for 65% tungsten concentrate increased from $252 per metric ton in 2024 to an estimated $380 in 2025.

USGS also ranks tungsten among the minerals with a high potential economic impact from supply disruption. Its 2025 assessment estimated a probability-weighted reduction of about $544 million in U.S. GDP under the modeled disruption scenario.

Springer Could Restart U.S. Tungsten Mining

Against that backdrop, the Springer project offers a potential domestic source.

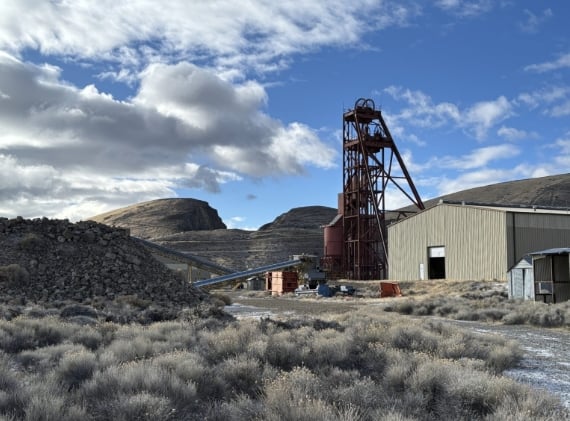
                                                The Springer Mine

springer
Source: Blue Moon

Located near Imlay, Nevada, Springer historically ranked among the largest tungsten mines in the United States. The project includes open-pit and underground mining operations, a 1,200-ton-per-day mill and an APT plant designed for potential production of up to 4,000 tonnes per year.

  • Blue Moon expects the Springer mine and mill to return to production in the fourth quarter of 2027. The APT plant is expected to restart in the second half of 2028.

The project already has access to water, electricity, natural gas, and tailings capacity. It is also located a few miles from Interstate 80 and the Union Pacific rail line. Blue Moon acquired additional water rights and land in September to provide access to the rail line, with the potential for a future loading facility.

Resource Estimate Needs Further Verification

Blue Moon reports a historical mineral resource of 10.7 million tonnes grading 0.45% WO₃. However, the company clearly states that this is a historical estimate from prior operators and has not been verified as a current NI 43-101 resource. Further drilling is planned to update the estimate.

That distinction is important for investors because the historical resource should not be treated as a current compliant resource.

Elmet Will Control the APT Plant

The transaction is designed to connect Springer mining with downstream tungsten processing.

Elmet will provide about $150 million across the Springer-related transactions. This includes a $50 million tungsten prepayment facility for Blue Moon and a $75 million capital contribution to the joint venture that will own and operate the APT plant. Elmet will also subscribe for $25 million of new Blue Moon equity.

The APT joint venture is expected to have the following ownership:

  • Elmet: 70%
  • Blue Moon: 20%
  • EQ Resources: 10%

Phase-one APT capacity is targeted at 4,000 tonnes per year, with infrastructure planned to support blue tungsten oxide capacity and an additional leaching line. Elmet will operate the facility.

The structure gives Springer a pathway from mined tungsten concentrate to a processed product that can feed downstream U.S. manufacturing.

EQ Resources Adds Australian and Spanish Supply

EQ Resources brings an allied supply component to the project.

The Australian company operates the Mt Carbine tungsten project in Queensland and Barruecopardo in Spain. Under the agreement, EQ will take a 10% interest in the APT joint venture and enter into an offtake agreement covering 4,000 tonnes of tungsten trioxide contained in its concentrate over eight years after the APT plant begins operating.

During the first five years, EQ could use up to 25% of the APT plant’s input capacity, capped at 1,000 tonnes of production capacity per year. Springer would receive up to 75% of the input volume during that period, with additional material potentially sourced through other agreements supported by Elmet and the Department of War.

EQ is also testing its ore-sorting technology at the Springer mill. Initial results were positive, although additional testing is still required before installation is confirmed.

Building a U.S.-Aligned Tungsten Chain

The Springer deal represents one part of a broader effort to rebuild U.S. tungsten supply.

The Department of War’s $450 million commitment to Elmet, the separate potential $2 billion DLA stockpile contract, and the Springer investment all address different parts of the same vulnerability: the U.S. has significant tungsten demand but no active commercial tungsten mine.

For Blue Moon, the transaction provides funding and strategic partners to advance Springer. For Elmet, it expands control over tungsten processing and downstream manufacturing. For EQ Resources, it creates another route into the U.S. market for tungsten from allied jurisdictions.

The broader market backdrop is also becoming more supportive for new Western supply. Global tungsten mine production reached an estimated 85,000 tonnes in 2025, according to USGS, while China remained the world’s leading producer, importer and consumer of tungsten concentrates.

Springer will not eliminate U.S. import dependence on its own. But if Blue Moon meets its development targets, the project could become an important domestic source of tungsten concentrate and APT.

The bigger investment story is the attempt to rebuild the entire supply chain, from Nevada mining to North American processing and U.S. defense manufacturing, at a time when China continues to dominate the global tungsten market.

The post Pentagon Backs Nevada’s Springer Project to Boost US Tungsten Supply appeared first on Carbon Credits.
EPA Rolls Back Carbon Rules for Coal and Gas Plants in Major U.S. Climate Shift

EPA Rolls Back Carbon Rules for Coal and Gas Plants in Major U.S. Climate Shift

The U.S. Environmental Protection Agency (EPA) has moved to dismantle federal limits on carbon emissions from coal- and natural gas-fired power plants, marking a major shift in U.S. climate policy.

On September 14, 2026, the EPA finalized a repeal of most of the greenhouse gas requirements in the Biden administration’s 2024 power plant rule. At the same time, it proposed removing the remaining federal greenhouse gas standards for fossil-fuel power plants.

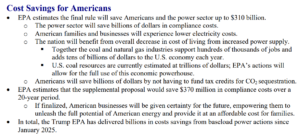
EPA Administrator Lee Zeldin said the changes will reduce costs and make it easier to expand U.S. power generation. The agency estimates that the finalized repeal could save the power sector and consumers up to $310 billion. Additionally, the proposed repeal might save another $370 million in compliance costs over 20 years.

The move comes as the U.S. faces rising electricity demand from data centers, manufacturing, and other industries. But it also removes a major federal tool for cutting power-sector emissions.

What the EPA Is Repealing

The Biden EPA finalized its Carbon Pollution Standards in April 2024. The rules covered existing coal-fired plants and new natural gas-fired power plants. The agency wrote:

“U.S. EPA is repealing the most burdensome greenhouse gas emissions standards from the EPA’s 2024 Carbon Pollution Standards (CPS), while simultaneously working to cement long-term energy prosperity by proposing to repeal the remaining Obama-Biden Greenhouse Gas (GHG) emission standards for the power sector.”

For existing coal plants, the rules relied heavily on carbon capture and storage (CCS) for units planning to operate for longer periods. New long-term natural gas plants also faced emissions limits based on technologies including CCS and lower-carbon fuels.

The Trump EPA now says those requirements were too costly and depended on technologies that are not available at the required scale. The agency specifically determined that 90% carbon capture was not adequately demonstrated or cost-effective for coal plants.

It also rejected natural gas co-firing as an appropriate emissions-control approach for existing coal units. Most of these requirements have now been removed.

The EPA is asking for public feedback on a plan to remove all remaining greenhouse gas standards for fossil-fuel power plants. This is under Section 111 of the Clean Air Act. That part is still a proposal, rather than a final repeal.

EPA Says Repeal Will Lower Energy Costs

The Trump administration argues that the rules could have forced utilities to spend heavily on emissions controls or retire plants earlier than planned. The EPA says repealing them will reduce compliance costs and make it easier to build and operate coal and natural gas generation.

Its September 2026 fact sheet estimates up to $310 billion in savings from the finalized repeal. It says the changes will also reduce barriers to new power projects and support greater use of domestic coal and natural gas. This argument comes as electricity demand is rising.

EPA Says Repeal Will Lower Energy Costs
Source: EPA

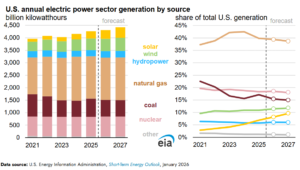
The U.S. Energy Information Administration expects electricity generation to reach new records in 2026 and 2027. It forecasts natural gas to provide about 40% of U.S. electricity generation in 2026, while coal’s share falls to about 16%.

Data centers are one source of the increase. Manufacturing growth and higher cooling demand are also adding pressure to the grid.

US annual electricity generation by source EIA
Source: EIA

U.S. Power Emissions Jump as Electricity Demand Grows

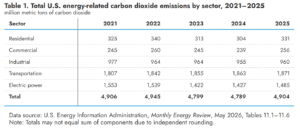
The timing of the repeal is important because U.S. power sector emissions increased in 2025. EIA estimates that carbon dioxide emissions from the electric power sector rose 4%, or 58 million metric tons, in 2025.

  • Electricity generation increased by 3%, while coal-fired generation jumped 13%.
Total U.S. energy-related carbon dioxide emissions by sector
Source: U.S. Energy Information Administration

Coal-related power emissions rose by 78 million metric tons during the year. That increase reversed part of the longer decline in U.S. power-sector emissions.

Natural gas remains the largest source of U.S. electricity generation, but coal still produces much more CO2 per unit of electricity. EIA expects coal’s share of generation to decline over the next two years as scheduled retirements continue, even as overall power demand grows.

This means the EPA rollback does not guarantee a major increase in coal generation. Market forces, plant economics and the growth of lower-cost renewable power will continue to influence the generation mix.

Biden EPA Projected Large Emissions Cuts

The disagreement over the rules is partly about their expected climate benefits.

The 2024 EPA analysis projected that the standards would reduce power sector carbon pollution by 1.38 billion metric tons between 2028 and 2047. It also estimated up to $370 billion in climate and public health net benefits over two decades.

The agency’s analysis predicts that by 2035, the rules could reduce annual power sector CO2 emissions by 123 million metric tons. This is compared to a scenario without the standards. Those projected benefits will now largely disappear if the federal standards are fully removed.

The Trump EPA disputes the earlier estimates and argues that the rules relied on unrealistic technology assumptions and would have imposed unnecessary costs. The difference reflects two very different views of how the U.S. should decarbonize its electricity system.

CCS Loses a Major Policy Driver

The repeal also has implications for the U.S. carbon capture market. The 2024 rules helped create a potential market for CCS at coal and gas plants because some facilities would have needed major emissions reductions to comply.

Removing those requirements weakens one of the strongest federal policy drivers for power sector CCS. Yet, that does not mean CCS development will stop.

Federal tax incentives for carbon capture remain available, and companies in sectors such as cement, steel, chemicals and natural gas processing continue to explore the technology. However, power plants now have less regulatory pressure to install expensive capture systems.

For the carbon market, this is an important distinction. Capturing and permanently storing CO2 from a fossil fuel power plant is not automatically the same as generating a tradable voluntary carbon credit. Its value may instead come through regulatory compliance, tax incentives or corporate climate claims, depending on the project.

States and Corporate Buyers Can Still Push Cleaner Power

The federal rollback does not end climate regulation across the United States. States can maintain their own emissions rules, renewable energy standards and climate policies.

California and other states already have systems that require significant reductions in power-sector emissions. Utilities also face pressure from investors, customers and large electricity buyers.

Technology companies building data centers are increasingly looking for cleaner electricity to meet their own emissions targets. That creates another market force supporting renewable energy, storage and low-carbon generation even as federal climate rules are weakened.

The U.S. power market will likely stay split. Some states and companies are pushing for lower-carbon electricity. Meanwhile, federal policy supports more fossil fuel development.

What the EPA Rollback Means for Carbon Markets

The EPA’s decision could have effects well beyond power plants. The U.S. electric power sector produced about 1.485 billion metric tons of energy-related CO2 in 2025, making it a major source of emissions.

Removing federal carbon limits could make deeper emissions cuts harder and change investment decisions across coal, gas, renewables, storage and carbon capture. It also highlights the importance of policy risk for carbon markets, where project economics can depend on regulations, tax credits and carbon prices.

The move marks a major shift from the Biden administration’s approach, which used emissions standards to push utilities toward cleaner technologies. The Trump administration argues those rules would raise costs and threaten power reliability.

Meanwhile, electricity demand is rising due to data centers, manufacturing and electrification. Solar, wind, storage and natural gas will compete to meet that growth, while EIA still expects coal’s share of U.S. generation to decline.

The key question is whether market forces, state policies and corporate clean energy demand will continue to reduce emissions—or whether the federal rollback will slow that progress.

The post EPA Rolls Back Carbon Rules for Coal and Gas Plants in Major U.S. Climate Shift appeared first on Carbon Credits.
Philippines Builds Forest Carbon Roadmap as New Climate Target Raises Demand for Finance

Philippines Builds Forest Carbon Roadmap as New Climate Target Raises Demand for Finance

The Philippines is moving to turn its forests into a larger source of climate finance as it takes on a tougher emissions target. The country has a 2026–2030 roadmap for the voluntary forest carbon market. It is creating the registry, monitoring systems, and policies to draw in private investment for forests.

The move comes just days after the Philippines submitted its updated 2026 Nationally Determined Contribution (NDC) to the UN climate process.

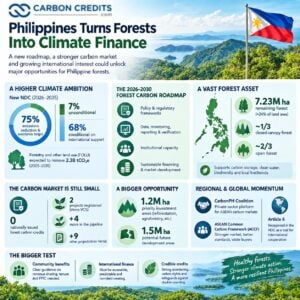
The new NDC keeps the country’s 75% emissions reduction and avoidance target, but changes the structure. The target now covers 2025–2035 and includes forestry and other land use (FOLU).

Of the 75% target, 7% is unconditional, while 68% depends on international support. That makes forest carbon more than a conservation opportunity. It could become one tool for helping the Philippines secure investment needed to deliver its broader climate targets.

Philippines Puts Forests at the Center of Its Climate Strategy

The Philippines’ new NDC gives forests a much larger role in its emissions pathway. The 2026 NDC covers energy, transport, industrial processes, agriculture, waste, and forestry and other land use.

Updated government modelling shows the FOLU sector has been a net carbon sink since 2020. The NDC estimates that FOLU policies could reduce cumulative emissions by about 2.3 billion tonnes of CO₂e between 2025 and 2035 compared with the business-as-usual pathway.

With all identified policies and measures, the country is projected to become a net sink over the 2025–2035 period. That makes protecting and expanding the forest carbon sink important to the country’s overall climate strategy.

The NDC commits the Philippines to fully use this sink. This will happen through forest protection, reforestation, and sustainable land management.

DENR Forest Management Bureau Assistant Director Ray Thomas Kabigting remarked:

“FMB is ready to converse with the business sector in a more scaled-up way wherein we’re talking about financing, we can already understand balance sheets, and we can produce policies that are actually aligned with business concepts and business science rather than just pure forestry science.”

A Five-Year Roadmap for Forest Carbon

The Department of Environment and Natural Resources (DENR) formally adopted its Roadmap to Readiness in the Voluntary Forest Carbon Market 2026–2030 through Administrative Order No. 2026-02.

The roadmap identifies four priorities:

  1. Policy and regulatory frameworks,
  2. Data, monitoring, reporting, and verification,
  3. Institutional capacity, and
  4. Sustainable financing and market development.

The goal is to make the Philippines more attractive for high-quality forest carbon projects while creating safeguards around carbon ownership, benefit sharing, and environmental integrity.

The roadmap also calls for a DENR Forest Carbon Credit Database that will track forest carbon projects and credits. It is designed to connect with a broader national carbon registry being developed under the country’s Article 6 framework. This infrastructure matters because buyers increasingly want evidence that credits are real, additional, and not counted twice.

7.23 Million Hectares Give the Philippines a Major Carbon Asset

The economic opportunity is significant. The DENR roadmap estimates that the Philippines has about 7.23 million hectares of remaining forest, equal to roughly 24% of the country’s land area.

The document estimates that around one-third is closed-canopy forest and two-thirds is open forest. These forests provide more than carbon storage. They also protect watersheds, reduce soil erosion, support biodiversity, and provide livelihoods for local communities.

However, forest finance remains a major challenge. The roadmap says global investment in forests is about $2.2 billion per year. Still, the world needs over $450 billion annually to reach forest and climate goals.

Carbon finance can help bridge that gap. It creates revenue linked to clear forest protection and restoration efforts. The Philippines is thus trying to move from short-term conservation funding toward longer-term investment models.

The Forest Carbon Market Is Still Small, but the Pipeline Is Growing

Despite the potential, the Philippine forest carbon market remains small. The DENR roadmap says there were no nationally issued carbon credits at the time of its stocktake. Existing credits had been issued through international standards.

The government identified two projects registered under Verra’s Verified Carbon Standard, with four additional projects in the pipeline. At least nine other forest carbon projects were also identified outside the Verra system.

Some projects are in Mindanao. Other opportunities are being looked into in areas with community forest agreements, ancestral domains, and other forest tenure arrangements.

The roadmap highlights 1.2 million hectares of classified forest land as key investment areas. These areas are prioritized for reforestation, agroforestry, and other forest-based development.

Another 1.5 million hectares are being assessed for possible release for future development. That could significantly expand the potential project pipeline. But land tenure, carbon rights, and benefit sharing remain important hurdles.

Philippines Builds Forest Carbon Roadmap

CarbonPH Pushes the ASEAN Opportunity

This is where the recent CarbonPH Coalition initiative becomes important. At a CarbonPH Coalition Education Series session, DENR officials shared their plans. They aim to strengthen forest carbon project registration. They will also establish carbon baselines and expand monitoring.

The DENR Forest Management Bureau is creating a registry to track projects and credits. They are also using satellite monitoring to enhance verification.

The Philippines is also seeking a stronger position in the ASEAN Common Carbon Framework (ACCF). The country is an observer right now, while the regional initiative is focused on building a stronger carbon market. It aims to improve supply integrity, boost demand, and ensure interoperability.

The United Nations Environment Programme (UNEP) says annual investment in nature-based solutions must nearly triple by 2030, reaching more than $542 billion a year. This funding will be critical to meet global climate, biodiversity, and land restoration goals.

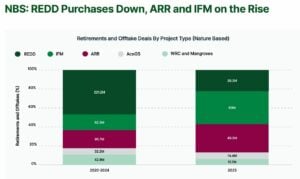
At the same time, demand for high-quality nature-based carbon projects is growing. Forest protection (REDD), reforestation (ARR), and mangrove restoration remain major sources of nature-based carbon credits. Buyers are increasingly looking for projects backed by strong science, reliable monitoring, and clear benefits for local communities.

nature based credits Allied Offsets
Source: Allied Offsets

That could give Philippine forest projects access to a wider pool of regional buyers if standards and systems become more connected.

Regional competition is already growing. Malaysia has a government-supported carbon exchange. Indonesia and Thailand are also building their carbon market systems. For the Philippines, credible forest projects could become a way to compete on quality rather than simply price.

Carbon Finance Must Also Deliver for Communities

Scaling forest carbon will require more than satellites and registries. The DENR roadmap identifies benefit sharing as a major gap.

Developers must submit benefit-sharing plans. However, the roadmap notes that more guidance is needed on revenue distribution. That issue matters a lot. Many potential projects affect communities, forest tenure holders, and Indigenous Peoples.

The roadmap calls for stronger safeguards and recognition of Free, Prior and Informed Consent (FPIC) where projects affect ancestral lands and domains. The credibility of Philippine forest credits depends on two things:

  • How much carbon they remove or avoid, and if local communities gain real benefits.  

The forest carbon roadmap fits directly into the Philippines’ broader climate finance challenge. The new NDC says implementation depends on access to accessible, predictable, and adequate international support. 

That means finance, technology, and capacity building are not secondary issues. They are central to delivering the country’s climate commitment. Carbon markets could become one part of that financing mix.

The new NDC also recognizes Article 6 mechanisms as tools for international cooperation and resource mobilization. Any international transfers, however, will require strong governance, monitoring, and safeguards against double counting.

Forest Carbon Could Link Climate Goals and Investment

The Philippines now has two pieces of a potentially important climate finance strategy. The 2026 NDC places the country’s forest sink directly inside its emissions pathway.

The CarbonPH Coalition is adding a private-sector platform to connect those developments with emerging ASEAN carbon markets. But the opportunity is still at an early stage.

The country needs clearer carbon rights, reliable monitoring, workable tenure rules and transparent benefit sharing before forest carbon can scale. It also needs international finance to help develop projects that may not be commercially viable on carbon revenue alone.

If those pieces come together, Philippine forests could play a larger role in both emissions reduction and climate finance.

The bigger test is whether the country can turn its millions of hectares of remaining forest and its expanding carbon market infrastructure into credible, investable climate assets while ensuring that communities and ecosystems share in the value.

The post Philippines Builds Forest Carbon Roadmap as New Climate Target Raises Demand for Finance appeared first on Carbon Credits.
Canada Investment Summit 2026: Can $1 Trillion Drive a Critical Minerals Mining Boom?

Canada is putting mining and critical minerals at the centre of a new push to attract global investment. Prime Minister Mark Carney hosted Canada’s first Investment Summit in Toronto on September 14–15, bringing together global investors and Canadian companies as Ottawa seeks to catalyze C$1 trillion in investment over the next five years.

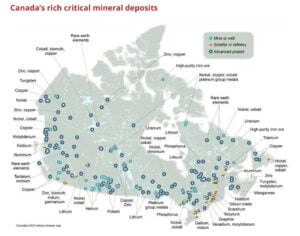
The government’s investment prospectus features 167 projects across eight sectors, with mining and metals accounting for 63 projects, the largest category in the portfolio. The projects span commodities including copper, lithium, graphite, gold and other minerals considered important to energy, technology and national security supply chains.

The focus on mining comes as governments and manufacturers look to diversify critical-mineral supply chains away from concentrated sources of production and processing.

For Canada, the opportunity is not simply to increase mine output. It is to attract the capital needed to build mines, processing facilities and infrastructure while keeping the environmental footprint of new production under control.

Mining Leads Canada’s Investment Pitch

The scale of the mining presence at the summit is significant.

As said before, of the 167 projects in the federal prospectus, 63 are in mining and metals. That makes the sector the largest component of Canada’s investment pitch to global institutional investors.

Canada already has a large and established mining economy.

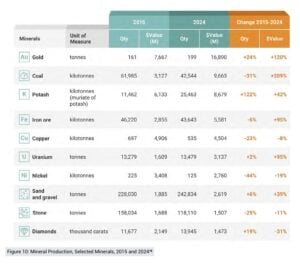
Natural Resources Canada says the country produced more than 60 minerals and metals worth C$64.3 billion in 2024. Metals accounted for more than half of that value, with gold alone contributing about 26%.

Canada is also a leading global producer of several critical minerals and ranked among the world’s major producers of uranium and palladium. The broader minerals sector directly employed approximately 438,000 people in 2024.

However, developing new deposits requires substantial upfront capital. Long permitting timelines, infrastructure requirements and the need for processing capacity can also make projects difficult to finance.

Ottawa is increasingly using government-backed capital to help bridge that gap.

Canada Mining
Source: Canada Govt

C$140 Million backs Ontario’s Generation Mining Marathon Project

Canada Growth Fund announced a commitment of approximately C$140 million to Generation Mining (TSXV: GENM) to support the development of the Marathon Project in northwestern Ontario. The investment is intended to help advance the project toward construction and mobilize additional private capital.

The Marathon Project is a large copper-palladium development that also contains platinum, gold and silver.

Generation Mining announced separately that it has now assembled approximately US$1.3 billion in project financing for construction. The package includes the Canada Growth Fund investment, approximately US$50 million from the Canada Infrastructure Bank, senior and subordinated debt and metal-streaming arrangements.
The project is expected to enter early construction work in the fourth quarter of 2026, subject to the company’s financing arrangements and construction conditions.
Marathon is important beyond its individual production potential because it could strengthen Canada’s domestic critical-minerals chain.
The company has an agreement with Glencore to purchase the project’s polymetallic concentrate, providing a potential route into existing Canadian processing infrastructure.

Frontier Lithium’s PAK Lithium Project Adds Another Layer

Lithium is another major theme in Canada’s investment push. Frontier Lithium’s PAK Lithium Project in northwestern Ontario has been included in the Canada Investment Summit prospectus and Ontario’s Deal Book. The company described PAK as the only lithium project included in Ontario’s investment portfolio.

Other projects are also seeking to connect Canadian mineral resources with international battery supply chains.

  • E3 Lithium, for example, recently signed a non-binding memorandum of understanding with India’s Epsilon Advanced Materials to potentially supply up to 5,000 tonnes of lithium carbonate per year from its Clearwater project in Alberta over five years.

The agreement highlights another part of Canada’s strategy: using its mineral resources to build relationships with buyers outside the U.S.

Canada’s Mining Output is Already Substantial

Canada’s critical-minerals investment strategy is being built on an existing mining base.

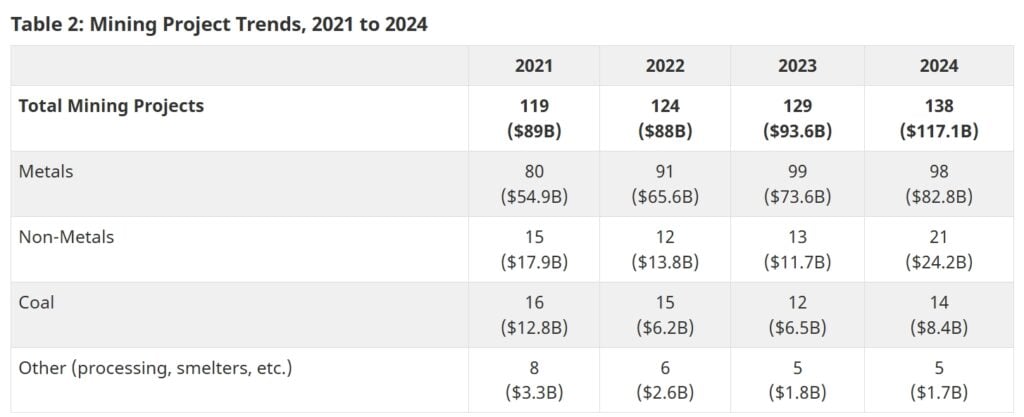
The value of Canadian mineral production reached C$64.3 billion in 2024, although that was down from C$70.4 billion in 2023. Natural Resources Canada says metals production increased by 1%, while non-metals and coal declined, largely because of lower coal and potash prices.

canada mining critical mineral
Source: The Mining Association of Canada | The Mining Story 2026

The country therefore has an established workforce, mining expertise, capital markets and infrastructure that can support a new generation of projects.

The challenge is scaling that system quickly enough.

CANADA mining critical minerals

The Emissions Challenge is Harder to Ignore

Canada’s mining expansion also comes with a climate challenge.

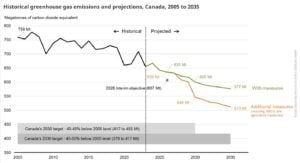
The country’s latest National Inventory Report, released in 2026 and covering emissions through 2024, puts Canada’s total greenhouse gas emissions at approximately 685 million tonnes of CO2e in 2024. It was about 10% below the 2005 level of 763 Mt CO2e.

Mining’s emissions require more careful interpretation.

Its stationary combustion emissions were about 5.5 Mt CO2e in 2024. This figure covers emissions from stationary fuel combustion and should not be treated as the industry’s entire carbon footprint.

Mining and quarrying also appear within broader energy-sector categories that include other activities.

For example, Canada’s facility-level reporting system groups mining, quarrying, and oil and gas extraction together. Those facilities reported approximately 126 Mt CO2e in 2024. However, that number should not be described as mining’s standalone emissions because the category includes the much larger oil and gas industry.

This distinction matters as Canada promotes new mining investment.

CANADA EMISSION
Source: Govt of Canada

The country wants to increase production of the minerals needed for electrification and energy technologies while also reducing the emissions intensity of the economy.

Low-carbon power could become a mining advantage

Canada has one potential advantage in that race: electricity.

Several major mining provinces have access to large amounts of hydroelectric or nuclear power. That could help mines reduce their reliance on fossil fuels, particularly for electricity-intensive processing.

For investors and industrial buyers, the carbon footprint of mineral production could become increasingly important. Copper, lithium, nickel, graphite and other minerals may be essential to the energy transition, but producing them still requires energy, transportation and processing.

This creates an opportunity for Canada to compete not only on resource availability but also on the potential carbon intensity of supply.

A Race for Capital, Not Just Minerals

Overall, the Canada Investment Summit highlights a clear opportunity for the country’s critical-minerals sector. Canada has the resources and mining expertise. Now, it needs capital, infrastructure, and faster project development.

With 63 mining and metals projects in the summit prospectus, Ottawa is betting that its C$1 trillion investment ambition can turn mineral wealth into new domestic supply chains and lower-carbon growth.

The question now is whether Canada can bring these projects into production fast enough, while keeping their environmental footprint competitive.

The post Canada Investment Summit 2026: Can $1 Trillion Drive a Critical Minerals Mining Boom? appeared first on Carbon Credits.