Google’s Big Energy Bet on Finland: 22-Year Fortum Deal Brings Nuclear, Renewables and Storage Together
Google is taking a long-term stake in Finland’s low-carbon energy future. The technology giant has signed a 22-year power purchase agreement (PPA) with Finnish utility Fortum covering up to 50% of the generation capacity of the Loviisa nuclear power plant.

The press release says that the agreement will help Fortum finance investments needed to extend Loviisa’s operating life through 2050. It will also support a planned power upgrade at the plant.
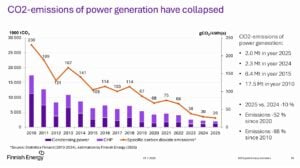
Finland’s Electricity Demand is Rising, But Emissions are Falling

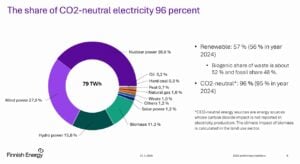
Finland consumed 85 TWh of electricity in 2025, up 2% from 2024. Industry accounted for 42% of demand, while households, services, buildings and agriculture made up most of the rest. Industrial electricity use rose 2.6% during the year.

At the same time, 96% of Finland’s electricity came from CO₂-neutral sources in 2025, up from 95% in 2024. Here’s the chart showing the share:

low carbon electricity

  • This cleaner power mix has helped cut emissions sharply. CO₂ emissions from electricity generation fell to 2 million tonnes in 2025, down 10% from 2024 and 88% from 2010.
  • Emissions from electricity and district heating also fell to 3.9 million tonnes in 2025, down 31% from the previous year and 88% from the 2003 peak.

carbon emission

The Loviisa Deal Puts Nuclear at the Center

The most important part of the partnership is the long-term PPA.

  • The agreement starts in 2028 with a smaller contracted capacity. From 2030 through 2049, Google will contract up to 50% of Loviisa’s generation capacity.

It gives Fortum something particularly valuable for a large nuclear investment: long-term revenue visibility.

Fortum is already pursuing an approximately €1 billion investment program to extend Loviisa’s operating life to 2050. About €700 million of the required capital expenditure is still pending investment decisions.

The Google agreement provides additional certainty to move ahead with those investments. This matters significantly because Loviisa is not a marginal asset for Finland.

                                        Loviisa nuclear plant
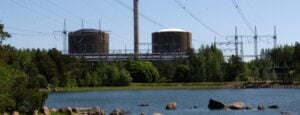
Loviisa nuclear plant
Source: Fortum

Keeping 10% of Finland’s power online

The plant currently provides about 10% of Finland’s electricity and employs approximately 580 people. Without the lifetime extension investment program, Loviisa would not be able to continue operating beyond 2030.

Extending the plant to 2050 therefore allows Finland to retain a large source of reliable, fossil-free electricity instead of losing that capacity at the end of the current operating period.

Additionally, the agreement could also increase the plant’s output. Fortum already has plans for a 38-megawatt capacity increase, expected to be operational in 2028. The new partnership with Google could support an additional 10 MW increase.

For Finland’s electricity system, keeping existing nuclear generation online while adding capacity can help strengthen supply without waiting years for entirely new large-scale generation projects.

Google’s Finland Bet Goes Beyond Nuclear Power

But the partnership goes beyond nuclear power.

The companies have also agreed to explore new nuclear generation, renewable energy and flexibility solutions. The companies are effectively building a broader framework for expanding reliable, low-carbon electricity across Finland.

  • Google plans to invest €13 billion in Finland during 2027 and 2028. The investment will include data centers, supporting infrastructure and partnerships in Hamina, Muhos, Vaala and Kajaani.

Fortum has an 8 GW renewable pipeline in the Nordic countries currently in the permitting phase. The company aims to have 1.2 GW of ready-to-build renewable projects and 2.5 GW of new flexibility services and generation assets ready to deploy by the end of 2028.

Google’s partnership could help create demand for some of that future capacity and create a much broader clean-energy strategy.

The companies also want to explore how nuclear, renewable energy and flexibility technologies can work together as electricity demand changes. However, for Fortum, the immediate focus is clear: keep a major source of Finland’s fossil-free electricity online for another two decades.

Batteries join the equation

The first example is already taking shape in Kajaani. The deal will help optimize a new 94 MW battery storage system that Google has contracted for near its new data center.

Battery storage can help balance variable renewable generation and provide additional flexibility to the electricity system. It makes the partnership broader than a traditional nuclear PPA.

Google’s Clean-Energy Portfolio is Expanding

The Fortum agreement also fits into Google’s rapidly expanding clean-energy portfolio.

  • In 2025, Google struck more than 12 GW of net-new clean energy deals. It was the company’s largest annual clean-energy procurement and exceeded the combined amount it contracted during the previous two years.

Since 2010, it has signed more than 240 clean-energy agreements representing nearly 35 GW of capacity. It also reported a 37% increase in electricity demand in 2025.

  • Despite that increase, Google said it reduced operational emissions by 2% and matched 100% of its electricity consumption with renewable energy purchases for the ninth consecutive year.
  • Its energy, hardware and computing-efficiency initiatives also avoided more than 58 million metric tons of CO2 equivalent in 2025.
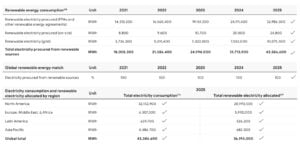
clean energy google
Source: Google

The Nuclear Strategy Extends Beyond Finland

The Loviisa agreement is not Google’s only nuclear commitment. The company has signed landmark nuclear agreements earlier, and they are:

  • Kairos Power: Google’s 2024 agreement supports up to 500 MW of advanced nuclear capacity by 2035. Its Hermes 2 project in Tennessee is expected to supply up to 50 MW to the TVA grid from 2030.
  • Elementl Power: In 2025, Google agreed to provide early-stage funding for three potential U.S. nuclear sites, each targeting at least 600 MW, with an option to purchase future power.
  • Commonwealth Fusion Systems: Google has invested in the fusion company as part of its strategy to support next-generation clean energy. The partnership aims to advance fusion power toward commercial deployment.
  • TAE Technologies: Google has also invested in TAE Technologies, supporting its efforts to develop fusion energy. TAE is pursuing a compact fusion approach designed to produce reliable, carbon-free power.

Geothermal, storage and fusion broaden the bet

In Taiwan, Google signed geothermal agreements expected to add 10 MW of always-on geothermal power to the grid and made an equity investment in Baseload Capital.

Google is also supporting long-duration energy storage through its partnership with Energy Dome. Its CO2 Battery technology is designed to store renewable electricity and discharge it over eight to 24 hours.

Together, however, they show Google’s willingness to support a wide range of technologies that could contribute to a more resilient low-carbon electricity system.
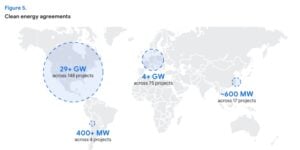
google clean energy
Source: Google

A Nordic Model for Clean Energy

The Loviisa deal shows how big companies can support the wider energy transition, not just buy clean electricity. Google’s long-term demand gives Fortum greater certainty to keep Loviisa running through 2050 and develop new renewable, storage and nuclear capacity.

Google’s €13 billion investment in Finland adds to this strategy by expanding its footprint and supporting the country’s low-carbon energy system. The partnership could become a model for using corporate demand and investment to strengthen clean energy infrastructure across Finland and the Nordic region.

The post Google’s Big Energy Bet on Finland: 22-Year Fortum Deal Brings Nuclear, Renewables and Storage Together appeared first on Carbon Credits.
Biochar Demand Hits 2.99 Million Tonnes: Can Corporate Buyers Trigger a Supply Crunch?

Biochar is quickly becoming one of the most important technologies in the carbon removal market. But as corporate demand grows, buyers are running into a new problem: there may not be enough high-quality biochar to go around.

A new report from carbon removal marketplace Supercritical shows that 81% of high-quality biochar supply for 2026 had already been committed by July. In 2025, the same threshold was not reached until October.

The shift highlights how quickly the biochar market is moving from an emerging carbon removal technology toward a more established market where buyers are competing for proven supply.

At the same time, the market is becoming more selective. Hundreds of projects are developing biochar capacity, but Supercritical found that only a small share meets its quality standards.

Biochar Demand Is Growing Rapidly

The numbers show just how quickly demand is changing.

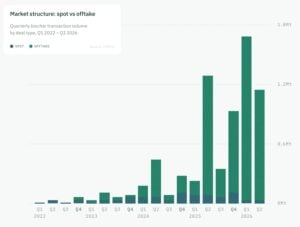
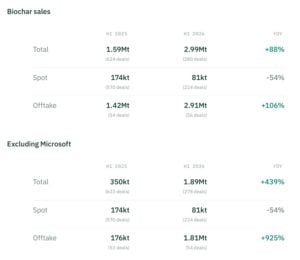
  • Biochar sales nearly doubled in the first half of 2026, rising from 1.59 million tonnes in H1 2025 to 2.99 million tonnes across 280 deals. However, the headline growth hides an important shift in how buyers are purchasing credits.
  • Spot-market sales actually fell 54%, from 174,000 tonnes to 81,000 tonnes.
biochar demand
Source: Supercritical

Instead, corporate buyers are increasingly signing longer-term offtake agreements. Offtake volumes jumped from 1.42 million tonnes in H1 2025 to 2.91 million tonnes in H1 2026.

  • Notably, excluding Microsoft, offtake purchases increased more than tenfold, from 176,000 tonnes to 1.81 million tonnes.

In other words, buyers are not simply buying more biochar. They are locking it up earlier.

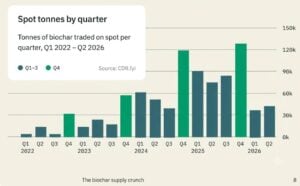
That matters because biochar has traditionally had a two-speed market. Large buyers secure future supply through offtakes in the first half of the year, while smaller buyers typically turn to the spot market later in the year.

biochar offtake

But in 2026, that pattern has become much more pronounced.

Why High-Quality Biochar Is Harder to Find

The biochar market can look well supplied at first glance.

There are hundreds of projects across different stages of development, ranging from large industrial pyrolysis facilities to smaller distributed systems and artisanal production.

However, total capacity does not necessarily equal usable carbon removal supply.

Supercritical evaluated more than 400 biochar projects through its climate science process and found only 13 that passed its full assessment. Its 2026 report evaluates 119 projects using a 118-point vetting framework covering feedstock, production conditions, carbon stability, permanence, additionality, monitoring and verification.

This distinction matters for companies purchasing carbon removals.

For example, a project may be registered or rated but still have problems with additionality, methane emissions, delivery reliability or site-level safety.

One project Supercritical reviewed failed because it produced biochar at multiple open-pit sites without methane monitoring. Another failed an additionality assessment because the facility existed before the changes being credited. A smaller operation was also rejected because it lacked a meaningful delivery history.

So, while biochar production is expanding, high-integrity supply is a much smaller market.

The Market Is Moving Toward Long-Term Contracts

The growing preference for offtakes could reshape the biochar market.

Non-Microsoft buyers purchased more biochar in the first half of 2026 than they purchased during all of 2025. Most of that increase came from multi-year offtake agreements.

Part of the reason is that companies are beginning to plan carbon removal as a long-term component of their net-zero strategies rather than as an annual purchase.

Supercritical points to the Science Based Targets initiative’s Corporate Net-Zero Standard v2, which makes permanent carbon removal mandatory from 2035, eventually requiring removals for residual emissions. The EU’s Carbon Removal Certification Framework also certified biochar as a permanent removal pathway in February 2026.

As these frameworks develop, companies have more reason to secure future supply before they actually need it.

That creates a difficult position for buyers that rely on the spot market.

  • By July, 81% of high-quality 2026 supply had already been committed through offtakes and exclusive agreements. Supercritical estimates that active corporate RFPs could potentially claim another 70% of what remains.

Why Biochar Prices Could Rise Later in the Year

Timing is becoming increasingly important.

Historically, the fourth quarter has been the busiest period for biochar spot purchases. In Q4 2025, 994 spot transactions moved about 125,000 tonnes, with an average deal size of roughly 125 tonnes.

Thus, the three factors driving the late-year rush are:

  • Emissions needs become clearer: Companies often finalize their emissions data later in the year, pushing some buyers to the spot market to cover their remaining needs.
  • Project shortfalls tighten supply: Supercritical found that 73% of biochar projects lowered their capacity forecasts in 2025. Buyers may turn to spot credits when contracted volumes fall short.
  • New supply takes time: Biochar credits must go through production, verification, and registry approval before issuance, often bringing fresh supply to market when demand is already rising.
biochar demand and supply
Source: Supercritical

The result is a market where fresh supply and peak demand can collide toward the end of the year.

And prices already show the effect.

Supercritical reported that a biochar credit from the same project sold for $155 per tonne in July 2025 but reached $185 per tonne by November.

The report says high-quality biochar prices have remained broadly stable since 2024, but seasonal demand can push spot prices higher during the second half of the year.

That suggests the issue is not simply whether biochar is becoming more expensive. It is whether buyers are willing to wait until the market is most competitive.

India Is Becoming an Important Biochar Market

The supply story also highlights India’s growing role in biochar carbon removal.

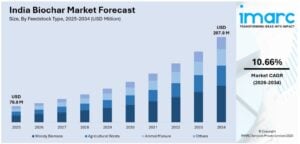
  • The country’s biochar market grew from $79.8 million in 2025 to $92.4 million in 2026. According to IMARC Group, the market is expected to reach $207.9 million by 2034, growing at a 10.66% CAGR from 2026 to 2034.
india biochar

Supercritical’s 2026 portfolio includes several Indian projects, including Varaha’s distributed biochar operation and Ground Up’s project using sugarcane residues.

Varaha’s model uses cotton stalks that might otherwise be burned, as well as the invasive Prosopis juliflora shrub. Its biochar is verified through Isometric, with batches tracked from production to soil.

Ground Up is already issuing credits through Isometric. According to Supercritical, field trials have shown potential yield increases of up to 38% for local sugarcane and 59% for wheat.

This points to one of biochar’s biggest advantages: the technology can connect carbon removal with agricultural waste management and soil applications.

India’s large agricultural residue base could therefore become an important source of future biochar supply, provided projects can meet the required standards for emissions monitoring, permanence, additionality, and verification.

The Bigger Problem Is Scaling High-Quality Supply

Biochar has already delivered more than twice the volume of all other permanent carbon removal pathways combined, according to Supercritical. It is also currently the only permanent removal method with a liquid spot market.

But its next challenge is not simply building more projects.

It is building projects that can reliably deliver high-quality removals at scale.

Supercritical says 73% of biochar projects revised their capacity downward in 2025. That highlights another risk for buyers: announced capacity can look very different from actual deliveries.

For corporate buyers, this makes due diligence increasingly important. Registry certification and third-party ratings can provide a starting point, but they may not answer every question about a project’s operations or ability to deliver.

As the market matures, buyers are likely to place greater value on projects with proven production records, robust monitoring and reliable feedstock.

The supply crunch is taking shape…

The biochar market is shifting from rapid growth to a race for reliable, high-quality supply. Demand is rising, while companies are signing larger offtakes and committing projects earlier. As a result, buyers who wait for the spot market could face higher prices and fewer choices.

Meanwhile, developers with reliable production and strong carbon accounting can capture more corporate demand.

The post Biochar Demand Hits 2.99 Million Tonnes: Can Corporate Buyers Trigger a Supply Crunch? appeared first on Carbon Credits.

Free EU Carbon Allowances Boosted Airline Profits More Than Green Investment, Report Finds

Free EU Carbon Allowances Boosted Airline Profits More Than Green Investment, Report Finds

European airlines received billions of euros in free carbon allowances under the EU Emissions Trading System (EU ETS), but most of the benefit appears to have supported airline profits rather than new green investment. That is the key finding of a new CE Delft report examining free aviation allowances between 2013 and 2025.

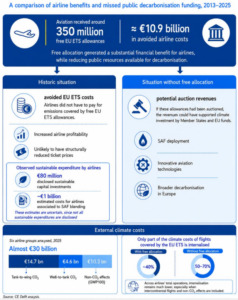
The study estimates airlines received €10.9 billion worth of free EU allowances during the period. By comparison, six major airline groups spent about €1.1 billion on sustainable activities, mainly sustainable aviation fuel (SAF). The findings come as the EU completes its phase-out of free aviation allowances in 2026.

Airlines Received €10.9 Billion in Free Allowances

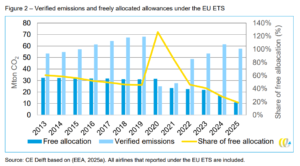
The EU originally provided free allowances to airlines to limit competitiveness concerns and reduce the risk of carbon leakage. Between 2013 and 2025, airlines received about 350 million free allowances, covering roughly half of the 700 million tonnes of verified aviation emissions reported under the EU ETS during the period.

The value of those allowances increased sharply as carbon prices rose.

CE Delft estimates the average EU allowance price increased from about €4.56 per tonne in 2013 to €73.43 in 2025, measured in 2025 prices. The annual average reached about €87.90 per tonne in 2022.

That made free allowances increasingly valuable to airlines, particularly during the years when carbon prices were high. The largest benefits came in 2022 and 2023, when airlines continued receiving free allowances while EU carbon prices remained elevated.

The author noted:

“We find no strong reason to expect that these expenditures would have been substantially lower without free allocation. EU ETS auction revenues, on the other hand, are largely used for climate and energy transition purposes. Full auctioning of aviation allowances would therefore most likely have made significantly more funding available for the decarbonisation of the European economy.”

Free Allocation Became a Major Profit Booster

CE Delft compared airline profitability with a scenario in which airlines had to purchase all their EU allowances. The six airline groups studied were Ryanair, Lufthansa, Air France-KLM, easyJet, Wizz Air and IAG.

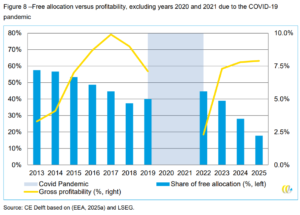
For five major European airline groups that were profitable over the period, the report estimates that free allocation accounted for about 17% of profitability. For Air France-KLM, which recorded cumulative losses, free allowances reduced those losses by about 10%.

Verified emissions and freely allocated allowances under the EU ETS
Source: CE Delft

The report also finds little evidence that ending free allocation has seriously damaged airline profitability. European airline margins during 2023–2025 were broadly comparable with pre-pandemic levels, even as free allocation declined sharply.

That does not mean airlines would face no costs from buying all their allowances. But it weakens the argument that free allocation was essential to protect the sector’s financial performance.

Free allocation versus profitability
Source: CE Delft

Green Spending Fell Far Behind the Carbon Windfall

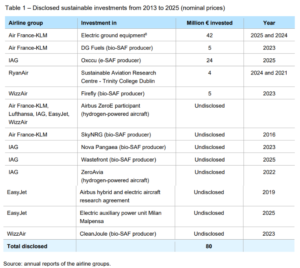
The biggest concern raised by the report is the gap between the value of free allowances and spending on sustainable activities. The six airline groups spent approximately €80 million on sustainable capital investments during the period studied.

They also spent an estimated €1 billion on SAF purchases. Combined, that is roughly €1.1 billion, compared with the €10.9 billion estimated value of free carbon allowances.

CE Delft also examined 2025 EU Taxonomy reporting from eight airlines. The airlines reported a combined €18.1 billion in capital expenditure. About €9.57 billion, or 52.8%, was classified as taxonomy-aligned.

However, almost all of that spending — €9.55 billion — was classified as transitional activity, mainly conventional aircraft purchases and maintenance.

Only €24 million, or 0.13% of total reported capital expenditure, was classified as genuinely sustainable investment. This consisted of electric ground-handling equipment reported by Air France-KLM.

sustainable investments from 2013 to 2025

The distinction matters because newer aircraft can use less fuel than older models but still rely mainly on fossil-based jet fuel.

Could Auction Revenue Have Delivered More?

The report argues that governments could have used auction revenue to support technologies that can cut aviation emissions. CE Delft models several hypothetical uses for the €10.9 billion in free allowances.

If the money had instead been used to purchase HEFA-based SAF, the report estimates it could have supported about 18 million tonnes of CO₂ reductions. Using synthetic SAF could have produced about 4.7 million tonnes of reductions.

The report also estimates that putting the money into the EU Innovation Fund could theoretically have generated up to 815 million tonnes of reductions across sectors. These are not actual historical savings. They are illustrative scenarios based on different technology and investment assumptions.

Still, they highlight the potential opportunity cost of giving carbon allowances to airlines rather than auctioning them.

The wider EU ETS has already become a major source of climate funding. EU ETS auctions generated more than €258 billion between 2013 and 2025, with revenues exceeding €43 billion in 2025, according to the European Commission.

Aviation’s Carbon Costs Remain Partly Unpriced

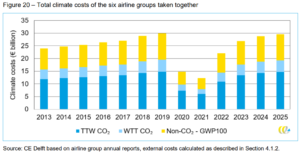
The report also examines aviation’s wider climate impact. For the six airline groups, CE Delft estimates their external climate costs reached almost €30 billion in 2025.

That included about €14.7 billion from direct aircraft CO₂ emissions, €4.6 billion from fuel-production emissions and €10.3 billion from non-CO₂ climate effects. These figures show why aviation’s climate impact extends beyond the CO₂ covered by the EU ETS.

Total climate costs of the six airline groups
Notes: TTW (tank-to-wing), WTT (well-to-tank), Source: CE Delft

CE Delft estimates that carbon pricing has internalized around 40% of the external cost of direct CO₂ emissions within the EU ETS scope in recent years. But the picture changes when international aviation and non-CO₂ effects are included.

For 2025, the report estimates only 16% of CO₂-related external costs were internalized when intercontinental aviation was included. Non-CO₂ effects, including climate impacts linked to aircraft emissions at altitude, remain much less covered by carbon pricing.

Europe Finally Ends Free Airline Allowances

The EU has now entered a new phase for aviation carbon pricing. Under the 2023 EU ETS reforms, free aviation allowances were reduced by 25% in 2024 and 50% in 2025. From 2026, regular free allocation has ended, and aviation allowances are auctioned.

The change means airlines now face a clearer market-based carbon cost for their EU ETS emissions. At the same time, the EU is directing carbon market resources toward aviation decarbonization.

  • Between 2024 and 2030, up to 20 million EU ETS allowances will be used to help narrow the cost gap between eligible SAF and conventional jet fuel.

EASA expects aviation emissions covered by the EU ETS to reach about 59.5 million tonnes in 2026. It estimates airlines could need to purchase about 34.5 million allowances this year. That makes the price of carbon increasingly important to airline costs.

# Philippines Builds Forest Carbon Roadmap as New Climate Target Raises Demand for FinanceThe Philippines is moving to turn its forests into a larger source of climate finance as it takes on a tougher emissions target. The country has adopted a **2026–2030 roadmap for the voluntary forest carbon market** and is building the registry, monitoring systems and policies needed to attract private investment into forests. The move comes just days after the Philippines submitted its updated **2026 Nationally Determined Contribution (NDC)** to the UN climate process. The new NDC keeps the country's **75% emissions reduction and avoidance target**, but changes the structure. The target now covers **2025–2035** and includes forestry and other land use (FOLU). Of the 75% target, **7% is unconditional**, while **68% depends on international support**. That makes forest carbon more than a conservation opportunity. It could become one tool for helping the Philippines secure investment needed to deliver its broader climate targets. ## Philippines Puts Forests at the Center of Its Climate Strategy The Philippines' new NDC gives forests a much larger role in its emissions pathway. The 2026 NDC covers energy, transport, industrial processes, agriculture, waste, and forestry and other land use. Updated government modelling shows the FOLU sector has been a **net carbon sink since 2020**. The NDC estimates that FOLU policies could reduce cumulative emissions by about **2.3 billion tonnes of CO₂e between 2025 and 2035** compared with the business-as-usual pathway. With all identified policies and measures, the country is projected to become a **net sink over the 2025–2035 period**. That makes protecting and expanding the forest carbon sink important to the country's overall climate strategy. The NDC also commits the Philippines to maximizing the potential of that sink through forest protection, reforestation and sustainable land management. ## A Five-Year Roadmap for Forest Carbon The Department of Environment and Natural Resources (DENR) formally adopted its **Roadmap to Readiness in the Voluntary Forest Carbon Market 2026–2030** through Administrative Order No. 2026-02. The roadmap identifies four priorities: 1. **Policy and regulatory frameworks** 2. **Data, monitoring, reporting and verification** 3. **Institutional capacity** 4. **Sustainable financing and market development** The goal is to make the Philippines more attractive for high-quality forest carbon projects while creating safeguards around carbon ownership, benefit sharing and environmental integrity. The roadmap also calls for a **DENR Forest Carbon Credit Database** that will track forest carbon projects and credits. It is designed to connect with a broader national carbon registry being developed under the country's Article 6 framework. This infrastructure matters because buyers increasingly want evidence that credits are real, additional and not counted twice. ## Philippines Has 7.23 Million Hectares of Forest The economic opportunity is significant. The DENR roadmap estimates that the Philippines has about **7.23 million hectares of remaining forest**, equal to roughly **24% of the country's land area**. The document estimates that around one-third is closed-canopy forest and two-thirds is open forest. These forests provide more than carbon storage. They also protect watersheds, reduce soil erosion, support biodiversity and provide livelihoods for local communities. But forest finance remains a major challenge. The roadmap estimates that global investment in forests is only about **$2.2 billion per year**, compared with more than **$450 billion annually** needed to meet international forest and climate goals. Carbon finance could help close part of that gap by creating a revenue stream tied to measurable forest protection and restoration. The Philippines is therefore trying to move from short-term conservation funding toward longer-term investment models. ## The Market Is Still at an Early Stage Despite the potential, the Philippine forest carbon market remains small. The DENR roadmap says there were **no nationally issued carbon credits** at the time of its stocktake. Existing credits had been issued through international standards. The government identified **two projects registered under Verra's Verified Carbon Standard**, with four additional projects in the pipeline. At least **nine other forest carbon projects** were also identified outside the Verra system. Several projects are located in Mindanao, while other opportunities are being explored in areas covered by community forest agreements, ancestral domains and other forest tenure arrangements. The roadmap also identifies **1.2 million hectares of classified forest land** as priority investment areas for reforestation, agroforestry and other forest-based development. Another **1.5 million hectares** are being assessed for possible release for future development. That could significantly expand the potential project pipeline. But land tenure, carbon rights and benefit sharing remain important hurdles. ## CarbonPH Pushes the ASEAN Opportunity This is where the recent **CarbonPH Coalition** initiative becomes important. At a CarbonPH Coalition Education Series session, DENR officials outlined plans to strengthen forest carbon project registration, establish carbon baselines and expand monitoring. The DENR Forest Management Bureau is also developing a registry to track projects and projected credits while using satellite-based monitoring to improve verification. The Philippines is also seeking a stronger position in the **ASEAN Common Carbon Framework (ACCF)**. The country currently participates as an observer, while the regional initiative works on stronger carbon-market infrastructure, supply integrity, demand and interoperability. That could give Philippine forest projects access to a wider pool of regional buyers if standards and systems become more connected. Regional competition is already growing. Malaysia has a government-backed carbon exchange, while Indonesia and Thailand are also developing carbon-market infrastructure. For the Philippines, credible forest projects could become a way to compete on quality rather than simply price. ## Carbon Finance Must Also Deliver for Communities Scaling forest carbon will require more than satellites and registries. The DENR roadmap identifies **benefit sharing** as a major gap. Developers will be required to submit benefit-sharing plans, but the roadmap says further guidance is still needed to determine how revenues should be distributed. That issue is especially important because many potential projects overlap with communities, forest tenure holders and Indigenous Peoples. The roadmap calls for stronger safeguards and recognition of **Free, Prior and Informed Consent (FPIC)** where projects affect ancestral lands and domains. The credibility of Philippine forest credits will therefore depend not only on how much carbon they remove or avoid, but also on whether local communities receive meaningful benefits. ## International Finance Is the Bigger Climate Test The forest carbon roadmap fits directly into the Philippines' broader climate-finance challenge. The new NDC says implementation depends on access to **accessible, predictable and adequate international support**. The government is seeking finance through public and private sources, including innovative financing instruments. It also says climate support should be **highly concessional, non-debt creating and accessible through simplified mechanisms**. The structure of the new NDC makes this particularly important. Only **7% of the 75% target is unconditional**. The remaining **68 percentage points are conditional on international support**. That means finance, technology and capacity building are not secondary issues. They are central to delivering the country's climate commitment. Carbon markets could become one part of that financing mix. The new NDC also recognizes **Article 6** mechanisms as tools for international cooperation and resource mobilisation. Any international transfers, however, will require strong governance, monitoring and safeguards against double counting. ## Forest Carbon Could Link Climate Goals and Investment The Philippines now has two pieces of a potentially important climate-finance strategy. The **2026 NDC** places the country's forest sink directly inside its emissions pathway. The **2026–2030 forest carbon roadmap** is building the policies, data systems, registry and financing mechanisms needed to attract investment into that forest base. The CarbonPH Coalition is adding a private-sector platform to connect those developments with emerging ASEAN carbon markets. But the opportunity is still at an early stage. The country needs clearer carbon rights, reliable monitoring, workable tenure rules and transparent benefit sharing before forest carbon can scale. It also needs international finance to help develop projects that may not be commercially viable on carbon revenue alone. If those pieces come together, Philippine forests could play a larger role in both **emissions reduction and climate finance**. The bigger test is whether the country can turn its **7.23 million hectares of remaining forest** and its expanding carbon-market infrastructure into credible, investable climate assets while ensuring that communities and ecosystems share in the value.
Source: CE Delft

The Next Test for Aviation Carbon Policy

The CE Delft report does not show that free allowances had no value to airlines. Instead, it raises a broader question about whether the policy delivered enough climate benefits for its cost.

The report was commissioned by Opportunity Green, so its policy recommendations should be considered in that context. Its analysis, however, uses EU ETS data, airline financial reports, EU Taxonomy disclosures and other published datasets.

With free allocation now ending, the focus shifts to what happens next. A stronger carbon price can increase the cost of flying while creating revenue for climate investment.

The challenge for Europe is to ensure that those revenues help scale technologies such as SAF, synthetic fuels, and eventually hydrogen and electric aviation.

For the EU’s carbon market, the goal is no longer simply putting a price on aviation emissions. It is turning that price into measurable progress toward cleaner flight.

The post Free EU Carbon Allowances Boosted Airline Profits More Than Green Investment, Report Finds appeared first on Carbon Credits.

Brazil Eyes China as Carbon Credit Buyer Ahead of Potential COP31 Accord

Brazil Eyes China as Carbon Credit Buyer Ahead of Potential COP31 Accord

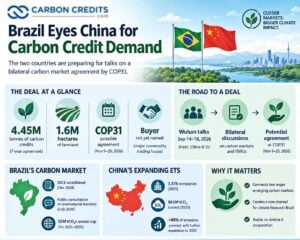
Brazil is looking to China as a potential buyer of its carbon credits as it works to build a stronger international carbon market. Brazilian officials are preparing for talks with China that could lead to a bilateral carbon market agreement by COP31 in November. The discussions will focus on whether China could purchase Brazilian Internationally Transferred Mitigation Outcomes (ITMOs) under Article 6 of the Paris Agreement.

The talks come as Brazil builds its own regulated carbon market and China expands the world’s largest emissions trading system. A deal would connect two major emerging carbon markets and could create a new channel for climate finance in Brazil.

Brazil Targets China for Carbon Credit Demand

Brazil will send a carbon market delegation to Wuhan from September 14 to 18. Officials from Brazil, China, and the European Union will meet there as part of a larger carbon market coalition.

Brazil’s Ministry of Finance confirmed that the Wuhan meetings will include bilateral discussions between Brazil and China on carbon markets. The talks follow earlier discussions at the China-Brazil High-Level Coordination and Cooperation Committee, or COSBAN, held in Beijing in June.

Brazilian carbon market officials are also exploring whether China could become a buyer of Brazilian ITMOs.

If it works, this deal would be important. China lacks an official bilateral ITMO trading agreement with any other country, according to Brazilian officials mentioned by Reuters.

Brazil wants to move quickly enough to potentially announce an agreement at COP31 in Antalya, Türkiye, which runs from November 9 to 20. However, talks have not yet resulted in a finalized deal. The two countries still need to agree on the rules, eligible projects, and other conditions for any future transfers.

Brazil Is Building Its Own Carbon Market

The push toward international carbon trading comes as Brazil develops its domestic carbon market. The nation established the Brazilian Emissions Trading System (SBCE) through Law No. 15,042 in December 2024. The system aims to build a regulated market for emissions and carbon assets. It also supports the country’s climate goals.

The government is now working through the detailed rules needed to make the system operational.

In July, Brazil opened a public consultation on rules for international carbon credit transfers. The proposal allows Brazil to join Article 6 cooperation but limits overseas mitigation transfers.

The proposed framework includes a global ceiling of 50 million tonnes of CO₂ equivalent (MtCO₂e) for international transfers. The limit could later be adjusted based on Brazil’s emissions and the economic performance of the mechanism. The proposed rules apply to mitigation outcomes generated during 2031–2035.

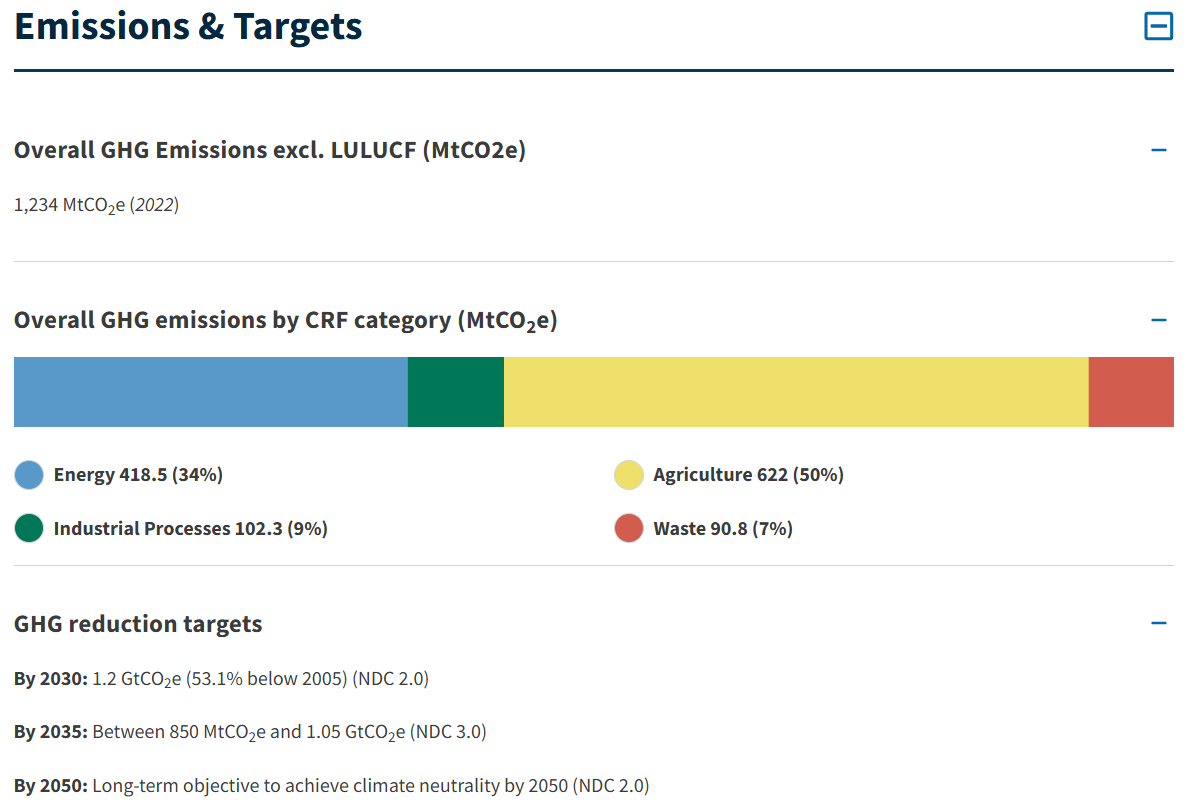
brazil ghg emissions trading system
Source:

Brazil is setting up the legal framework for international carbon trading. However, large-scale exports of ITMOs won’t happen right away.

Why ITMOs Matter

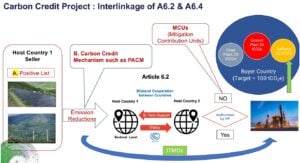
ITMOs are different from ordinary voluntary carbon credits. Under Article 6.2 of the Paris Agreement, countries can cooperate directly and transfer mitigation outcomes toward their climate targets. These transfers need accounting rules. This stops both countries from counting the same emissions reductions.

Carbon Credit generation article 6
Source: UNFCCC

This is where the corresponding adjustment becomes important.

When Brazil authorizes a mitigation outcome for export, it must make the required adjustment to its emissions accounting. This prevents Brazil from using the same reduction toward its own nationally determined contribution (NDC) after another country has used it toward its target.

For Brazil, the system could turn high-quality emissions reductions and removals into a source of international climate finance. The country must choose wisely which reductions to send abroad. It needs to meet its own climate goals too.

Ana Paula Cavalcante, Brazil’s deputy secretary, said:

“Both the coalition and the closer relationship with China can help scale up carbon markets and unlock investment flows for Brazil ​as it seeks to reindustrialize around new technologies.”

China’s Carbon Market Is Expanding

China represents an important potential buyer because its domestic carbon market is becoming larger and more sophisticated. Its national emissions trading system covered 3,378 companies in 2025, including power, steel, cement, and aluminum producers.

Those companies took part in a market that traded 865 million tonnes of carbon allowances. This was worth 57.663 billion yuan for the year. China is also continuing to expand the system.

In 2025, steel, cement, and primary aluminum were added to the national ETS. The expansion means the national market now includes over 60% of China’s total carbon emissions, says China’s Ministry of Ecology and Environment.

China aims to make its national carbon market more comprehensive by 2030. This includes broader coverage, better allowance controls, and a voluntary market that aligns more closely with international standards.

china compliance carbon market ets

That makes China a potentially important future participant in international carbon market cooperation.

Brazil and China Are Already Building Market Links

The potential bilateral agreement is also part of a broader effort to make different carbon markets more compatible. Brazil launched the Open Coalition for Regulated Carbon Markets at COP30. China and the European Union are among its participants.

The coalition focuses on areas such as monitoring, reporting, and verification (MRV), carbon accounting, offset rules, and market interoperability. Brazil says the longer-term goal is to make regulated carbon markets more compatible and potentially allow deeper connections between them.

The coalition now has an important next step in Wuhan.

Brazil, China, and the EU are expected to advance a work plan for improving compatibility between their carbon markets. The group has expanded beyond its original members and now represents a significant share of global emissions.

This wider cooperation could simplify future carbon credit trading. It would create consistent rules for measuring and tracking emissions reductions.

High-Integrity Credits Will Be the Price of Entry

For Brazil, access to China’s market would only be valuable if the credits could meet strict quality requirements.

Brazilian carbon market officials have emphasized the need for high-integrity credits before any international transactions take place. The government’s plan requires that internationally transferred credits follow approved methods. They must also get authorization from Brazil’s national authority.

That requirement is especially important because Brazil has a large pipeline of nature-based climate projects, including forest conservation and restoration.

The government will need to ensure that exported mitigation outcomes are real, measurable, and properly accounted for. Otherwise, international transfers could create risks for Brazil’s own climate targets. The same issue applies to China. Any future bilateral market must provide confidence that credits bought by Chinese entities or the Chinese government represent genuine emissions reductions.

BRAZIL CHINA Carbon credit cop31

COP31 Could Become the Next Carbon Market Milestone

The next two months could be important for Brazil’s international carbon market strategy. The September 14–18 Wuhan meetings could advance Brazil-China talks, while COP31 in November could provide a potential deadline for announcing a bilateral framework.

Still, expectations should remain measured. Brazil is implementing its domestic carbon market, while its international transfer rules are still being developed. China is also refining its own ETS.

A Brazil-China agreement would not immediately create a large carbon credit market. Instead, it could establish the rules and institutional foundation for future ITMO transactions.

That would still be significant. Brazil has major potential for emissions reductions and removals, while China has a large and expanding carbon market. Linking the two could open a new channel for climate finance and strengthen Article 6 trading among two major emerging economies.

The bigger question is whether they can build a system that makes cross-border carbon trading credible, transparent, and scalable. If an agreement is reached by COP31, it could become an important test of how major developing economies use Article 6 to finance decarbonization.

The post Brazil Eyes China as Carbon Credit Buyer Ahead of Potential COP31 Accord appeared first on Carbon Credits.

China’s Battery EV Market Grows as Tesla (TSLA Stock) Posts Third Straight Monthly Sales Decline

China’s Battery EV Market Grows as Tesla (TSLA Stock) Posts Third Straight Monthly Sales Decline

China’s electric vehicle market is showing a growing split between battery electric vehicles (BEVs) and other powertrains. The country’s overall passenger vehicle market fell sharply in August. Yet, BEV sales increased year over year, while plug-in hybrids, extended-range EVs and gasoline-powered vehicles all declined.

The shift is also exposing a tougher problem for Tesla. The company’s China retail sales fell for a third consecutive month, even as the broader BEV market expanded.

The latest figures show how quickly China’s auto market is changing. They also highlight the growing role of electrification in cutting oil demand and transportation emissions.

China’s Auto Market Slumps, But BEVs Keep Growing

China’s passenger vehicle retail market dropped 23.6% year-over-year in August, according to China Passenger Car Association (CPCA) data. New energy vehicle (NEV) sales also declined, falling 10.1% to about 1.005 million units. NEVs include BEVs, plug-in hybrids and extended-range electric vehicles.

However, the headline NEV decline masks a major difference between powertrains. BEV retail sales reached 698,000 units in August, up 0.8% from August 2025 and 7.9% from July.

China passenger NEV retail sales august
Source: CnEVPost

Meanwhile, plug-in hybrid sales fell 29.6%, and extended-range EV sales declined 22.2%. Fossil-fuel vehicles, including internal-combustion and conventional hybrid models, plunged about 40%. That made August another important month for China’s transition toward fully electric vehicles.

BEVs did not deliver explosive growth. However, they were the only major powertrain category to post year-over-year growth as the broader auto market contracted.

The result was a record 65.2% NEV penetration rate in China’s passenger vehicle retail market, up from 55.2% a year earlier. In other words, nearly two out of every three new passenger vehicles sold in China in August were NEVs.

Tesla Is Moving in the Opposite Direction

Tesla’s performance stands out because its core product is concentrated in the BEV segment. Tesla sold 50,047 vehicles in China in August, according to CPCA data. That was down 12.4% from 57,152 vehicles a year earlier.

It was also Tesla’s weakest August result in China since 2022. The decline followed a 32.9% year-over-year drop in July and a 14% decline in June, creating three consecutive months of falling China retail sales.

Tesla monthly retail sales in China august
Source: CnEVPost

The month-on-month comparison was better. Tesla’s August sales jumped 83.7% from July, when the company sold only 27,249 vehicles in China.

Still, the rebound was not enough to reverse the underlying annual decline. Through the first eight months of 2026, Tesla’s China retail sales reached 316,251 vehicles, down about 12.4% from the same period last year.

Tesla’s position in China’s NEV market also shows the intensity of competition. The company ranked sixth in August with a 5.0% share of NEV retail sales. BYD led with 233,943 vehicles and a 23.3% share, followed by Geely at 110,560 and Leapmotor at 84,874.

Tesla, therefore, sold less than half as many NEVs as BYD in the Chinese retail market during the month.

China's Aug 2026 NEV retail ranking
Source: CnEVPost

China’s EV Competition Is Getting More Intense

Tesla’s challenge is not simply a weak Chinese auto market. Local manufacturers are continuing to expand their presence across different price points and vehicle categories.

  • Other major players included Changan, SAIC-GM-Wuling, Chery, Huawei-backed HIMA, Li Auto, Nio, Xpeng and Xiaomi.

The rise of these companies matters because China’s EV market is increasingly driven by competition over price, battery technology, charging speed, software and vehicle features.

The International Energy Agency (IEA) estimates that China’s EV production costs are around 35% lower than in advanced economies, reflecting the country’s integrated battery, materials and manufacturing supply chains. China also accounted for nearly 75% of global electric car production in 2025.

Tesla once had a much larger position in this market. Reuters reported that Tesla’s share of China’s BEV sector fell to 6.6% in the second quarter of 2026, compared with more than 15% in 2020.

That decline shows the structural change underway. Tesla helped establish the premium mass-market EV category in China, but domestic manufacturers now have increasingly competitive alternatives.

Tesla Stock Reaction

Tesla shares showed little reaction to the August China sales figures. TSLA stock rose about 0.3% on September 9, even as Tesla’s China sales fell 12.4% from a year earlier.

Tesla TSLA stock price

Investors are looking beyond the latest sales numbers. Tesla’s stock has also been affected by concerns over its slowing vehicle sales, rising competition in China and uncertainty around its robotaxi and Cybertruck plans.

The bigger concern is the growing gap between Tesla and China’s broader BEV market. China’s BEV sales increased in August, while Tesla’s sales fell for a third straight month. This suggests Tesla is facing stronger competition, rather than simply a weaker EV market.

China Is Turning to Exports as Domestic Demand Weakens

China’s weakening domestic market is also pushing automakers toward international markets. Passenger vehicle exports reached 894,000 units in August, up 77.5% year over year, even as domestic sales fell 23.7%.

NEV exports were particularly strong, rising 154.7% from a year earlier. NEVs represented 58.4% of China’s passenger vehicle exports during the month. The trend extends beyond August.

IEA data show that Chinese electric car exports increased by more than 120% in the first half of 2026, fully offsetting the decline in domestic electric car sales. Electric vehicles accounted for more than 45% of China’s car exports, compared with around 35% in 2025.

Tesla is also increasingly using Shanghai as an export hub. The EV giant exported 36,119 vehicles from its Shanghai factory in August, up 38.7% year over year. However, that was down 45.6% from July’s record 66,330 exports.

The contrast is important. Tesla’s China retail market is shrinking, while its Shanghai factory is increasingly serving international markets. Chinese automakers face a similar dynamic, but their export growth has been substantially faster.

Electric Cars Are Starting to Cut China’s Oil Demand

The shift toward BEVs also has consequences beyond the auto industry. China is the world’s largest oil importer and has the world’s largest EV fleet. The IEA estimates that EVs already displaced around 1 million barrels of oil per day in China in 2025.

That figure could reach 2.7 million barrels per day by 2030 under current policies. Recent data suggest the effect is becoming visible in national energy statistics.

China’s carbon dioxide emissions fell 1% year over year in the second quarter of 2026, according to analysis by the Centre for Research on Energy and Clean Air (CREA). Oil consumption fell about 9%, while transport oil use dropped 16%.

CREA estimated that EVs displaced around 36 million tonnes of oil during the first half of 2026, contributing to an estimated 35 million tonnes of carbon emissions reductions after accounting for emissions from EV charging.

Net avoided greenhouse gas emissions from EV deployment, 2025-2035
Source: IEA

Sinopec’s research arm now expects China’s oil demand to decline by 600,000 barrels per day, or 8.9%, in 2026. Gasoline demand is forecast to fall 8.7%, while diesel demand could decline 11.4%.

EV adoption is not the only factor behind those changes. Higher oil prices, weaker economic activity, and changes in industrial demand also matter. Still, transportation electrification is becoming an increasingly important structural factor.

China’s EV Boom Is Becoming a Global Export Story

China’s auto market is under pressure, but BEVs are still gaining ground as gasoline vehicles lose share. At the same time, Chinese automakers are taking their EVs into overseas markets, increasing competition in Europe, Southeast Asia and other regions.

The IEA says China produced nearly 75% of the world’s electric cars in 2025, while Chinese brands accounted for more than half of EV sales in Southeast Asia.

Tesla faces a different challenge. Its August sales fell even as China’s BEV market grew, showing that stronger competition is hurting its position in the world’s largest EV market.

The long-term outlook for China’s EV market remains strong. The IEA expects EVs to make up more than 60% of China’s car sales in 2026 and more than 90% by 2035.

The shift also has climate implications. More BEVs can reduce oil demand and transport emissions while increasing demand for cleaner electricity and batteries.

READ MORE: China’s New 2030 Climate Playbook and What It Means for the EV Market

The post China’s Battery EV Market Grows as Tesla (TSLA Stock) Posts Third Straight Monthly Sales Decline appeared first on Carbon Credits.

Singapore Targets 12 Million Carbon Credits in Major Article 6 Tender

Singapore Targets 12 Million Carbon Credits in Major Article 6 Tender

Singapore has opened the second stage of a tender to buy at least 12 million Internationally Transferred Mitigation Outcomes (ITMOs) under Article 6 of the Paris Agreement. The tender opened on September 7, 2026, by the Ministry of Trade and Industry (MTI). Only bidders that passed the first stage can now submit detailed project proposals. A briefing for pre-qualified bidders is scheduled for September 23.

The tender marks a major step in Singapore’s plan to secure more international carbon credits. It also shows that the country is moving from signing Article 6 agreements to buying actual future credit supply.

However, the 12 million tonnes are a procurement target, not credits already issued. Projects must still be approved, monitored, and independently verified.

Singapore Is Scaling Up Carbon Credit Purchases 

The new tender is much larger than Singapore’s first major government carbon purchase. In September 2025, the country agreed to buy 2.175 million tonnes of nature-based carbon credits from four projects in Ghana, Peru and Paraguay. The deals were worth about S$76 million, with deliveries planned from 2026 to 2030.

The new tender seeks more than five times that volume.

It also covers a wider range of projects. Singapore says the procurement can include nature-based and technology-based projects. That could include renewable energy, methane reduction, industrial projects and carbon removal, depending on the final eligibility rules.

The tender could therefore become an important source of demand for developers seeking long-term buyers for future Article 6 credits.

Article 6 Creates a Different Type of Carbon Market

Article 6.2 allows countries to transfer emissions reductions between countries. These units are known as ITMOs: Internationally Transferred Mitigation Outcomes.

A key safeguard is the corresponding adjustment. It stops both countries from counting the same emissions reduction toward their climate targets.

Carbon Credit generation article 6
Source: UNFCCC

For example, if a project in a host country creates an authorised mitigation outcome and transfers it to Singapore, the host country must adjust its emissions accounting. It cannot also count the same reduction toward its own climate target.

This is an important difference between Article 6 transactions and many voluntary carbon market deals. Singapore’s bilateral Implementation Agreements create the framework for project approval, reporting, authorization, and corresponding adjustments.

Why Singapore Needs More International Carbon Credits

Singapore has limited land and fewer options for large-scale domestic carbon removals. International credits therefore form an important part of its climate strategy.

The country aims to reduce emissions to 45–50 million tonnes of CO2 equivalent by 2035 and reach net zero by 2050.

Singapore article 6 network and partnerships

Singapore has estimated that it could need around 2.51 million tonnes of ITMOs each year during its 2021–2030 NDC period. The government plans to secure eligible credits through both direct procurement and its carbon-tax system.

That makes the new 12-million-ton tender important. The volume is large enough to build a bigger supply pipeline, rather than relying mainly on smaller individual deals.

Carbon Tax Creates Another Source of Demand

Singapore’s carbon tax adds another reason to expand the supply of eligible credits. The tax applies to industrial facilities that emit at least 25,000 tonnes of CO2e a year. It covers about 70% of Singapore’s national emissions, according to the government.

The carbon tax rose from S$25 per tonne in 2025 to S$45 per tonne in 2026 and 2027. Singapore plans to raise it to S$50–S$80 per tonne by 2030.

Since 2024, covered companies can use eligible international carbon credits for up to 5% of their taxable emissions. This creates a direct link between Singapore’s domestic carbon price and its international carbon market.

As the tax rises, demand for eligible credits could also increase, provided those credits meet Singapore’s rules.

Quality Matters as Much as Carbon Volume

Singapore is not simply looking for large volumes of cheap credits. Its eligibility rules require projects to meet key principles such as additionality, accurate measurement, permanence, transparency, and no double counting.

The country has also introduced additional safeguards for some project types. For example, certain renewable energy projects face extra requirements because Singapore wants to avoid using credits for projects that may already be financially viable without carbon revenue.

Singapore also requires cancelling 2% of authorized credits at issuance to support an overall reduction in global emissions. Another 5% of proceeds must support adaptation in host countries or the UNFCCC Adaptation Fund. These measures reduce the number of credits available for use, but they are intended to improve environmental integrity.

The Biggest Challenge: Turning Deals Into Real Credits

The large tender also reflects a simple problem: eligible Article 6 credits take time to develop. Singapore says carbon projects can take up to four years to generate credits. That makes early procurement important for companies and governments that need supply later.

Signing an Article 6 agreement also does not automatically create credits. Projects must be identified, approved, and monitored. Host countries must authorise the relevant mitigation outcomes, while developers must meet Singapore’s eligibility and verification requirements.

This creates a gap between policy agreements and actual carbon supply. The new tender is designed to help close that gap by bringing more projects into the pipeline now.

Singapore Is Building a Regional Carbon Network

The tender is part of a wider effort by Singapore to build a network of Article 6 partners across Asia and other regions.

Singapore has signed Implementation Agreements with countries including Ghana, Bhutan, Chile, Mongolia, Papua New Guinea,
Peru, Rwanda, Paraguay, Thailand, Vietnam and the Philippines. Laos also signed an Implementation Agreement with Singapore in September 2026.

Singapore article 6 network and partnerships

This network gives Singapore a wider pool of potential projects. It also gives developing countries access to a buyer that is seeking credits that meet government standards.

That could encourage more investment in projects involving forests, clean energy, methane reduction, waste and other emissions reduction activities.

Carbon Finance Could Benefit Host Countries

The impact of the tender could extend beyond Singapore. Carbon projects often require large upfront investments. Revenue from future credits can help improve the economics of projects that might otherwise struggle to secure financing.

Singapore has also committed US$15 million to the Global Green Growth Institute’s Carbon Transaction Facility and established a Singapore Article 6 Carbon Facility to support project development and capacity building.

The combination of project financing, technical support and future credit demand could help countries develop stronger carbon market infrastructure. The benefits may also include renewable energy, better land management, rural income and other development gains, depending on the projects selected.

The 12M-Ton Tender Puts Article 6 to the Test

The second-stage tender is an important test for the Article 6 market. Singapore has spent years building bilateral agreements and setting strict rules for carbon-credit quality. It is now moving toward a much larger procurement programme.

For developers, the tender could create a major new source of demand. For host countries, it could bring more climate finance. For Singapore, it could help secure the international credits needed for its climate and carbon-tax policies.

The wider message is clear: Article 6 is moving from international climate rules toward real carbon market transactions at scale. As more governments begin to buy credits directly, the quality of those credits will matter as much as their volume.

For the leading carbon buyer in Asia, the new tender is a major step toward building a reliable international carbon supply. For the wider market, it could help turn Article 6 from a policy framework into a functioning source of climate finance.

READ MORE: Singapore and Indonesia Seal Landmark Carbon Credit Deal to Boost Southeast Asia’s Green Economy

The post Singapore Targets 12 Million Carbon Credits in Major Article 6 Tender appeared first on Carbon Credits.
Australia’s Forest Carbon Fight: Greens Split as Senate Backs Forest Credits

Australia’s Forest Carbon Fight: Greens Split as Senate Backs Forest Credits

Australia has taken a major step toward using carbon credits to protect native forests. However, the decision has also exposed a deep split within the environmental movement.

The Senate has rejected an attempt to block the Improved Native Forest Management (INFM) method. This allows the new forest carbon credit system to remain in place.

The Greens were divided. Most of their senators supported the government’s position after securing changes to the scheme. Three Greens senators opposed it. The vote highlights a bigger question for Australia’s carbon market:

Can carbon credits help protect forests without allowing companies to rely on offsets instead of cutting their own emissions?

Australia’s Senate Clears a New Path for Forest Carbon

The Coalition tried to disallow the INFM method, arguing that it could affect Australia’s native forestry industry. The motion was defeated 34 votes to 27, allowing the method to continue.

  • Seven Greens senators supported the government, while Senators Nick McKim, Vanessa Bleyer and Jordon Steele-John voted against it.

The federal government says the method gives states another financial option for protecting public native forests. Under the system, states can generate Australian Carbon Credit Units (ACCUs) by stopping planned timber harvesting in eligible native forests.

The forests can then continue growing and storing carbon. At the same time, emissions linked to harvesting can be avoided.

The government formally approved the INFM method in June 2026. It is scheduled to expire on September 30, 2036, unless extended under Australian law.

How Forest Credits Work

The basic idea is simple. A state identifies a forest that would otherwise be harvested. If logging is stopped through an eligible project, the additional carbon stored in the forest can be counted as emissions reduction.

Projects must use Australia’s Full Carbon Accounting Model (FullCAM) to calculate the carbon benefit. They also face monitoring, reporting and compliance requirements.

The resulting ACCUs can be sold to companies seeking to offset emissions or meet obligations under Australia’s climate policies. For governments, this creates a potential new source of revenue from forest protection.

For environmental groups, however, the question is whether the carbon benefit is genuinely additional. That issue sits at the heart of the debate.

Why the Greens Are Divided

The Greens have long supported stronger forest protection and deeper emissions cuts. But the party remains divided over the role of carbon markets.

Most Greens senators backed the INFM method after negotiating changes with the government. Greens leader Larissa Waters said the party secured stronger safeguards, including restrictions on how credits can be used by coal and gas companies.

Energy Minister Chris Bowen said:

“If you believe in ending native forest logging or moving away from it and reducing it, then you vote for this method.”

Three Greens senators, however, rejected the deal.

McKim, Bleyer and Steele-John argued that carbon credits could allow major polluters to keep emitting while claiming reductions elsewhere. They also said native forests should be protected for their environmental and biodiversity value, rather than mainly because they can generate carbon credits.

Senator McKim noted:

“Labor is holding koalas hostage… and threatening their extinction unless they can profit from their habitat.”

The disagreement reflects a wider debate over whether forest conservation and carbon markets should be linked.

Supporters argue that carbon revenue can make standing forests more valuable than logging them. Critics say forests should be protected through direct government action, without creating credits that companies can use to offset emissions.

Great Koala National Park Could Become the Big Test

The proposed Great Koala National Park in New South Wales is likely to become one of the most important tests of the new system. The proposed park covers about 476,000 hectares, including more than 176,000 hectares of state forest.

Great Koala National Park Australia

The NSW government says the area could protect more than 12,000 koalas, 36,000 greater gliders and habitat for more than 100 other threatened species.

NSW is developing a carbon project under the new INFM method. The plan is to stop timber harvesting and allow the forests to continue growing and storing carbon.

  • Earlier government estimates suggested the project could generate about 6.4 million tonnes of carbon abatement and sequestration over 25 years, including around 3.7 million ACCUs over 15 years.

Those figures were based on an earlier version of the method. They should not be treated as the final credit volume.

The project will now provide an important real-world test of whether carbon finance can support large-scale forest protection.

Additionality Will Make or Break Forest Credits

The Senate vote does not end concerns about the quality of forest carbon credits. One major issue is additionality.

For a carbon credit to represent a real climate benefit, the protection should not have happened without the project. If a forest was already going to be protected, critics argue that issuing credits could create little additional climate benefit.

Another concern is leakage. If logging stops in one forest but moves to another area, some of the claimed emissions benefit could be lost.

The government considered both issues while developing the INFM method. The final rules include requirements to monitor harvesting and account for potential leakage.

The government received 371 submissions during consultation on the draft method. The results will now depend on how the rules work in actual projects.

A New Phase for Australia’s Carbon Market

The forest credit debate comes as Australia’s ACCU market plays a larger role in national climate policy. The credits are increasingly linked to the Safeguard Mechanism, which requires Australia’s largest industrial facilities to manage their emissions.

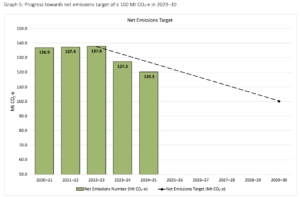
The policy continues to show positive momentum, with a noticeable reduction in industrial footprints during 2024–25. Total gross covered emissions decreased by 2.3% year-over-year to 132.8 MtCO₂e. Meanwhile, net emissions dropped at a faster rate of 5.5%, falling to 120.3 MtCO₂e, highlighting increased compliance and market activity.

Australia progress toward net zero
Source: Clean Energy Regulator

The Climate Change Authority’s latest review said the ACCU system remains fundamentally sound but called for improvements in transparency and information for buyers. It also recommended further work on carbon storage permanence and the treatment of credits from different project types.

The INFM method adds another potential source of ACCUs. Instead of planting new forests, projects can generate credits by keeping existing native forests standing and allowing them to grow.

That could expand Australia’s land-sector carbon market. But forest projects also face risks from fires, drought, pests and other disturbances. Ensuring that credited carbon remains stored will therefore be important for market credibility.

The Real Test: Can Australia Forest Credits Deliver?

Australia’s Senate decision does not settle the debate over forest carbon credits. It does, however, create a path for governments to put a financial value on keeping native forests standing.

The Great Koala National Park could become an early test. If its carbon project delivers real additional emissions reductions while protecting important biodiversity, it could show how carbon markets can support large-scale conservation.

But if credits are issued for protection that would have happened anyway, or if they allow major emitters to delay real emissions cuts, the method could face renewed criticism.

The next stage will, therefore, matter more than the Senate vote itself.

Australia now has to show that forest carbon can deliver both real climate benefits and real forest protection. How that works in New South Wales could influence the future of forest carbon projects across Australia.

The post Australia’s Forest Carbon Fight: Greens Split as Senate Backs Forest Credits appeared first on Carbon Credits.
NextEra Energy Secures $1.9 Billion DOE Loan to Restart Duane Arnold Nuclear Plant in Iowa

NextEra Energy (NYSE: NEE) and the U.S. Department of Energy (DOE) have finalized a loan of up to $1.9 billion. This funds the restart of the Duane Arnold Energy Center in Iowa.

The press release highlights that this financing is a key step in bringing the 615-megawatt nuclear facility back online. The plant shut down in 2020. If it gets the needed regulatory approvals, NextEra aims to restart it by early 2029.

The project aligns with the U.S. goal to boost reliable power as electricity demand grows. Nuclear energy remains vital for America’s low-carbon power landscape.

NextEra’s Energy Mix Spans Nuclear to Renewables

NextEra Energy has a broad energy portfolio spanning renewables, nuclear power, natural gas and battery storage. Through NextEra Energy Resources, the company operates more than 40,000 MW of generating capacity and is expanding its infrastructure to meet rising U.S. electricity demand.

                                NextEra Energy Resources: An Energy Pioneer

nextera
Source: NextEra

John Ketchum, chairman, president and CEO of NextEra Energy, said:

“Restarting Duane Arnold is about delivering new power to meet new demand while generating billions of dollars in economic value for Iowans. Just as importantly, it shows how America can support rapid economic growth and rising electricity demand while helping keep power affordable for existing customers.

By bringing new generation online to serve new demand, we can strengthen the grid, create hundreds of good-paying jobs and help ensure Iowa families and businesses are not asked to bear the costs of growth. We appreciate the Administration’s leadership in advancing America’s nuclear renaissance and share its commitment to an all-of-the-above energy strategy that expands supply, strengthens energy security and keeps America competitive.”

Duane Arnold Restart Adds Nuclear Power to Iowa Grid

Located in Linn County, the Duane Arnold Energy Center ran for over four decades before closing in 2020. NextEra is now navigating licensing, engineering, inspections, and readiness work to restart the facility.

In June, the Iowa Utilities Commission gave NextEra a certificate to construct and operate the facility, marking another milestone.

DOE Backs Nuclear Restarts

The DOE financing comes from its Office of Energy Dominance Financing, which supports efforts to reactivate existing nuclear assets.

For the U.S. power sector, restarting a current reactor offers a different option than building a new one. Duane Arnold already has a developed site and infrastructure, though the restart still needs extensive technical and regulatory work.

Electricity demand is rising nationwide. Data centers, manufacturing, and industrial activities are driving higher power use, highlighting the need for reliable generation that runs continuously.

U.S. Deputy Secretary of Energy James P. Danly said:

“President Trump has set an ambitious course to restore American nuclear leadership, and the restart of Duane Arnold Nuclear Plant in Iowa marks another step in advancing America’s nuclear renaissance. Returning 615 megawatts of reliable baseload generation will drive down electricity costs, while supporting thousands of American jobs.

This Administration is pursuing a comprehensive nuclear strategy, restarting existing reactors, increasing the output of our nuclear fleet, and accelerating new construction, to build the abundant, affordable, and reliable power system required for American prosperity and reindustrialization.”

Nuclear Already Supplies 18% of U.S. Electricity

The scale of America’s nuclear fleet also highlights why restarting existing reactors is becoming a focus of U.S. energy policy. EIA data shows that the country has roughly 98 gigawatts of nuclear generating capacity.

  • Explaining further, the latest EIA Short-Term Energy Outlook forecasts nuclear power to provide 18% of U.S. electricity generation in both 2026 and 2027.
  • At the same time, U.S. electricity sales are expected to reach 4,135 billion kWh in 2026 and 4,211 billion kWh in 2027, driven in part by growing data center demand and increased manufacturing activity.

EIA nuclear

Nuclear plants also operate at high utilization rates, with the EIA reporting an average capacity factor of 91% in 2025.

This reflects the high utilization of nuclear reactors, which operate for long periods. Restarting existing reactors could be crucial as the U.S. seeks reliable power without relying solely on fossil fuels.

$1.9 Billion Financing Supports Nuclear Restart

The Duane Arnold project is set to bring significant economic benefits, too.

  • A study cited by NextEra estimates the recommissioning could create $15.9 billion in economic impact across the U.S. and $9.1 billion in Iowa during construction and 25 years of operation.
  • For Linn County, the study estimates an economic impact of $8.2 billion and $3.2 billion in labor earnings.

The project is expected to generate 393 new full-time jobs during operations, raising total direct employment at the site to about 433 positions. Over its lifetime, it could produce around $75 million in tax revenue.

However, the economic case is just one part of the investment.

Nuclear Restart Fits Into U.S. Energy Strategy

The DOE financing supports the Trump administration’s push to expand U.S. nuclear power and rebuild the domestic nuclear industry.

The administration’s 2025 executive order, “Reinvigorating the Nuclear Industrial Base,” pointed to the country’s slow pace of nuclear development and weakening domestic fuel-cycle infrastructure. It also highlighted growing reliance on foreign reactor designs and nuclear fuel services.

Against this backdrop, restarting existing nuclear plants can help preserve reliable power while the U.S. works to develop new reactors and strengthen its nuclear supply chain.

The DOE said the Duane Arnold financing is the third nuclear plant restart it has supported under the current administration. The 615-MW facility would add more reliable, low-carbon electricity to the Midwest grid and help meet growing power demand.

The project still requires regulatory approvals and further readiness work. However, the $1.9 billion financing moves Duane Arnold another step closer to returning to service.

The post NextEra Energy Secures $1.9 Billion DOE Loan to Restart Duane Arnold Nuclear Plant in Iowa appeared first on Carbon Credits.
Nuclear Power Could Triple by 2050 as It Helps Avoid 43.6 Billion Tonnes of CO₂

nuclear

Global nuclear power is entering a new period of expansion as governments look for reliable, low-carbon electricity to meet rising energy demand.

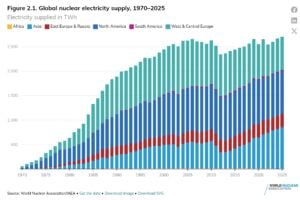
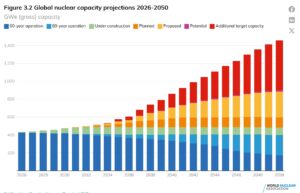
The World Nuclear Association’s (WNA) World Nuclear Outlook Report 2026 finds that national nuclear targets are collectively strong enough to support more than a tripling of global nuclear capacity by 2050. If those ambitions are delivered, global capacity could reach 1,457 GWe by the middle of the century.

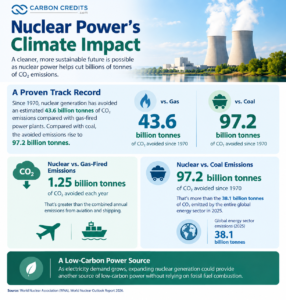
The growth would build on nuclear power’s existing contribution to emissions reductions. Since 1970, nuclear generation has avoided an estimated 43.6 billion tonnes of CO₂ emissions compared with producing the same electricity from gas-fired power plants. Compared with coal, the avoided emissions rise to 97.2 billion tonnes.
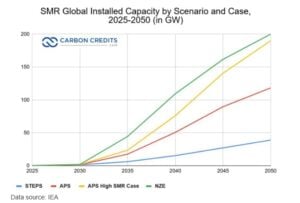
However, the report makes clear that reaching the 2050 target will depend less on setting new ambitions and more on delivering reactors at a much faster pace.

Nuclear Generation Reaches a Record High

Nuclear power already supplies a significant share of global electricity.

  • Worldwide nuclear generation reached a record 2,702 TWh in 2025, up from 2,667 TWh a year earlier. That was enough to provide about 9% of global electricity.

nulcear

The increase was driven largely by Asia. Nuclear generation across the region has risen by approximately 2.5 times since 2012, with China accounting for much of the expansion alongside growing output from countries including India, Pakistan and the United Arab Emirates.

At the same time, nuclear’s share of global electricity has fallen from around 17% in the mid-1990s. That does not mean nuclear generation has declined. Instead, global electricity production has expanded faster than nuclear output.

  • The existing fleet is also performing strongly. The global average reactor capacity factor rose to 83.7% in 2025, compared with 82.9% in 2024.
  • The report found no general decline in performance among reactors operating for more than 40 years.

That strengthens the case for keeping existing plants online while new capacity is built.

nuclear

Nuclear’s Climate Contribution Is Already Significant

Nuclear power’s role in reducing emissions extends well beyond its current electricity output.

Nuclear vs. Gas-Fired Emissions: At today’s generation levels, nuclear power avoids roughly 1.25 billion tonnes of CO₂ emissions every year compared with gas-fired generation. WNA says that is greater than the combined annual emissions from aviation and shipping.

Nuclear vs. Coal Emissions: The comparison with coal is even more significant because coal has a higher carbon intensity.

The report estimates that nuclear generation has avoided 97.2 billion tonnes of CO₂ compared with coal-fired electricity since 1970. That cumulative figure is larger than the 38.1 billion tonnes of CO₂ emitted by the entire global energy sector in 2025.

A Low-Carbon Power Source: As electricity demand grows, expanding nuclear generation could provide another source of low-carbon power without relying on fossil fuel combustion.

Here’s the summary of nuclear’s climate impact in the infographic below:

nuclear emissions

2050: Global Nuclear Capacity Could Reach 1,457 GWe

The report’s central outlook is based on a combination of existing reactors, projects already moving through development, and additional capacity linked to national government targets.

Under its projection, global nuclear capacity reaches 1,457 GWe in 2050. The calculation assumes existing reactors operate for up to 80 years where appropriate, current projects enter service, and additional reactors needed to meet national targets are constructed.

nuclear power 2050

The project pipeline is gradually becoming more concrete.

Capacity under construction increased from 76 GWe to 82 GWe, while planned capacity rose from 107 GWe to 114 GWe. Meanwhile, proposed capacity declined from 294 GWe to 289 GWe and potential capacity dropped from 24 GWe to 13 GWe.

That shift is important because it suggests some projects are moving toward more advanced stages of development.

Still, a substantial gap remains. The report estimates that another 559 GWe would be required beyond identified projects to meet governments’ stated nuclear targets.

China, India and New Nuclear Markets

Most of the projected growth will come from countries that already operate nuclear reactors. Existing nuclear countries are expected to account for 1,303 GWe of the projected 2050 capacity. New nuclear entrants could contribute another 154 GWe.

Five countries — China, France, India, Russia and the US — are projected to account for a combined 986 GWe by 2050.

China is particularly important to the near-term outlook. Nine of the 11 reactors that began construction in 2025 were in China, with the remaining two in Russia.

India also has ambitious plans. The country currently has around 8 GWe of nuclear capacity, providing approximately 3% of its electricity. Its government is targeting 100 GWe by 2047, which would require a major increase in construction and industrial capacity.

Meanwhile, new entrants are beginning to expand the geographic reach of nuclear power. The report expects countries without operating reactors in 2026 to collectively reach 154 GWe by 2050.

nuclear capacity

The Nuclear Buildout Needs to Accelerate

This is where the outlook faces its biggest challenge.

The industry started construction on 11 reactors in 2025, matching the previous year’s total. However, the World Nuclear Association estimates that construction starts would eventually need to reach around six times current levels by the mid-2030s to achieve the tripling objective.

Construction times also vary considerably.

China’s Zhangzhou 2 reactor reached the grid after 62 months, while India’s Rajasthan 7 took 163 months. The report links China’s shorter construction period to its active programme of standardized reactors built in series.

That difference illustrates one of the central lessons of the report: building reactors repeatedly can preserve expertise, strengthen supply chains and allow developers to apply experience from one project to the next.

Countries that build reactors only occasionally face a different challenge. Long gaps can result in the loss of skilled workers and institutional knowledge, while each new project can effectively become a first-of-a-kind undertaking.

Keeping Existing Reactors Online Matters

New construction is only one part of the nuclear expansion strategy.

Currently, 401 GWe of the 423 GWe of nuclear capacity are operating. It could still be in service in 2050 under its operating-life assumptions. Of that amount, 230 GWe would come from reactors operating between 60 and 80 years.

That makes lifetime extensions particularly important.

Furthermore, 46 reactors had already been operating for more than 50 years as of August 2026. Their continued performance demonstrates that reactor age alone does not necessarily prevent reliable operation.

For countries seeking to increase low-carbon electricity quickly, extending the life of existing reactors can therefore complement new construction.

Financing, Fuel and Supply Chains Are Critical

Despite stronger government support, nuclear projects face high upfront costs and long development timelines.

The report argues that financing must move beyond one-off project structures toward repeatable programmes. Governments can reduce investment risk through long-term policy commitments, revenue frameworks, public-private partnerships and appropriate risk-sharing mechanisms. Multilateral development banks and export credit agencies could also help attract private capital.

At the same time, the nuclear supply chain will need to expand. Tripling capacity would require additional manufacturing, construction, specialist engineering, transportation and nuclear-qualified suppliers.

Uranium supply is another potential bottleneck. The report warns that nuclear expansion will require significantly more uranium and says exploration and mine development must accelerate because new projects can take years to develop. Fuel-cycle capacity for conversion, enrichment and fabrication will also need to grow ahead of demand.

SMRs Could Broaden Nuclear’s Role

Small modular reactors could eventually complement large conventional reactors.

The report says SMRs may simplify project delivery, reduce capital requirements per unit and support more flexible financing models. Factory manufacturing and modular construction could also encourage standardization and potentially shorten construction schedules.

However, most SMR designs still require further licensing, demonstration, and first-of-a-kind deployment. Therefore, large reactors are expected to provide most of the capacity added through 2050, even if SMRs become increasingly important.

Nuclear’s role could also extend beyond electricity. Advanced reactors could provide industrial heat, district heating, desalination and energy for synthetic fuels and other hard-to-abate applications.

The International Energy Agency (IEA) also expects strong long-term growth. In its Announced Pledges Scenario, the IEA predicts over 1,000 SMRs to be used worldwide by 2050. This would add up to about 120 gigawatts (GW) of capacity. It also estimates SMR investment could rise from about $5 billion today to more than $25 billion by 2030.

SMR IEA

Nuclear’s 2050 Goal Depends on Delivery

The World Nuclear Outlook 2026 presents a clear contrast between ambition and execution.

Governments have established enough targets to support a tripling of nuclear capacity. The pipeline is also becoming more concrete, with more capacity moving into construction and planned categories.

But those targets will only translate into operating reactors if countries can solve the practical challenges of financing, licensing, construction, fuel supply, manufacturing and workforce development.

For the energy transition, the potential payoff is significant. Nuclear already provides a large source of low-carbon electricity and has helped avoid tens of billions of tonnes of CO₂ emissions over the past five decades.

The next stage will depend on whether the industry can turn that established climate contribution into a much larger fleet.

The nuclear industry has set the target. Now it needs to build the capacity to deliver it.

The post Nuclear Power Could Triple by 2050 as It Helps Avoid 43.6 Billion Tonnes of CO₂ appeared first on Carbon Credits.